
Meet the “toll sales space” of digital transactions: Visa. The Every day Breakdown dives into this firm’s enterprise to see what’s occurring beneath the hood.
Earlier than we dive in, let’s be sure you’re set to obtain The Every day Breakdown every morning. To maintain getting our each day insights, all you could do is log in to your eToro account.
Deep Dive
Yesterday we regarded on the charts for Visa and in the present day we’re taking a deeper dive into the basics. Visa shares have struggled for the reason that inventory hit a report excessive in June, down about 7.5%. Regardless of that, Visa is up about 26% over the previous 12 months and sports activities a powerful long-term observe report, up 368% over the past decade. For context, the S&P 500 is up “simply” 233% in that span.
The Enterprise
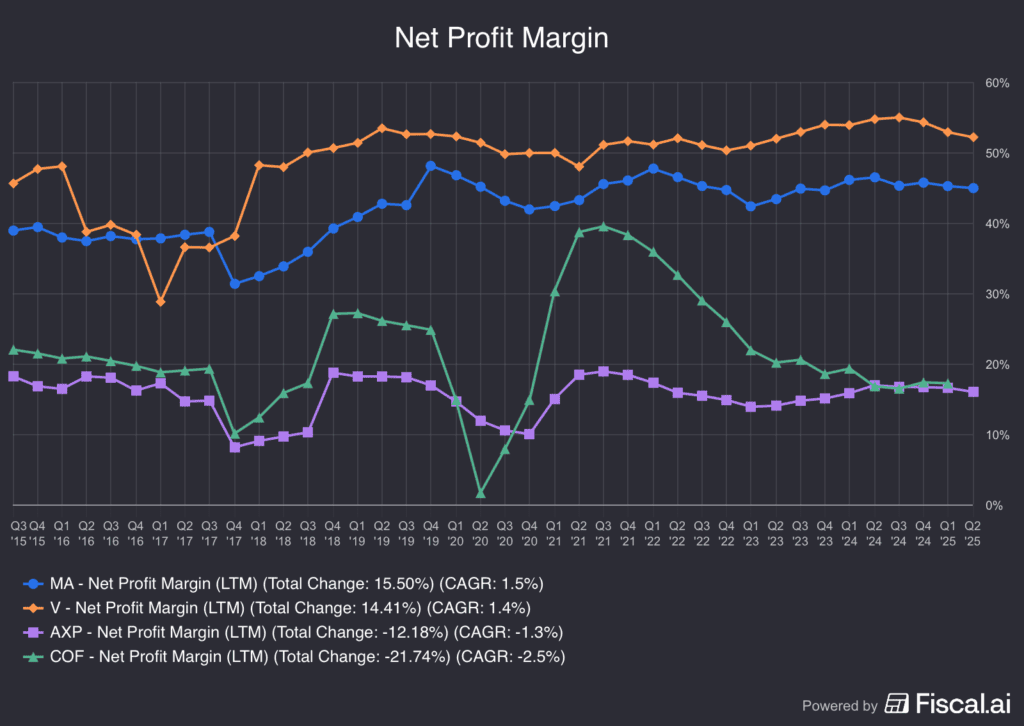
Buyers know Visa as a credit score and debit card firm — that a lot is apparent. Nevertheless it’s sometimes called the “toll sales space” of digital transactions. MasterCard enjoys an identical distinction. And whereas there are different bank card firms — like American Specific, Capital One, and Synchrony Monetary — in addition they perform as banks. Whereas there are professionals and cons to every enterprise mannequin, Visa and MasterCard command a lot larger revenue margins with their enterprise.
Development
Visa has grown its income and earnings at a compound annual progress charge (CAGR) of 11.1% and 15.7%, respectively. Trying ahead, analysts count on spectacular outcomes as properly, together with:
Income progress estimates*: 11.4% in 2025, 10.6% in 2026, and 10% in 2027.
Earnings progress estimates*: 15.3% in 2025, 12.3% in 2026, and 12.7% in 2027.
*Estimates in line with Fiscal.ai
Wish to obtain these insights straight to your inbox?
Join right here
Diving Deeper: Valuation
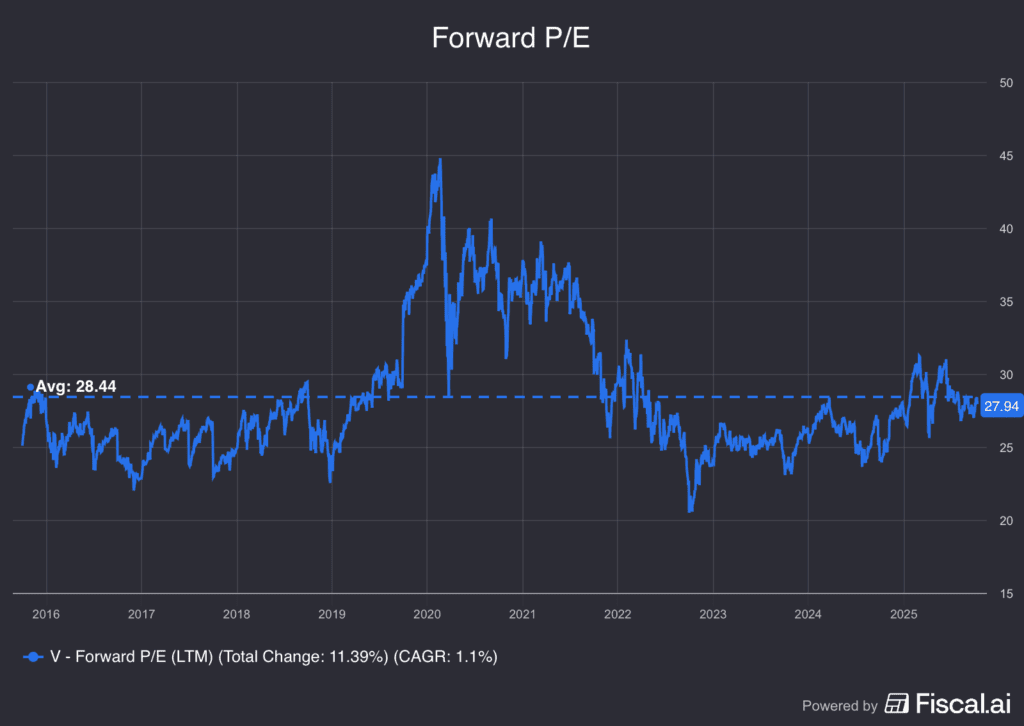
Buying and selling at roughly 28x ahead earnings expectations, Visa inventory is about in-line with its long-term common. The inventory has been thought of comparatively low cost when shares commerce at about 23x to 24x ahead earnings and costly within the low- to mid-30x. Traditionally, many traders have justified Visa’s premium valuation as a consequence of its elevated progress charges and excessive margins.
Dangers & Backside Line
The primary dangers to Visa are fairly apparent: Market volatility and financial exercise.
If market volatility picks up, Visa isn’t immune. As an illustration, the inventory suffered a peak-to-trough decline of ~18.5% earlier this 12 months amid the tariff tantrum. Whereas this was really higher than the S&P 500’s swing of 21.3%, it’s nonetheless an enormous swing.
The opposite threat can be an financial slowdown or a recession. As a result of Visa is a world firm, a world or US slowdown can be a unfavourable for a lot of companies — bank card firms included — particularly in the case of consumption.
The Backside Line: Buyers who consider Visa will proceed to generate sturdy top- and bottom-line progress could justify the inventory’s valuation, which is at a slight premium to the S&P 500 however roughly in-line with its long-term common. Those that view the inventory as unattractive at present ranges could look forward to Visa’s valuation to probably dip to a extra enticing degree or they could not like Visa’s enterprise and resolve to ignore it altogether.
Disclaimer:
Please observe that as a consequence of market volatility, among the costs could have already been reached and situations performed out.


