
The Each day Breakdown digs into Uber’s enterprise, its flip to profitability, the inventory’s valuation, and the dangers that it faces in its trade.
Earlier than we dive in, let’s be sure you’re set to obtain The Each day Breakdown every morning. To maintain getting our day by day insights, all you’ll want to do is log in to your eToro account.
Deep Dive
We all know Uber as a premium ride-hailing service that operates world wide. Nevertheless, the corporate has delved into a number of service choices to convey extra worth to its finish consumer. Uber operates out of three fundamental enterprise segments: Mobility (which connects riders with drivers), Supply (which hyperlinks customers with eating places, grocers, and retailers), and Freight (which matches shippers with carriers).
Shares hit a document excessive of $101.99 in September and lately dipped as little as $81.51, the place Uber discovered key help. Whereas it might not appear like Uber inventory has been in demand, traders ought to notice that shares are at the moment up about 50% to date this yr. A part of that “low-demand” narrative is the concept that Uber can be a significant loser — moderately than a significant winner — when autonomous autos (AVs) finally acquire extra traction (be it from Alphabet’s Waymo, Tesla, or one other entity solely).
Uber Turns Towards Profitability
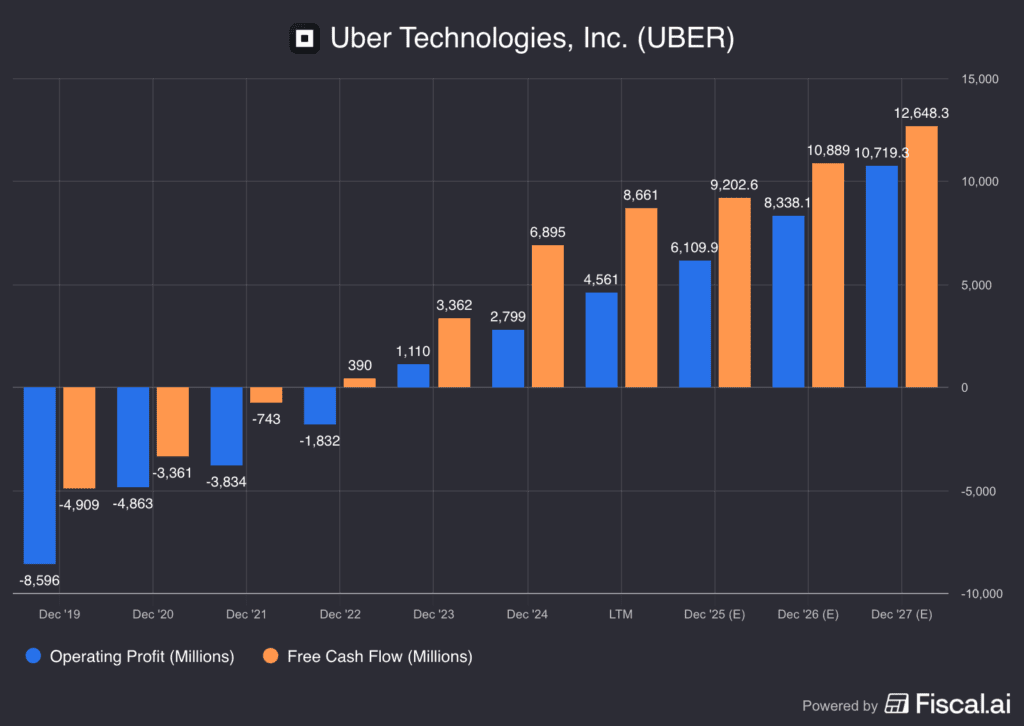
Uber has gone from $13 billion in income in 2019 to an expectation of about $52 billion in income this yr. That’s good for a compound annual development charge (CAGR) of ~22%. However maybe extra vital than income development has been the corporate’s flip to profitability. Discover on the chart above the best way Uber’s working revenue and free money stream each turned from detrimental to constructive. Additionally discover the way it has continued to enhance annually over these stretches — and the way they’re forecast to proceed in 2026 and 2027.
Future Progress Projections
Whereas Uber has demonstrated sturdy development traditionally, analysts suspect that there’s extra fuel left within the tank. In line with Bloomberg, analysts venture the next:
Working Earnings Progress: 100% in 2025, 50.3% in 2026, and 27.7% in 2027
Income Progress: 18.1% in 2025, 16.4% in 2026, and 14.5% in 2027
Analysts at the moment have a consensus value goal of ~$116 on Uber inventory, implying about 28% upside to at this time’s inventory value.
Wish to obtain these insights straight to your inbox?
Enroll right here
Diving Deeper
Uber inventory has had an enormous 2025 and has greater than quadrupled from its 2022 bear market low. Regardless of the big transfer in its inventory value, sturdy development has stored the valuation in verify.
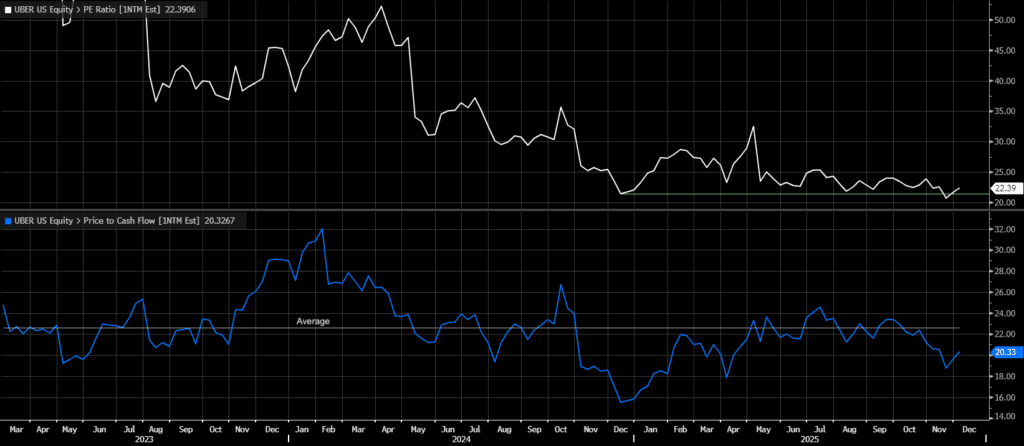
In line with Bloomberg, Uber’s at the moment under its common ahead price-to-free-cash-flow (P/FCF) ratio of the final a number of years, whereas its ahead price-to-earnings ratio (fP/E) stays within the low 20s, an space that marked a low level round this time final yr. That doesn’t imply Uber inventory can’t go decrease, however the valuation won’t be as wealthy as some traders might imagine.
Dangers
Uber has clearly achieved effectively, each from a basic standpoint and in its capacity to create worth for its shareholders. However that doesn’t imply it isn’t with out dangers.
From its current excessive to the current low, shares tumbled 20% — exhibiting outsized volatility vs. the broader market. Additional, Uber’s ties to the journey trade exposes it to the cyclical nature of the economic system. Ought to shopper exercise sluggish, Uber’s enterprise might sluggish too. (The other can be true although: ought to the economic system speed up, Uber’s enterprise might see a lift). Lastly, whereas Uber very effectively could possibly be a beneficiary of AVs, the market has regularly handled it as a detrimental for Uber, in order that threat might persist shifting ahead.
Disclaimer:
Please notice that on account of market volatility, among the costs could have already been reached and situations performed out.


