
The rise of Money2 marks a turning level within the historical past of finance, the place the dominance of banks and paper-based techniques provides option to stablecoins, good contracts, and automatic blockchain infrastructure.
The dialog round financial institution disruption is heating up as a result of Money2 addresses probably the most persistent flaws in conventional finance: excessive charges, gradual settlements, and restricted accessibility. Stablecoins allow near-instant 24/7 funds, whereas DeFi platforms replicate lending, financial savings, and buying and selling companies with out counting on bodily branches or human gatekeepers.
This transformation is being pushed by a robust mixture of decentralized finance, stablecoins, and automation. Collectively, they’re reshaping how cash is created, saved, and transferred. If the momentum continues, Money2 may develop into the spine of a quicker, extra open, and extra inclusive monetary system.
What’s Money2 and How It Differs from TradFi
The TradFi vs DeFi distinction is vital: in TradFi, establishments act as central authorities, whereas in DeFi, protocols distribute management by means of open code. Money2 represents the emergence of a brand new monetary paradigm powered by digital property, DeFi, and good contracts.
It’s constructed on core ideas: decentralization, the place management lies in clear code, not establishments; transparency, each transaction is verifiable on public blockchains; and programmability, cash behaves like software program, flowing in response to predefined guidelines reasonably than handbook processes.
By early 2025, stablecoin provide had reached $225 billion, attaining 63% year-over-year development. It is a clear sign that Money2 is already reshaping international worth switch exterior the standard banking infrastructure.
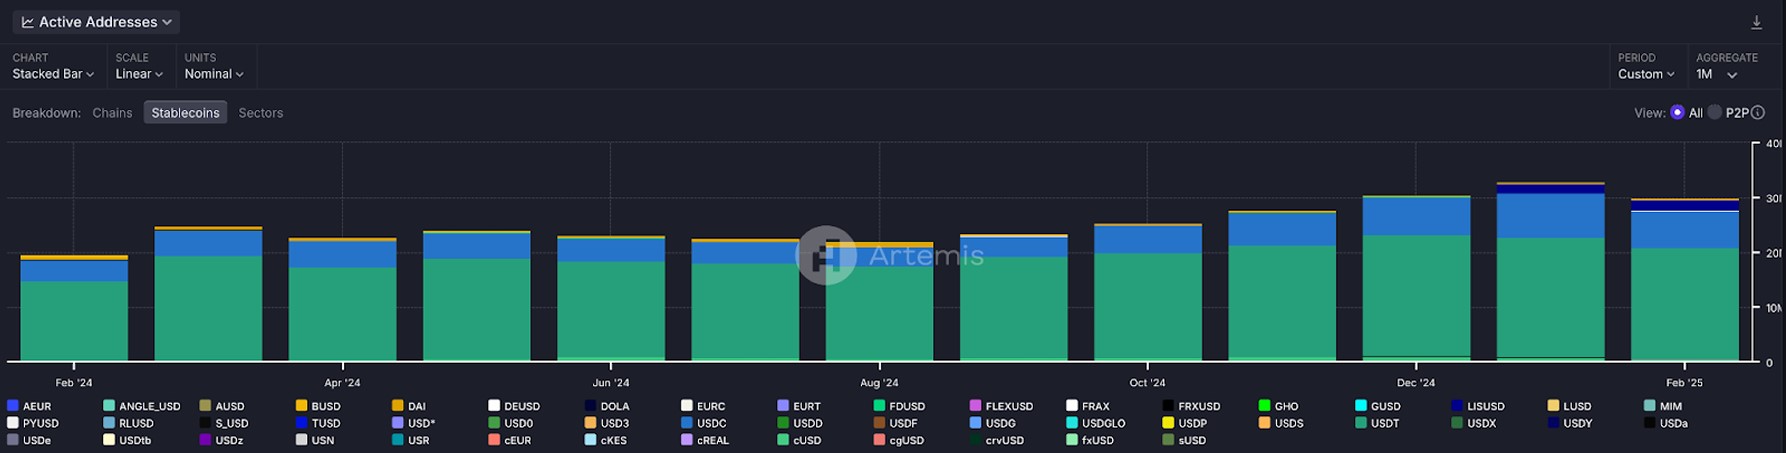
Funds, lending, and asset transfers will be executed robotically with out human oversight or intervention. This code-driven mannequin reduces charges, speeds friction, and the danger of gatekeeping; any person with a pockets can take part instantly within the ecosystem.
In conventional banking, shifting cash usually includes a number of establishments, handbook compliance checks, delayed settlement, and hidden charges. Transfers could take days and depend on clearing homes or SWIFT messaging. In distinction, Money2 transactions normally settle in seconds, function 24/7, and are verifiable on-chain.
Good contracts implement programmatic situations, like escrow or collateral guidelines, with out handbook approval. This essentially shifts monetary duty from establishments to open, verifiable code, providing a extra environment friendly, accessible, and clear different to legacy techniques.
The Position of Stablecoins in Money2
Stablecoins are sometimes referred to as the “digital money” of DeFi as a result of they mix the soundness of conventional foreign money with the velocity and accessibility of blockchain. In contrast to risky cryptocurrencies like Bitcoin or Ethereum, stablecoins are pegged to secure property, mostly the U.S. greenback, making them a predictable medium of trade.
This stability permits them to operate like money within the DeFi ecosystem. You possibly can ship, obtain, and retailer worth with out worrying about sudden value swings, making them perfect for on a regular basis use and huge transactions alike. Stablecoins additionally gasoline DeFi buying and selling, appearing as a secure medium of trade on decentralized exchanges like Uniswap or Curve.
Use Circumstances: funds, remittances, on-chain financial savings
Retailers and platforms can settle for stablecoins with out going through the volatility dangers of different crypto property. Transactions settle in minutes and will be despatched globally with out the excessive charges of bank cards or wire transfers.
For instance, Shopify retailers utilizing Coinbase Commerce can settle for USDC funds immediately, avoiding card charges and chargebacks. In El Salvador, some espresso retailers settle for USDT instantly from prospects’ crypto wallets.

For cross-border transfers, stablecoins supply a quicker, cheaper different to conventional cash switch companies. Sending USDC or USDT to household overseas usually prices pennies in charges and avoids days of ready.
For instance, Filipino abroad staff use USDT on Tron to ship cash dwelling, the place family money out at native exchanges for near-zero charges in comparison with Western Union’s 5–10% prices. In Nigeria, freelancers obtain stablecoin funds through Binance Pay to bypass restrictive banking guidelines.
In DeFi, stablecoins will be deposited into lending platforms or liquidity swimming pools to earn curiosity, offering a safe option to develop financial savings with out publicity to crypto market volatility.
For instance, customers deposit DAI into Aave or Compound to earn annual yields, or stake USDC in Curve Finance swimming pools to earn buying and selling charges. Platforms like Yearn Finance robotically optimize returns on stablecoin deposits.
Past financial savings, stablecoins are a core element in DeFi buying and selling, enabling customers to swap property effectively with out counting on centralized platforms.
DeFi Lending vs Financial institution Loans
The talk of DeFi vs banks is changing into extra related as customers flip to platforms like Aave and Compound that provide lending companies with out conventional gatekeepers.
Debtors deposit crypto as collateral, and lenders provide liquidity to the protocol in trade for curiosity. All the course of is automated on the blockchain, from collateral administration to curiosity funds, decreasing prices and enabling 24/7 entry.
In contrast to conventional banks, there aren’t any department visits, prolonged purposes, or credit score checks; the one requirement is a suitable crypto pockets.
Rates of interest, collateral fashions, and international accessibility
DeFi rates of interest are decided algorithmically primarily based on provide and demand. For instance, if demand for borrowing stablecoins will increase, the borrowing fee rises to encourage extra lending. Collateral necessities are usually increased than in banking, usually 120% to 150% of the mortgage quantity, to guard lenders from value volatility.
Nonetheless, DeFi loans are borderless: somebody in Nigeria can borrow USDC from a lender in Canada immediately, with out foreign money conversions or worldwide banking charges. This international attain makes DeFi particularly engaging in nations with restricted entry to reasonably priced credit score.
Transparency vs opacity in mortgage processes
The DeFi vs banks comparability additionally highlights a basic distinction in transparency. In DeFi, customers can confirm phrases and transactions immediately. All transactions, rates of interest, and collateral ranges are seen on the blockchain in actual time, and anybody can audit the good contract code.
In distinction, financial institution loans usually contain opaque processes, hidden charges, and choices made behind closed doorways, with prospects counting on the financial institution’s inner threat fashions.
Whereas DeFi’s transparency builds belief, it additionally signifies that customers should take duty for understanding the dangers, as there’s no central authority to reverse errors or supply protections like deposit insurance coverage.
Are Banks Adapting or Falling Behind?
Some forward-thinking banks are actively testing blockchain and digital asset integration. JPMorgan Chase operates its personal permissioned blockchain community, Onyx, which facilitates tokenized deposits and cross-border funds. HSBC has piloted tokenized gold and digital bond platforms.
Customary Chartered and BNY Mellon have launched custody companies for cryptocurrencies, whereas Santander has experimented with blockchain-based worldwide transfers. These initiatives present that conventional establishments are exploring blockchain as a option to modernize funds, settlement, and asset administration processes.
Structural challenges stopping quick adaptation
Regardless of these experiments, banks face vital hurdles in adopting blockchain and “Money2” techniques at scale. Regulatory compliance is advanced, particularly when coping with decentralized protocols that lack clear oversight.
Legacy IT infrastructure is one other barrier; many banks function on decades-old techniques which might be pricey and time-consuming to exchange. Moreover, risk-averse company cultures make fast innovation troublesome, as banks should steadiness shareholder expectations, regulatory obligations, and buyer belief.
Might banks coexist with Money2 or get replaced completely?
Banks may coexist with Money2 by changing into gateways that present regulated entry to digital property, stablecoins, and decentralized monetary companies. For example, they might supply hybrid accounts the place prospects maintain each fiat and tokenized property.
Nonetheless, if DeFi and blockchain-based cost networks proceed to enhance in velocity, cost-efficiency, and user-friendliness, they might bypass banks altogether for a lot of monetary companies, from lending to cross-border funds.
In the end, whether or not banks adapt or get changed will rely on their willingness to embrace open finance reasonably than compete towards it.
Implications for Monetary Inclusion
Money2 has the potential to enhance monetary inclusion by eradicating conventional limitations and increasing entry to monetary companies. Listed here are the important thing methods it could possibly make a distinction:
Increasing entry to the unbanked and underbanked
Money2 has the potential to convey monetary companies to the 1.4 billion unbanked adults worldwide who lack entry to conventional banking. With solely a smartphone and web connection, people can retailer worth, ship funds, and entry credit score by means of decentralized platforms.
Decreasing prices for on a regular basis transactions
Conventional banking techniques usually impose excessive charges for remittances, worldwide transfers, and small transactions, making them prohibitive for low-income customers. Money2 options can cut back switch charges from a mean of 6–8% (through banks or Western Union) to underneath 1%. This price discount permits more cash to remain within the palms of households and small companies, instantly supporting native economies.
Empowering micro-entrepreneurs and small companies
By bypassing the delays and necessities of conventional credit score techniques, DeFi lending platforms can prolong microloans to entrepreneurs in rising markets who would in any other case be excluded. For example, protocols like Goldfinch supply crypto-collateralized credit score strains to small lenders in growing nations, enabling them to fund native companies rapidly and at aggressive charges.
Potential challenges to inclusion
Whereas Money2 can improve inclusion, it’s not with out hurdles. Digital literacy, dependable web entry, and regulatory readability stay limitations in lots of areas. There’s additionally the danger that, with out correct safeguards, predatory lending or risky digital property may hurt weak populations. Addressing these challenges might be key to making sure that monetary innovation genuinely advantages these at present excluded from the worldwide monetary system.
Closing Ideas
Because the DeFi vs banks dynamic continues to evolve, we’re prone to see a redefinition of banking roles. Whereas Money2 is already eroding a number of the banking features, full-scale displacement will seemingly unfold over the following decade or extra. Adoption will rely on how rapidly shoppers, companies, and establishments develop comfy with on-chain techniques and on how nicely the infrastructure scales to fulfill international demand.
Regulation would be the deciding consider how far and how briskly this transition occurs. Clear, balanced guidelines can encourage innovation whereas defending shoppers, making it simpler for institutional capital to stream into blockchain-based finance. Then again, overly restrictive legal guidelines may gradual adoption and push exercise into unregulated or offshore markets.
Good contracts received’t essentially get rid of banks, however they are going to pressure a redefinition of their position. As a substitute of being intermediaries for each transaction, banks could evolve into custodians, compliance hubs, and repair suppliers that combine with blockchain networks. On this future, banking may develop into much less about holding your cash and extra about serving to you work together safely and effectively with programmable monetary techniques.
Disclaimer: This text is meant solely for informational functions and shouldn’t be thought of buying and selling or funding recommendation. Nothing herein ought to be construed as monetary, authorized, or tax recommendation. Buying and selling or investing in cryptocurrencies carries a substantial threat of monetary loss. All the time conduct due diligence.
If you need to learn extra articles like this, go to DeFi Planet and observe us on Twitter, LinkedIn, Fb, Instagram, and CoinMarketCap Neighborhood.
Take management of your crypto portfolio with MARKETS PRO, DeFi Planet’s suite of analytics instruments.”

