
FinovateSpring 2026 involves sunny San Diego, California, from Might 5 to 7. Tickets are on sale and going quick. Save your spot, e book your room, and prepare for a full-court press on most of the largest points in fintech as we speak: from AI and embedded finance to stablecoins and hyperpersonalization within the buyer expertise.
As we speak we spotlight eight prime fintech traits that can dominate the dialog at FinovateSpring this yr—from major stage plenary keynotes to govt briefings and particular highlight classes. We’re additionally showcasing the place on the agenda you will discover shows and panel discussions on every theme.
It’s All About Agentic AI
AI is undeniably essentially the most compelling and in-demand expertise in banking and monetary companies as we speak—and the innovation in AI that’s attracting essentially the most consideration is agentic AI. Agentic AI techniques are designed with a level of autonomy and decision-making means that permits them to finish an increasing vary of duties independently with out requiring human intervention. In a comparatively brief time, this expertise has developed from pilot initiatives to powering e-commerce, fraud prevention, automated funding, credit score danger evaluation, and extra.
Agentic AI classes at FinovateSpring
Getting Critical about Stablecoins in Monetary Companies
With rising use circumstances in monetary companies and growing regulatory readability, stablecoins have grow to be essentially the most constructive innovation to emerge from the DeFi motion. From cross-border funds and remittances to serving as a secure medium of alternate, retailer of worth, and hedge towards volatility for cryptocurrency customers, stablecoins allow banks and different monetary establishments to leverage blockchain innovation whereas benefitting from value stability.
Stablecoin classes at FinovateSpring
Making Embedded Finance Work for Banks
Whereas a lot of the dialog about embedded finance focuses on the way it empowers non-financial entities to supply monetary companies, it’s also true that embedded finance gives banks and different monetary companies suppliers a strategy to scale and diversify their choices whereas reaching new markets, clients, and members.
Embedded finance classes at FinovateSpring
A Warmth Examine on the Open Banking Alternative within the US
Open banking and finance are thriving in lots of locations world wide, and whereas there have been features within the US, it nonetheless lags behind friends in Europe and Australia. The absence of a regulatory mandate makes open banking within the US largely a market-driven phenomenon, however the continued debate over Part 1033 of the Dodd-Frank Act (which ensures shoppers can entry their monetary information upon request) creates uncertainties and challenges for banks and fintechs concerning information sharing and the extent of buyer management over their information.
Open banking classes at FinovateSpring
Combating Monetary Crime: New Challenges, New Options
Utilizing AI to remain forward of AI-wielding fraudsters and monetary criminals has been a key technique for fintechs and monetary establishments aiming to guard themselves and their clients. On the identical time, a rising variety of firms are recognizing that, past technological options, collaborating to struggle widespread fraud threats gives vital advantages in comparison with corporations relying solely on their very own assets.
Monetary crime and cybersecurity classes at FinovateSpring
Leveraging Information, Analytics, and AI to Improve the Buyer Expertise
With extra information than ever earlier than at their disposal and highly effective new analytical capabilities—together with AI—at hand, monetary establishments are methods to raised serve their clients and members with more and more personalised services and products. In some ways, the flexibility to satisfy clients the place they’re—at house, on the go, or in the midst of a transaction—is more and more seen as a possibility for monetary establishments to distinguish their choices, in addition to study from and compete extra successfully towards non-financial rivals.
Hyperpersonalization classes at FinovateSpring
Third-Social gathering Danger and Constructing Higher Partnerships within the Publish-SVB Period
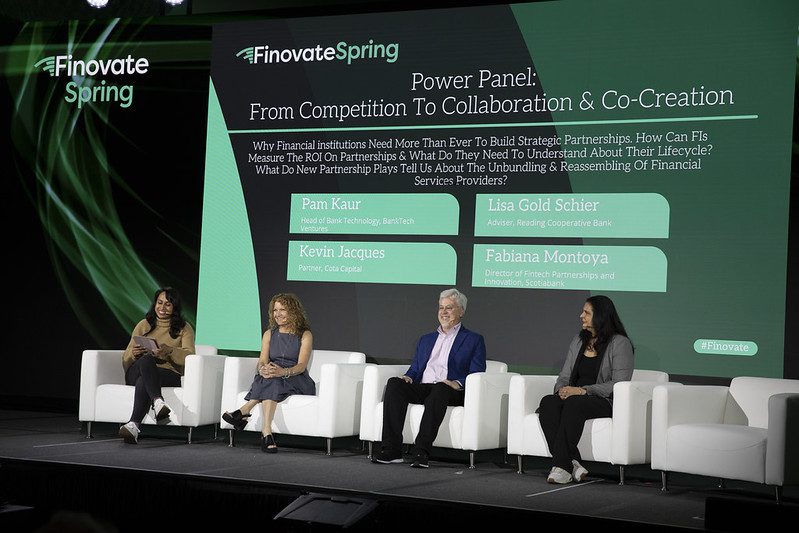
How are banks and fintechs addressing partnership and third-party danger within the post-SVB period? As regulators sharpen their deal with the dangers in bank-fintech partnerships—and a rising variety of fintechs resolve to “reduce out the intermediary” and grow to be banks themselves—it stays vital that banks and fintechs perceive what it takes to construct constructive alliances and collaborations that profit all stakeholders—together with regulatory our bodies.
Third-party danger/Financial institution-fintech partnership classes at FinovateSpring
Clients Nonetheless Rely on Credit score Unions and Neighborhood Banks
Massive nationwide banks could have the lion’s share of buyer cash, however with 73% of People having favorable views of credit score unions in comparison with 56% of People having favorable views of nationwide banks, it’s arduous to not see a possibility for smaller monetary establishments to leverage that belief into greater buyer bases, memberships, and deposits. Credit score unions and neighborhood banks that embrace modernization and fintech innovation will probably be finest positioned to supply the form of companies and merchandise that always appeal to clients to nationwide manufacturers.
Neighborhood banks and credit score union classes at FinovateSpring
Views: 55


