

MiCA Decoded is a 12-article weekly collection for Bitcoin.com Information, co-authored by LegalBison’s Co-Founding and Managing Administrators: Aaron Glauberman, Viktor Juskin and Sabir Alijev. LegalBison advises crypto and FinTech corporations on MiCA licensing, CASP and VASP purposes, and regulatory structuring throughout Europe and past.
There’s a model of the MiCA authorization course of that founders speak about as if it ends the second the license arrives. Apply, wait, get approved, function within the EU. The license is the end line.
That framing misreads what MiCA really authorizes. A Crypto-Asset Service Supplier (CASP) license grants permission to offer particular crypto-asset companies, outlined intimately within the regulation. It doesn’t grant permission to function a fee establishment, subject digital cash, or run a derivatives buying and selling venue. These actions sit beneath solely totally different regulatory frameworks. And for a lot of platforms whose business mannequin is determined by not less than certainly one of them, the MiCA license alone leaves a niche that’s operationally vital and, if ignored, legally critical.
This tenth installment of MiCA Decoded maps that hole exactly, service by service.
The Fantasy: MiCA Covers the Full Stack of What a Crypto Change Does
The belief is comprehensible. MiCA is complete. It covers ten classes of crypto-asset companies. Its scope extends to custody, change, execution, routing, recommendation, and portfolio administration. For many retail crypto platforms, that covers a considerable portion of their enterprise.
However “substantial” and “full” are various things. The platforms more than likely to find a major distinction will not be marginal operators. They’re those operating by-product merchandise, enabling crypto-funded card funds, providing leveraged perpetual positions, or internet hosting prediction markets. These prediction markets have change into a significant development for centralized exchanges (CEXes), but they sit at a regulatory boundary that MiCA doesn’t cross. As an alternative, they typically fall beneath native iGaming regulatory frameworks. These are commercially vital product traces at main exchanges, and each operates exterior MiCA’s scope.
The regulation is restricted about what it governs. Article 2(4) of MiCA explicitly excludes from its scope crypto-assets that qualify as monetary devices beneath Directive 2014/65/EU (MiFID II), deposits, funds as outlined beneath the Cost Companies Directive 2 (PSD2), and securitisation positions. These exclusions will not be technical footnotes. They outline the perimeter of MiCA’s authority. Something falling on the opposite facet of that perimeter requires authorization beneath a unique framework solely.
The place the CASP License Stops
Cost Companies
MiCA authorizes the switch of crypto-assets on behalf of shoppers, outlined in Article 3(1)(26) as “offering companies of switch, on behalf of a pure or authorized individual, of crypto-assets from one distributed ledger handle or account to a different.” This can be a crypto-native switch service. It isn’t a fee service within the PSD2 sense.
The excellence issues enormously for platforms that need to supply crypto-funded card applications, fiat on/off-ramp integrations, direct financial institution transfers, or service provider fee acceptance in euros or different official currencies. Article 2(4)(c) excludes “funds” as outlined in PSD2 from MiCA’s scope, besides the place they qualify as e-money tokens.
A platform that receives fiat or e-money tokens (EMTs) from a person, holds them, and transmits them someplace is working a fee service. This requires both a fee establishment license or an Digital Cash Establishment (EMI) license beneath Directive (EU) 2015/2366 (PSD2), fairly than only a Crypto-Asset Service Supplier (CASP) authorization. As a result of EMTs are legally deemed to be digital cash, CASP switch companies don’t cowl EMTs until the exercise falls beneath the “intermediation” exclusion.
A non-EMI CASP can transmit orders for EMTs provided that the transaction stays inside the CASP’s inner ecosystem or inside a custodial account managed by a licensed licensed associate. If a service includes transmitting an order that triggers the switch of an EMT to a third-party pockets or a non-public ledger, it constitutes the execution of a fee transaction or a cash remittance service beneath PSD2/PSD3. Any CASP facilitating these exterior transfers after March 2026 will need to have its personal EMI/PI license or use a licensed agent.
MiCA itself acknowledges this boundary. Article 70(4) states that crypto-asset service suppliers might themselves or by way of a 3rd occasion present fee companies associated to their crypto-asset service, however solely the place the supplier or the third occasion is permitted to offer these companies beneath PSD2. The regulation doesn’t grant fee companies functionality by way of the again door. It requires that the potential be independently approved.
For an change that wishes to let customers prime up by way of SEPA switch, settle redemptions in euros, or subject a branded debit card, a CASP license is a essential piece of the construction. It isn’t enough.
Perpetuals and Futures
That is the place the publicity tends to be sharpest for derivative-first platforms.
MiCA’s scope is outlined round “crypto-assets,” that are digital representations of worth or rights that may be transferred utilizing distributed ledger expertise. The regulation covers the companies constructed round these belongings: custody, buying and selling on spot markets, change, execution of orders in addition to routing of orders as a pure middleman. What it doesn’t cowl is monetary derivatives the place the crypto-asset is the underlying instrument fairly than the factor being traded.
Article 2(4)(a) removes from MiCA’s scope any crypto-asset that qualifies as a monetary instrument beneath MiFID II. A perpetual futures contract on BTC/USD isn’t a crypto-asset. It’s a by-product. It could settle in cryptocurrency, however the instrument itself, the contractual declare representing a leveraged place on the value of Bitcoin, is a monetary instrument within the MiFID II sense. Working a venue that enables EU shoppers to commerce such devices requires an funding agency authorization beneath MiFID II, or at minimal a buying and selling venue authorization relying on the construction, not a CASP license.
Recital 97 of MiCA addresses this straight, noting that derivatives qualifying as monetary devices beneath MiFID II and whose underlying asset is a crypto-asset are topic to Regulation 596/2014 (the Market Abuse Regulation), to not MiCA. The market abuse provisions nonetheless attain the underlying crypto-asset. However the authorization framework for the by-product product itself sits beneath MiFID II.
Some exchanges try to construction perpetuals as crypto-to- crypto swap preparations that they characterize as change companies fairly than derivatives. Regulators are conversant in this framing, and the classification query is finally certainly one of substance over type. An instrument with leverage, a funding fee, and no supply of the underlying asset is prone to face scrutiny as a by-product no matter how it’s labeled. The authorized threat of getting this improper is the supply of economic companies with out authorization.
Futures Contracts
The identical evaluation applies to dated futures. A futures contract obliging a counterparty to purchase or promote an asset at a predetermined worth on a future date is a monetary instrument beneath MiFID II, particularly inside the definitions protecting derivatives on commodities, currencies, and different underlyings. Cryptocurrency futures, even the place bodily settled in BTC or ETH, are handled as monetary devices when they’re traded on a multilateral foundation.
Working a buying and selling platform for such devices requires authorization as a regulated market, multilateral buying and selling facility (MTF), or organized buying and selling facility (OTF) beneath MiFID II. CASP authorization covers the operation of a buying and selling platform for crypto-assets beneath Article 76 of MiCA, which defines a buying and selling platform as a multilateral system bringing collectively a number of third-party buying and promoting pursuits in crypto-assets, not derivatives on crypto-assets.
In sensible phrases, this implies the CASP offers a venue the place shoppers meet and commerce with one another beneath clear working guidelines outlined and maintained by the CASP itself. The platform operator swimming pools and matches shopper orders to facilitate worth discovery fairly than setting costs. The CASP doesn’t take market threat, e book trades by itself sheet, or deal by itself account. The one exception is matched principal buying and selling, which the operator might have interaction in strictly with specific shopper consent and monitoring by the competent authority.
Each frameworks impose strict limits on permitted buying and selling fashions. Below MiFID II, multilateral buying and selling amenities (MTFs) are solely banned from executing shopper orders in opposition to proprietary capital or partaking in matched principal buying and selling. Organized buying and selling amenities (OTFs) are permitted to behave as matched principals for particular devices, corresponding to bonds, structured finance merchandise, emission allowances, and sure derivatives, however solely with specific shopper consent.
MiCA establishes comparable restrictions for crypto-assets. Crypto-asset service suppliers can not deal on their very own account on the buying and selling platforms they function. MiCA permits matched principal buying and selling as an exception, however solely the place the shopper has consented to the method. The supplier should provide the competent authority with data explaining its use of matched principal buying and selling. The competent authority then screens the engagement to confirm it continues to fall inside the strict definition of matched principal buying and selling and doesn’t give rise to conflicts of curiosity between the supplier and its shoppers.
Bitstamp, which holds MiCA authorization in Luxembourg beneath the Fee de Surveillance du Secteur Financier (CSSF), additionally holds a MiFID license allowing it to function an MTF. That twin licensing construction isn’t an accident. It displays the precise scope of the exercise.
Why Operators Miss This
A number of elements produce the misunderstanding.
First, the sensible impact of pre-MiCA nationwide VASP regimes assorted considerably by jurisdiction and over time. Whereas early registrations in some international locations might need initially operated as a permissive baseline, regulators grew to become more and more stringent.
In Estonia, for instance, the Monetary Intelligence Unit (RAB) actively scrutinized the precise companies offered by VASPs and investigated the supply of unlicensed monetary companies. By 2022, forward of MiCA’s enactment, Estonia applied strict amendments that explicitly banned the providing of futures and perpetuals beneath a VASP license. Operators obtained a brief 60 to 90-day grace interval to conform, which finally led to the mass revocation of hundreds of licenses.
Second, the CASP register entries themselves will not be all the time informative to founders studying them from the surface. An change listed as approved for “operation of a buying and selling platform” and “execution of orders” appears comprehensively approved. Whether or not it’s operating derivatives merchandise beneath a separate MiFID authorization requires studying past the CASP register solely.
Third, many platforms supply derivatives on crypto-assets to non-EU shoppers, and EU shoppers make up a minority of customers. The belief is that the EU publicity is manageable. However the reverse solicitation guidelines mentioned in earlier installments of this collection apply equally to unauthorized by-product companies. A platform advertising leveraged BTC perpetuals to international shoppers whereas concurrently making use of for a CASP license for its EU spot buying and selling product might discover that the 2 actions work together in methods the compliance staff didn’t anticipate.
The Regulatory Junctions
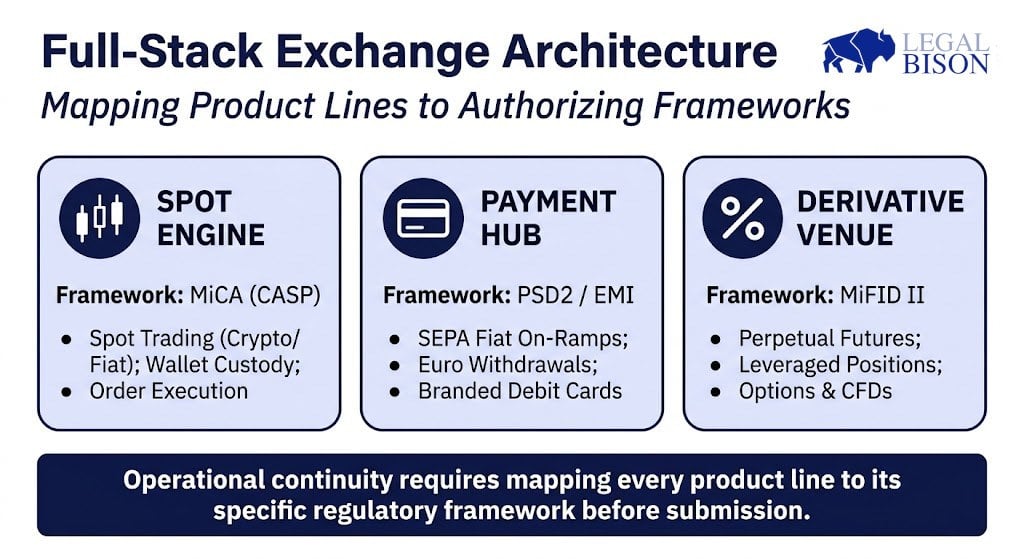
Three regulatory frameworks converge round most full-service crypto exchanges:
MiCA governs spot buying and selling, custody, switch companies, change, execution of orders, reception and transmission of orders, recommendation, and portfolio administration on crypto-assets. The CASP license is required and enough for these actions when offered to EU shoppers.
PSD2 and the EMI regime govern fee companies involving fiat. Any exercise involving the receipt, holding, or transmission of euro-denominated or different official forex funds requires both a fee establishment license (for fee initiation and cash transmission) or an EMI license (the place the platform shops fiat worth electronically as a declare redeemable at par). An change that enables customers to fund accounts by financial institution switch and withdraw in euros is, at minimal, touching a fee service. Whether or not that requires PSD2 authorization is determined by the precise stream and construction, however the query have to be assessed intentionally, not assumed away.
MiFID II governs derivatives. Futures, perpetuals, choices, and CFDs on crypto-assets are monetary devices. Working venues for his or her buying and selling, or offering funding recommendation and portfolio administration in relation to them, requires MiFID II authorization. The particular authorization kind, funding agency, regulated market, MTF, is determined by the enterprise mannequin.
Platforms working throughout all three classes want a construction that maps every product line to its authorizing framework. That may be a multi-license, multi-entity structure in some instances, not a single CASP utility.
What the Compliance Hole Appears Like in Apply
Take into account an change that:
Presents spot BTC/EUR buying and selling (CASP: change of crypto-assets for funds) Permits SEPA deposits and euro withdrawals (fee service, doubtlessly PSD2) Runs BTC perpetual contracts with as much as 20x leverage (by-product product, doubtlessly MiFID II) Presents a crypto-backed Visa card that spends euro balances (fee establishment functionality, PSD2/EMI)
A CASP authorization, standing alone, covers the primary merchandise with affordable confidence. The opposite three sit on the boundary. Whether or not they require unbiased authorizations, whether or not they are often structured as ancillary to the principle crypto enterprise, or whether or not they have to be routed by way of licensed third events are fact-specific questions. They aren’t questions the CASP license solutions.
That is precisely the kind of evaluation regulators will apply when reviewing a enterprise mannequin in the course of the authorization course of. The applying requires a programme of operations beneath Article 62(2)(d) of MiCA, which should set out the sorts of crypto-asset companies the applicant intends to offer, together with the place and the way these companies are to be marketed. A enterprise mannequin that features derivatives or fee companies should handle these components within the utility. Operators who deal with the CASP utility as protecting the complete scope of their enterprise threat having the NCA establish the hole earlier than they do, on the worst potential second within the authorization course of.
The Operational Consequence
For platforms already working within the EU beneath grandfathering provisions that expire July 1, 2026, the regulatory hole has a direct timeline consequence. A VASP registration doesn’t resolve the fee companies downside any greater than a CASP license will. These questions don’t disappear with MiCA authorization; they persist and change into extra seen to regulators whose supervisory instruments now match the formal authorization framework.
For platforms at present designing their EU market entry construction, the sequence issues. Mapping every product line to its authorizing framework comes earlier than selecting the jurisdiction for the CASP utility. The jurisdiction alternative impacts the CASP, but it surely additionally impacts the feasibility of layering PSD2 and MiFID II authorizations on the identical entity or inside the similar group.
Getting the structure improper is fixable. But it surely tends to be costly to repair after authorization, and it tends to floor in the intervening time the platform is rising quick sufficient that the regulators begin paying consideration.
What This Article Decoded
MiCA’s CASP license authorizes ten particular crypto-asset companies. It doesn’t authorize fee companies beneath PSD2, by-product buying and selling beneath MiFID II, or any exercise that falls beneath the monetary devices exclusion in Article 2(4)(a) of the regulation. Perpetuals and futures on crypto-assets are monetary devices within the MiFID II sense when structured as by-product contracts. Working buying and selling venues for these merchandise, or offering companies associated to them, requires MiFID II authorization unbiased of any CASP license. Fiat dealing with triggers PSD2. The receipt, storage, and transmission of euro-denominated or different official forex funds constitutes a fee service. A CASP license doesn’t authorize fee companies. This can be a structural hole for any change providing direct financial institution funding, fiat withdrawal, or crypto-funded card merchandise. Twin and triple licensing architectures are actual. Main exchanges with MiCA authorization that additionally run derivatives and fee merchandise usually maintain MiFID II and PSD2/EMI authorizations alongside the CASP. The construction isn’t unique; it displays the precise scope of a full-service crypto change working beneath EU legislation. The enterprise mannequin evaluation occurs earlier than the applying. NCAs reviewing CASP purposes will study the programme of operations. A enterprise mannequin that features derivatives or fee companies, unaddressed, creates publicity in the course of the authorization overview itself.
The CASP license is the mandatory basis for working a crypto change within the EU. It’s, in lots of instances, not enough.
This text is predicated on a research performed by LegalBison in Could 2026. The content material is for informational functions solely and doesn’t represent authorized recommendation.


