

MiCA Decoded is a 12-article weekly sequence for Bitcoin.com Information, co-authored by LegalBison’s Co-Founding and Managing Administrators: Aaron Glauberman, Viktor Juskin and Sabir Alijev. LegalBison advises crypto and FinTech firms on MiCA licensing, CASP and VASP purposes, and regulatory structuring throughout Europe and past.
Early in 2025, a crypto founder spent six months dismantling their British Virgin Islands group construction, shifting IP, redomiciling the treasury, and incorporating a brand new father or mother in Eire. Their attorneys had informed them MiCA meant Europe. In the event you wished to function within the EU, you wanted a European firm. Full cease.
They launched in early 2026, totally licensed, totally relocated, and totally European. Then they appeared on the ESMA public register.
Bybit’s world father or mother is integrated within the British Virgin Islands and headquartered in Dubai. Bybit EU GmbH, its Austrian subsidiary, holds the Markets in Crypto-Property Regulation (MiCA) license. OKX’s Seychelles entity sits on the prime of a construction whose Maltese subsidiary, OKX Europe Restricted, was approved by the Malta Monetary Companies Authority (MFSA). Crypto.com runs world operations by Singapore, whereas its EU-facing entity, Foris DAX MT Restricted, is a licensed Maltese crypto-asset service supplier.
None of those teams relocated. All of them are MiCA-compliant. And the ESMA register exhibits that token issuers from the BVI, the Cayman Islands, Panama, and Singapore have been submitting EU-compliant white papers because the regulation got here into pressure, with out incorporating a single EU entity.
So what does MiCA really require? And who was fallacious: the regulation, or the advisors?
The Delusion: It’s Unimaginable to Have an Offshore Construction With a MiCA License or Token
Earlier than decoding the structural actuality, it’s needed to know that MiCA governs two basically various kinds of actors. Conflating them is what produced the misunderstanding.
Crypto-Asset Service Suppliers (CASPs) are entities whose enterprise is offering crypto-asset providers to shoppers on an expert foundation. MiCA defines ten classes of such providers in Article 3(1)(16): custody and administration of crypto-assets, working a buying and selling platform, exchanging crypto-assets for funds or for different crypto-assets, executing orders, putting crypto-assets, receiving and transmitting orders, offering recommendation, offering portfolio administration, and offering switch providers. If what you are promoting mannequin includes any of those actions directed at EU shoppers, you’re a CASP. A centralized trade, a custody pockets supplier, a crypto dealer: all CASPs, regulated underneath Title V of MiCA and requiring authorization underneath Article 59.
Token issuers and offerors are a distinct class fully. These are the entities that create and supply crypto-assets to the general public, or search to have their tokens admitted to buying and selling on an EU platform. A mission launching a utility token, a layer-1 community distributing tokens at genesis, a DeFi protocol making its governance token obtainable to European buyers. All of those are token issuers or offerors, regulated underneath Titles II, III, and IV of MiCA, relying on the kind of crypto-asset concerned.
The obligations for every class are structurally totally different. The principles that apply to CASPs don’t apply to token issuers in the identical approach, and vice versa.
Many of the market commentary handled them as a single query: “Does MiCA apply to you?” The proper query is 2 distinct ones: “Are you a CASP?” and “Are you a token issuer or offeror?” The solutions decide which title of the regulation governs your scenario, and critically the place you must be integrated.
What the Regulation Truly Says
For CASPs: EU presence is obligatory
Article 59(2) of MiCA is unambiguous. A crypto-asset service supplier approved underneath Article 63 should have a registered workplace in a Member State the place it carries out not less than a part of its crypto-asset providers. The place of efficient administration have to be within the Union. No less than one director have to be resident within the Union.
This a part of the market assumption is appropriate. A BVI entity can’t acquire a CASP license. A Seychelles-incorporated trade can’t passport into Germany as-is. The MiCA authorization is granted to the entity, and that entity have to be meaningfully anchored contained in the EU. There is no such thing as a path round this particular requirement.
Article 68 provides the governance layer: members of the administration physique of a CASP have to be of sufficiently good reputation and possess the suitable information, abilities, and expertise, each individually and collectively, to carry out their duties. They have to be able to committing ample time to successfully carry out these duties. This isn’t a guidelines formality. The Nationwide Competent Authority (NCA) conducting the authorization evaluation assesses whether or not actual decision-making authority sits within the EU entity or whether or not it’s being exercised from elsewhere by a shell.
So sure, the CASP have to be European. However the CASP is one entity. MiCA says nothing about the place the CASP’s father or mother have to be integrated.
For token issuers: the image is totally different
For crypto-assets aside from asset-referenced tokens (ARTs) and e-money tokens (EMTs), the broad “different crypto-assets” class that covers utility tokens and most of what the market generally calls tokens, MiCA’s white paper requirement works very otherwise.
Article 4(1) requires that any particular person making a proposal to the general public of such a crypto-asset within the Union should, amongst different issues, be a authorized particular person. Not an EU authorized particular person. A authorized particular person. Article 8(1) specifies that offerors and individuals in search of admission to buying and selling should notify their white paper to the competent authority of their residence Member State, however then defines “residence Member State” for third-country entities in Article 3(1)(33)(c): the place the offeror is established in a 3rd nation, the house Member State is the Member State the place the crypto-assets are meant to be provided to the general public for the primary time, or, on the selection of the offeror, the Member State the place the primary software for admission to buying and selling is made.
In plain phrases: a BVI firm can notify a white paper to the Central Financial institution of Eire and supply its token to European buyers. It isn’t required to include in Eire to take action.
There’s a second path underneath Article 5(2) and 5(3). An individual in search of admission to buying and selling and the operator of the buying and selling platform could agree in writing that the operator will adjust to the white paper necessities. When a CASP takes this on, it assumes obligation for the accuracy and completeness of the disclosure. That is how exchanges like Kraken (Payward) or others have filed white papers for tokens with no centralized EU issuer. They agreed in writing to hold the duty, and the offshore mission didn’t want to have interaction an EU regulator instantly.
The necessary exception: this structural flexibility doesn’t prolong to ARTs or EMTs. For asset-referenced tokens, Article 16 requires the issuer to be established within the Union and approved by a reliable authority. For e-money tokens, Article 48 requires the issuer to be approved as a credit score establishment or digital cash establishment. These classes are categorically totally different, and the offshore shortcut just isn’t obtainable for both.
Why Confusion Took Maintain
Three issues went fallacious concurrently.
First, the commentary collapsed two separate questions into one. “Does MiCA apply to my firm?” turned the framing, and the CASP substance necessities had been utilized as the reply to all the pieces. Founders constructing token tasks examine Article 59(2) and assumed it utilized to them. It doesn’t, until they’re additionally working CASP providers.
Second, the substance necessities for CASPs are genuinely demanding. Studying Article 68 rigorously: the fit-and-proper evaluation, the collective experience requirement, the time-commitment obligations. It’s straightforward to know why early advisors concluded {that a} significant EU entity meant successfully shifting the enterprise to Europe. For a lot of candidates, the interior actuality of constructing a real EU administration layer felt indistinguishable from a relocation.
Third, the sensible challenges of early MiCA implementation strengthened warning. Some NCAs in late 2024 and early 2025 scrutinized CASP candidates with closely outsourced operations, and the business absorbed this as a sign that offshore constructions had been unwelcome. The sign was extra particular than that: hole EU entities with no real native substance had been unwelcome. That’s meaningfully totally different from saying offshore mother and father are prohibited.
Token Issuers Offshore: What the Register Exhibits
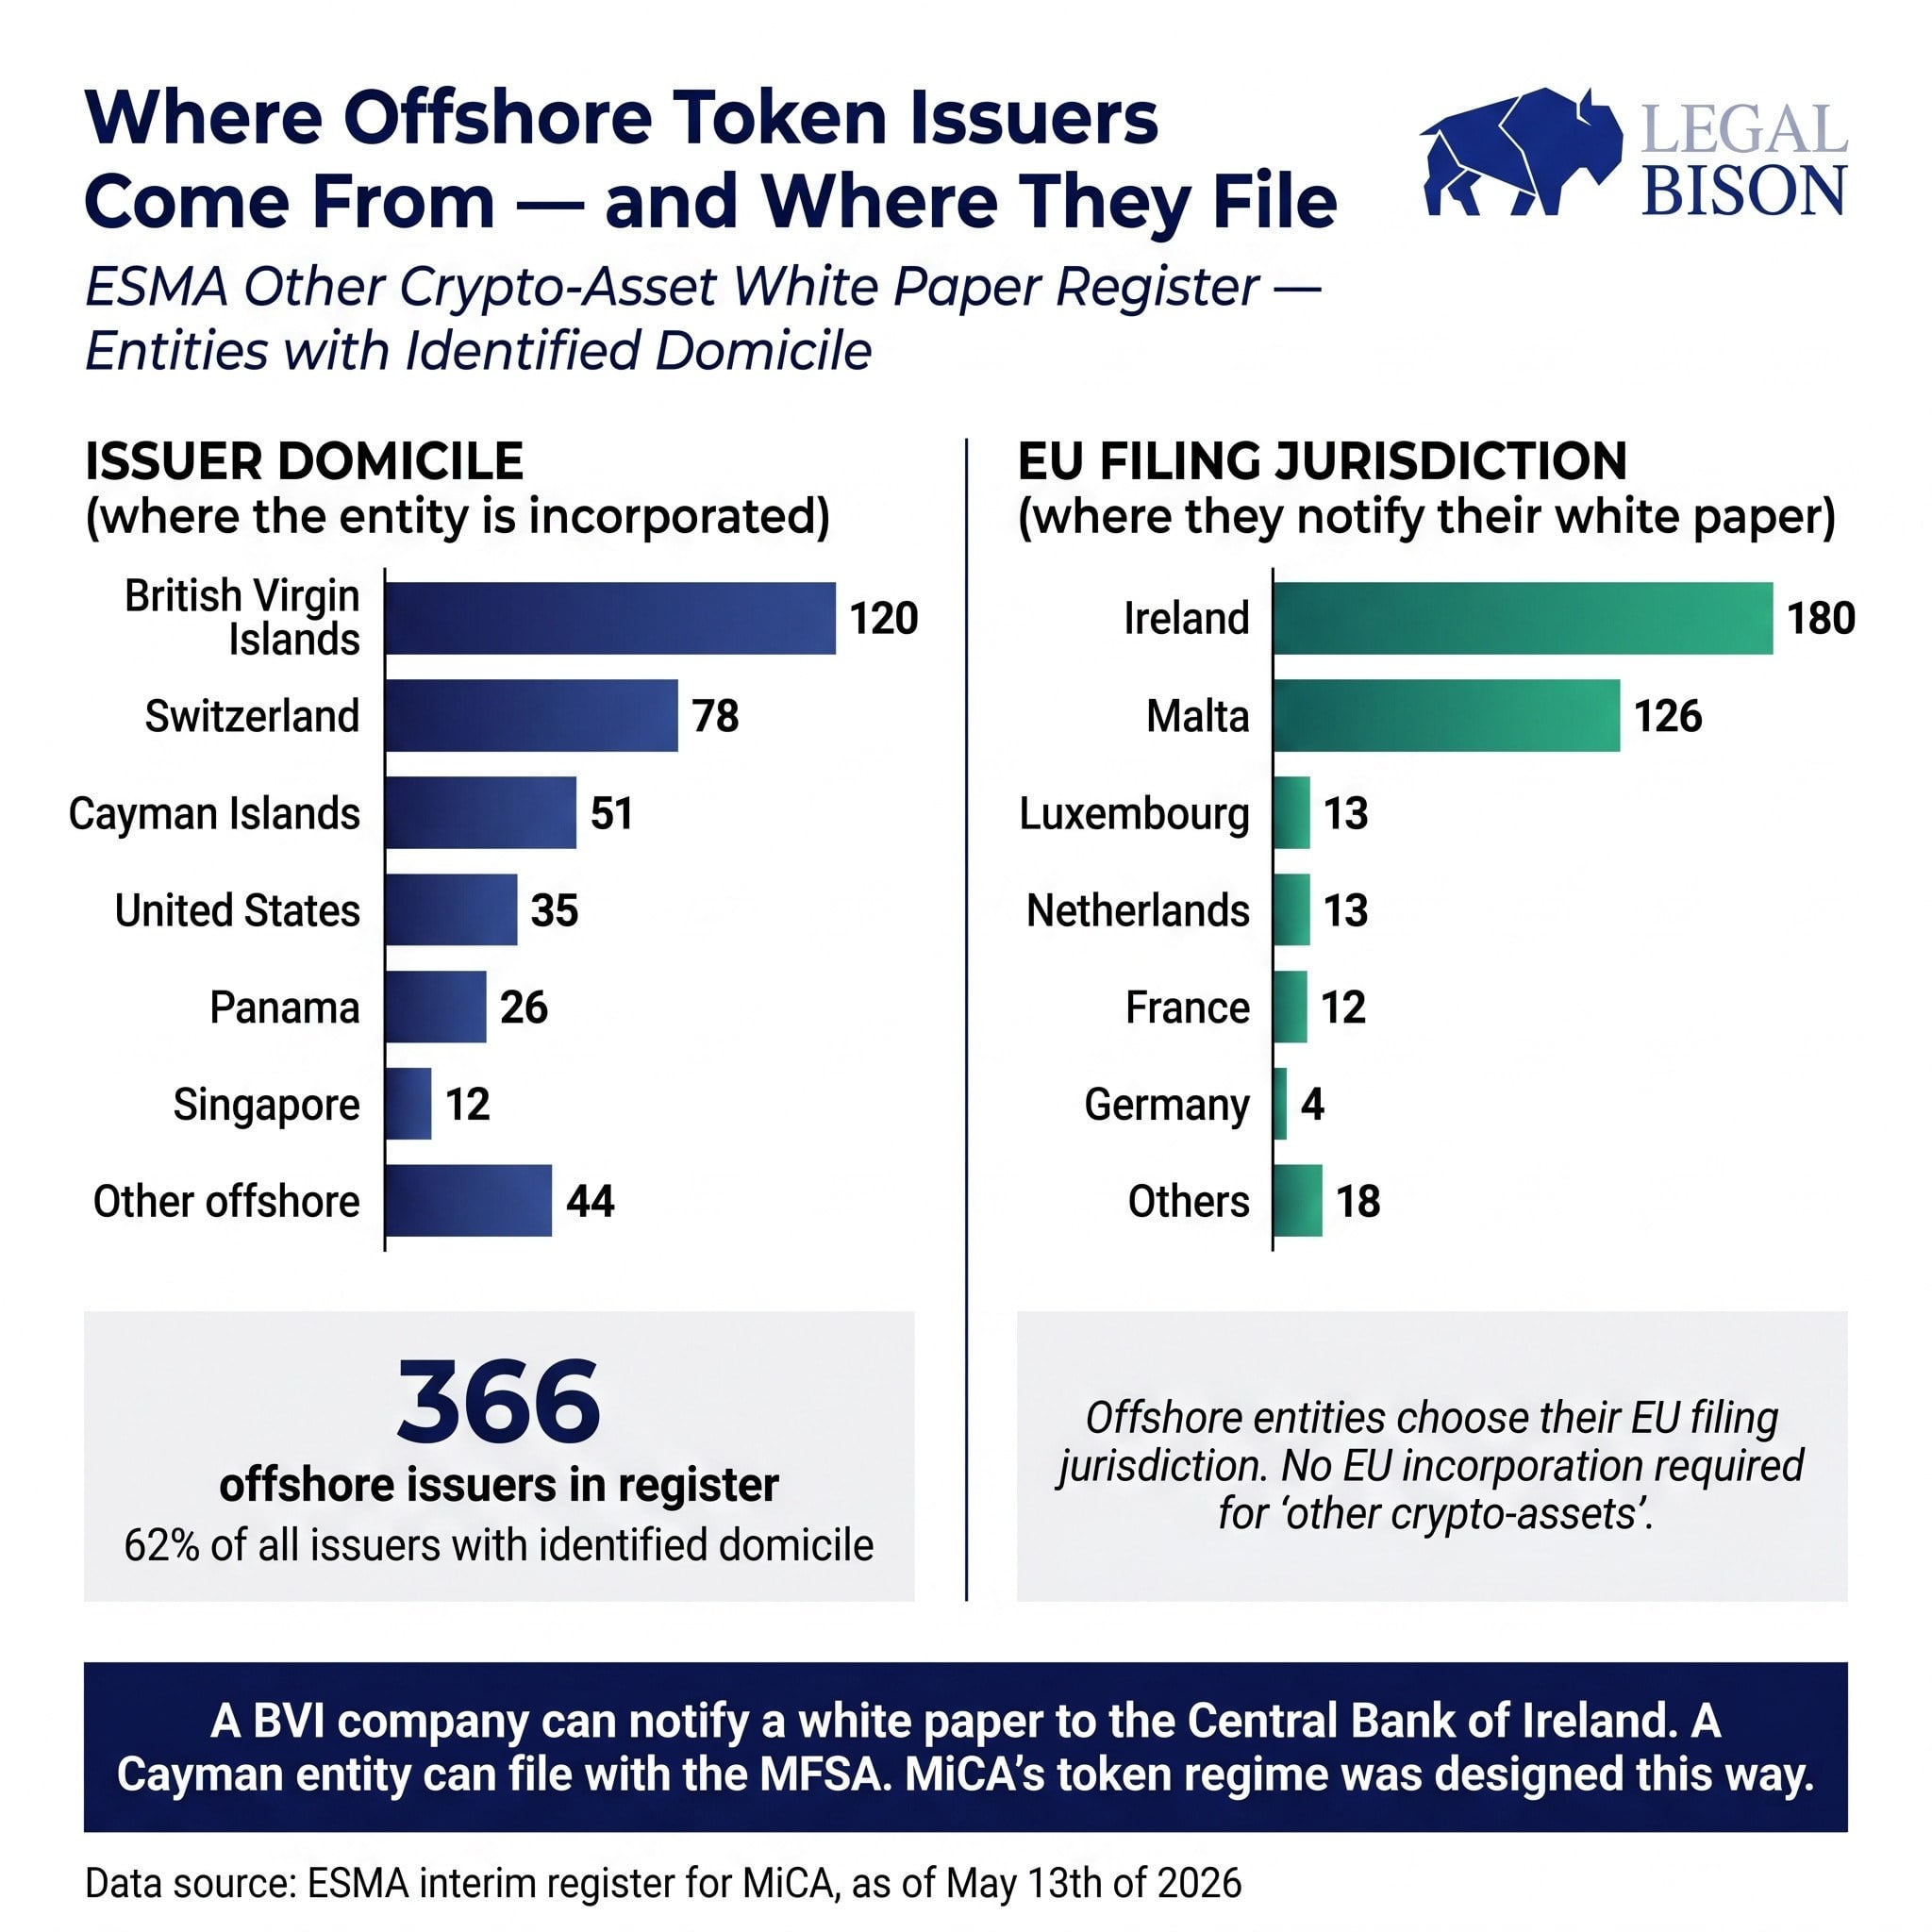
The ESMA public register of white papers for crypto-assets aside from ARTs and EMTs settles the query empirically. Of the 586 token issuers in that register with identifiable Authorized Entity Identifier (LEI) nation codes, 366 (62%) are domiciled exterior the EU or EEA.
The geography is hanging. 120 entities are integrated within the British Virgin Islands. 78 are in Switzerland. 51 are within the Cayman Islands. 26 are in Panama. 35 are integrated in america.
These entities selected their EU submitting jurisdictions intentionally. Eire acquired white paper notifications from 180 offshore issuers. Malta acquired 126. Luxembourg and the Netherlands every acquired round 13. BVI-incorporated entities alone filed 68 white papers in Eire and 33 in Malta.
The names within the register aren’t obscure tasks. Gensyn Community Ltd, a BVI firm, filed its white paper in France. Nexus Sub (BVI) Restricted filed in France, with Payward International Options (Kraken’s entity) listed because the CASP taking up the white paper obligation. The Horizen Basis, integrated within the Cayman Islands, filed in Germany. zkVerify Basis, additionally Cayman-based, equally filed in Germany. Init Capital Ltd, a BVI entity, filed in Eire.
None of those required an EU incorporation. The regulation supplied the trail instantly.
The Break up-Structure Mannequin: How It Works in Apply
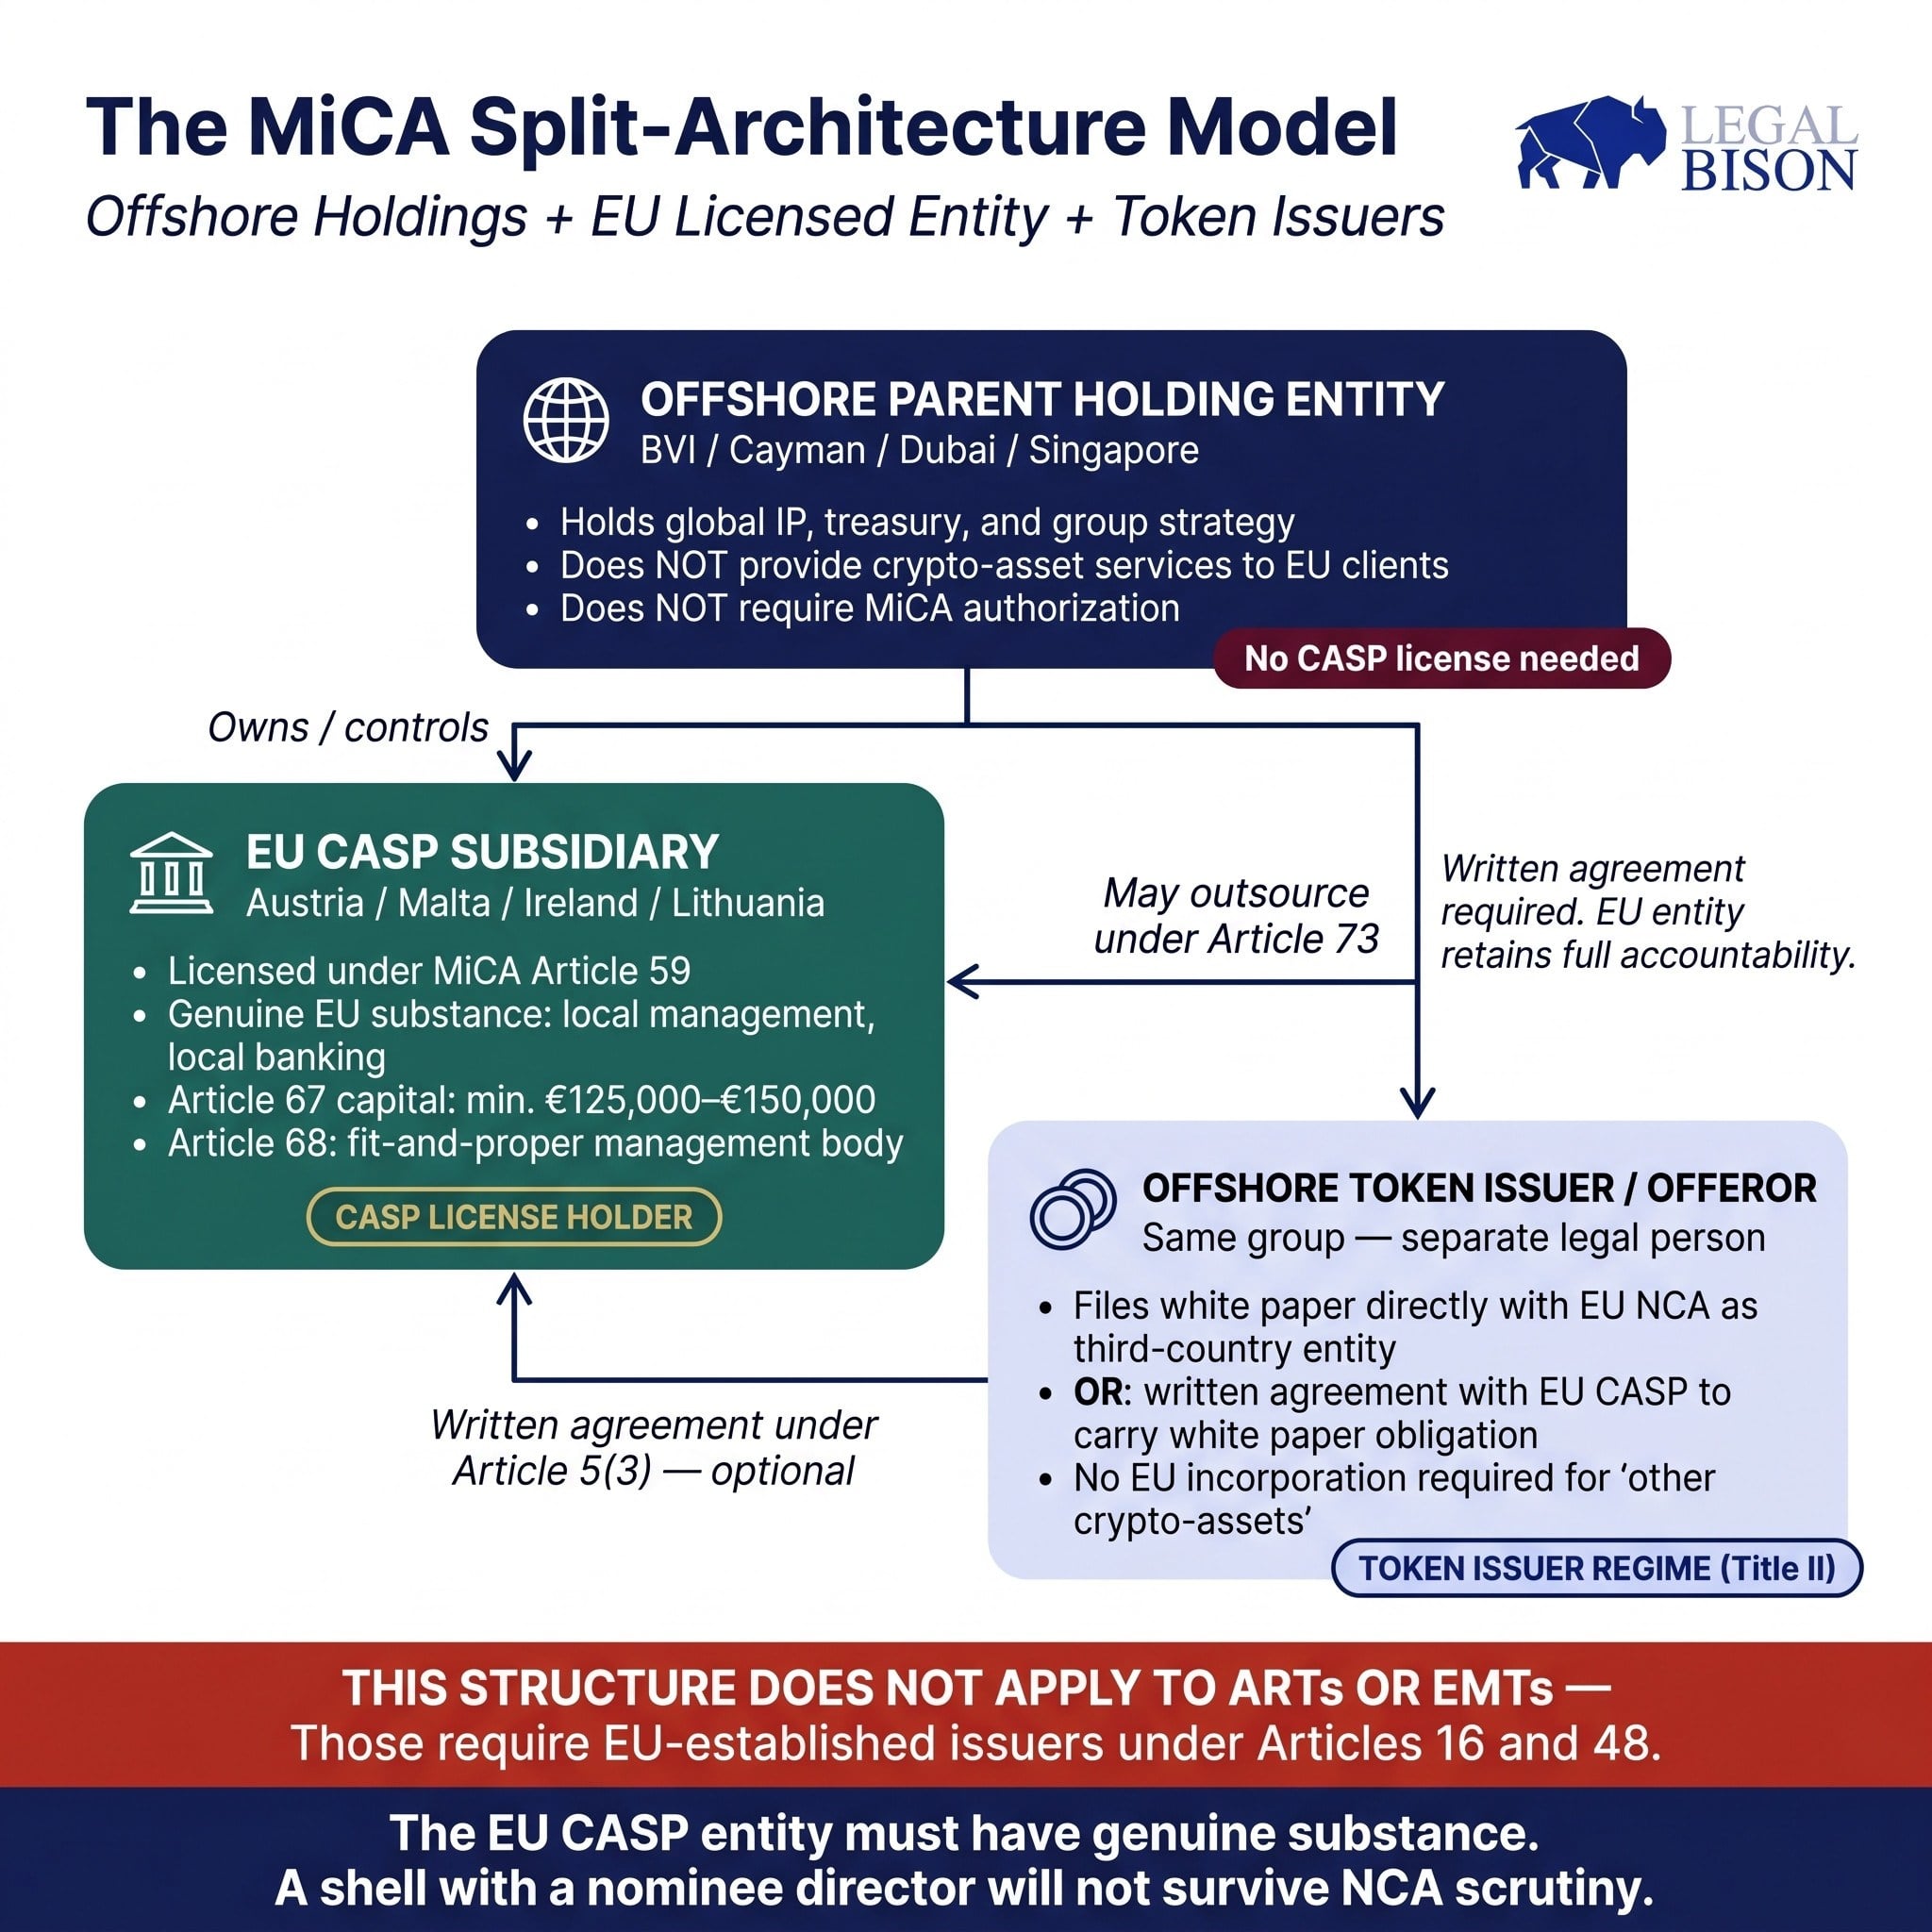
The structure that main exchanges use follows a transparent logic. Understanding it in sequence is beneficial.
On the prime sits an offshore holding entity. That is the place the group’s world treasury, mental property possession, and strategic features sometimes reside. The holding entity doesn’t present crypto-asset providers to EU shoppers. It doesn’t maintain a CASP license. It doesn’t want one.
Beneath it, an EU operational subsidiary is integrated in a Member State with a functioning MiCA licensing pipeline: Austria, Malta, Eire, and Lithuania have processed significant volumes. This subsidiary is the licensed CASP. It employs native administration. It maintains native banking relationships. Its administration physique meets the Article 68 suitability necessities. Its paid-in capital satisfies the Article 67 thresholds: at minimal EUR 125,000 for entities offering custody or trade providers, or EUR 150,000 if working a buying and selling platform. The place of efficient administration is genuinely within the EU, and may face up to regulatory scrutiny, as a result of the EU entity’s administration really runs the EU operations.
The connection between the offshore father or mother and the EU CASP is ruled by the outsourcing framework underneath Article 73. The EU CASP can outsource operational features to the father or mother or to group associates, however it should retain the experience to guage the standard of these providers and supervise them successfully. It should have direct entry to the related info of outsourced providers. Duty can’t be delegated. The EU CASP stays totally accountable to its NCA for all the pieces it outsources. If the father or mother supplies expertise infrastructure, the EU entity can’t merely abdicate oversight of it. The outsourcing settlement have to be in writing, should give the CASP the suitable to terminate, and should be certain that the father or mother cooperates with the NCA’s supervisory features.
In follow, this implies the EU entity wants greater than a registered deal with and a nominee director. It wants individuals who genuinely handle the EU operations, who can produce documentation and current to regulators, and who perceive what the father or mother is offering on its behalf. The structural separation between father or mother and subsidiary is actual, however the EU entity should have the interior functionality to be held accountable for the group relationship.
Token issuers in the identical group have a 3rd structural choice alongside the 2 already described. The place the mission just isn’t offering CASP providers itself, the offshore token entity can file its personal white paper with an EU competent authority as described above. Alternatively, if the group’s EU CASP operates a buying and selling platform, that entity can tackle the white paper obligation by written settlement underneath Article 5(3), successfully serving because the regulatory interface for the offshore token entity with out the token entity needing any EU presence in any respect.
What the Structure Can’t Do
Three issues stay exterior the attain of any offshore-parent construction, and founders who miss them expose themselves to critical regulatory threat.
The EU entity can’t be a shell. That is the boundary that a number of early MiCA candidates found the onerous approach. A nominee director association, the place selections are successfully constituted of the offshore father or mother and the EU director indicators off on directions from overseas, fails Article 59(2) and the real substance take a look at that regulators apply to Article 68. Some NCAs now conduct dwell interviews with administration physique members as a typical a part of the fit-and-proper evaluation. They ask probing questions on governance, threat administration, and operational authority. A director who can’t converse credibly in regards to the EU entity’s precise operations is a director who is not going to move the evaluation.
The offshore father or mother can’t solicit EU shoppers. Article 61 supplies a carve-out for providers supplied to EU shoppers at their very own unique initiative. ESMA’s pointers on reverse solicitation, printed underneath the mandate of Article 61(3), outline the outer boundary of this exemption in slender phrases. A agency that maintains a web site in Hungarian or Czech or Lithuanian, runs affiliate applications producing EU signups, or participates in EU-facing advertising by any channel, no matter whether or not that exercise comes from the offshore father or mother or an entity appearing on its behalf, just isn’t benefiting from the reverse solicitation exemption. The offshore father or mother of a licensed EU CASP can’t conduct parallel solicitation of EU customers and declare its EU subsidiary handles the regulated portion. Regulators will take a look at the industrial actuality of how shoppers are acquired, not the interior organizational chart.
ARTs and EMTs require EU issuers, full cease. Any mission planning to challenge a stablecoin or asset-referenced token ought to deal with Articles 16 and 48 as the start line for his or her construction, not the CASP regime. The offshore flexibility obtainable for utility tokens and related belongings doesn’t apply right here, and making an attempt to use it by a proxy construction is not going to survive regulatory evaluation.
What We Decoded
For CASP operators: The offshore holding can keep offshore. The query just isn’t whether or not to relocate the father or mother, however whether or not the EU subsidiary has real substance: administration that really runs the EU operations, capital that meets the Article 67 thresholds, governance that satisfies Article 68, and an outsourcing framework with the father or mother that doesn’t hole out the EU entity’s accountability. Jurisdiction choice for the EU subsidiary issues: Austria, Malta, Eire, and Lithuania every supply functioning licensing pipelines and totally different regulatory cultures that go well with totally different enterprise fashions.
For token issuers: In case you are not offering CASP providers, you don’t want an EU entity to file a white paper and supply your token to European buyers. A BVI or Cayman firm can notify the Central Financial institution of Eire or the MFSA and proceed. In case your token is already listed on a licensed EU trade, that trade could also be keen to tackle the white paper obligation by written settlement, by which case your regulatory burden for EU market entry is decreased additional. The sensible selection of submitting jurisdiction nonetheless issues. Eire has processed the broadest vary of token classes, whereas Malta has deeper infrastructure for crypto-specific compliance work.
For hybrid constructions: Teams that each challenge tokens and supply CASP providers have to map every exercise to its regulatory regime individually. The token issuer entity and the CASP entity could also be totally different authorized individuals inside the similar group. Their obligations don’t cross over just because they share an final father or mother. This structural separation is usually a characteristic, not a complication: the offshore token treasury operates underneath the token issuer regime, the EU CASP operates underneath Title V, and the offshore father or mother holds the group collectively with out itself needing authorization.
The founders who relocated in 2025 weren’t essentially fallacious to take action. A consolidated EU presence has operational benefits, and a genuinely EU-anchored group is easier to handle from a regulatory standpoint. However they acted on an assumption about what MiCA required that the regulation itself doesn’t totally assist. The register makes this seen. The structure of MiCA was at all times able to accommodating offshore father or mother constructions, supplied the entity that really serves EU shoppers is genuinely current, genuinely managed, and genuinely accountable contained in the Union.
This text is predicated on a research carried out by LegalBison in Might 2026. The content material is for informational functions solely and doesn’t represent authorized recommendation.


