
US President Donald Trump signed an govt order directing a overview of laws and obstacles that will restrict fintech innovation and limit entry to banking partnerships and cost techniques. The transfer has revived debate round whether or not fintech firms ought to have the ability to entry the Federal Reserve’s cost infrastructure extra immediately.
Ought to non-bank fintech corporations proceed to rely on conventional banks to succeed in cost rails, or ought to fintechs entry central financial institution cost rails throughout the US?
TL;DR
US policymakers are reviewing fintech entry to Federal Reserve cost techniques after an govt order from Donald Trump known as for decreasing obstacles to monetary innovation and updating outdated laws.
On the middle of the talk is whether or not fintech corporations ought to proceed counting on banks for entry to cost rails or be allowed direct entry into core U.S. cost infrastructure.
The dialogue highlights a broader stress between innovation and regulation, as fintech corporations push for simpler entry whereas regulators give attention to stability, oversight, and systemic threat management.
Why Is Entry to Fed Fee Rails So Vital for Fintechs?
The Fed cost system rails are the core infrastructure that powers how cash strikes throughout the US monetary system. They deal with important monetary actions similar to wire transfers, direct deposits, invoice funds, and real-time settlements between banks and controlled monetary establishments. Due to this function, they sit on the middle of how transactions circulate by way of the economic system.
Proper now, most fintech firms shouldn’t have direct entry to those techniques. As a substitute, they function by way of partnerships with conventional banks that already maintain entry. This implies fintech corporations rely on banking companions to course of funds, maintain buyer funds, and settle transactions inside the broader monetary system.
This construction creates each operational and strategic constraints. Funds usually transfer by way of extra layers of processing, which may introduce delays, enhance compliance necessities, and restrict how independently fintech firms can construct and scale merchandise. It additionally signifies that a lot of the innovation in digital funds will depend on the infrastructure and permissions of established banks slightly than fintech platforms themselves.
These limitations have additionally formed how competitors works within the funds trade. As a result of banks management direct entry to Fed cost rails, they continue to be central gatekeepers within the system. This makes it more durable for newer monetary firms to compete on equal phrases, even once they supply quicker or extra user-friendly digital providers.
Because of this, entry to Fed cost infrastructure has turn out to be a key difficulty for fintech corporations. Larger entry is seen as a approach to scale back reliance on middleman banks, simplify cost operations, and develop the flexibility to construct and scale monetary merchandise immediately on prime of core cost techniques.
On the similar time, the Federal Reserve’s cost techniques are thought-about essential nationwide monetary infrastructure, which is why entry has historically been tightly managed to keep up stability, safety, and reliability throughout the whole monetary ecosystem.
Why the US Authorities Is Reviewing Fintech Entry Guidelines
The controversy over entry has intensified as policymakers reassess how monetary innovation must be regulated in a digital economic system. The Trump administration has argued that regulatory frameworks must evolve alongside technological change within the monetary sector.
Within the govt order, Trump acknowledged that the US stays a world chief in monetary innovation, pushed by the fast development of economic expertise and fintech corporations. Trump wrote:
“To foster this monetary innovation, the Federal Authorities should replace laws to permit integration of digital belongings and revolutionary expertise into conventional monetary providers and cost techniques. The Federal Authorities should additionally take away overly burdensome and fragmented laws and supervisory practices that kind obstacles to entry and primarily profit incumbent monetary providers corporations.”
Regulatory Considerations: The Dangers of Fintech Entry To the Fed Fee Infrastructure
Regardless of the growing requires accessibility, the regulators should not but prepared to allow non-bank fintechs the correct of direct entry into the cost system of the Federal Reserve.
The first concern relating to such an enlargement is the potential to extend systemic dangers. The Fed cost rails deal with a really great amount of high-value transactions every day within the monetary providers trade. Growing the bottom of members who’ve direct entry to those rails can result in the potential for failures or different issues, which may have a broader influence throughout the whole monetary system.
The opposite main downside that wants consideration is oversight. There’s already a well-structured framework accessible for overseeing conventional banks. Such guidelines are meant particularly for these organizations that make settlements by themselves. Most fintech firms, together with these that aren’t banks, are regulated in a different way, and there are issues about whether or not these laws can be enough to grant entry to extra members.
One other difficulty price bearing in mind is that of operational resilience. Fee techniques run by the Federal Reserve are anticipated to work faultlessly and with out interruptions. There’s a threat that permitting extra organizations entry would possibly complicate issues and hinder efforts to keep up a correct stage of safety, safety in opposition to fraud, and integrity.
Because of this, entry to the Federal Reserve’s cost system stays extremely restricted. Any steps to open up entry ought to entail establishing extra requirements of compliance and supervision.
Impression On Banks and the Conventional Monetary System
Increasing fintech entry to the Federal Reserve’s cost techniques might reshape how banks function, compete, and preserve their function within the monetary ecosystem.
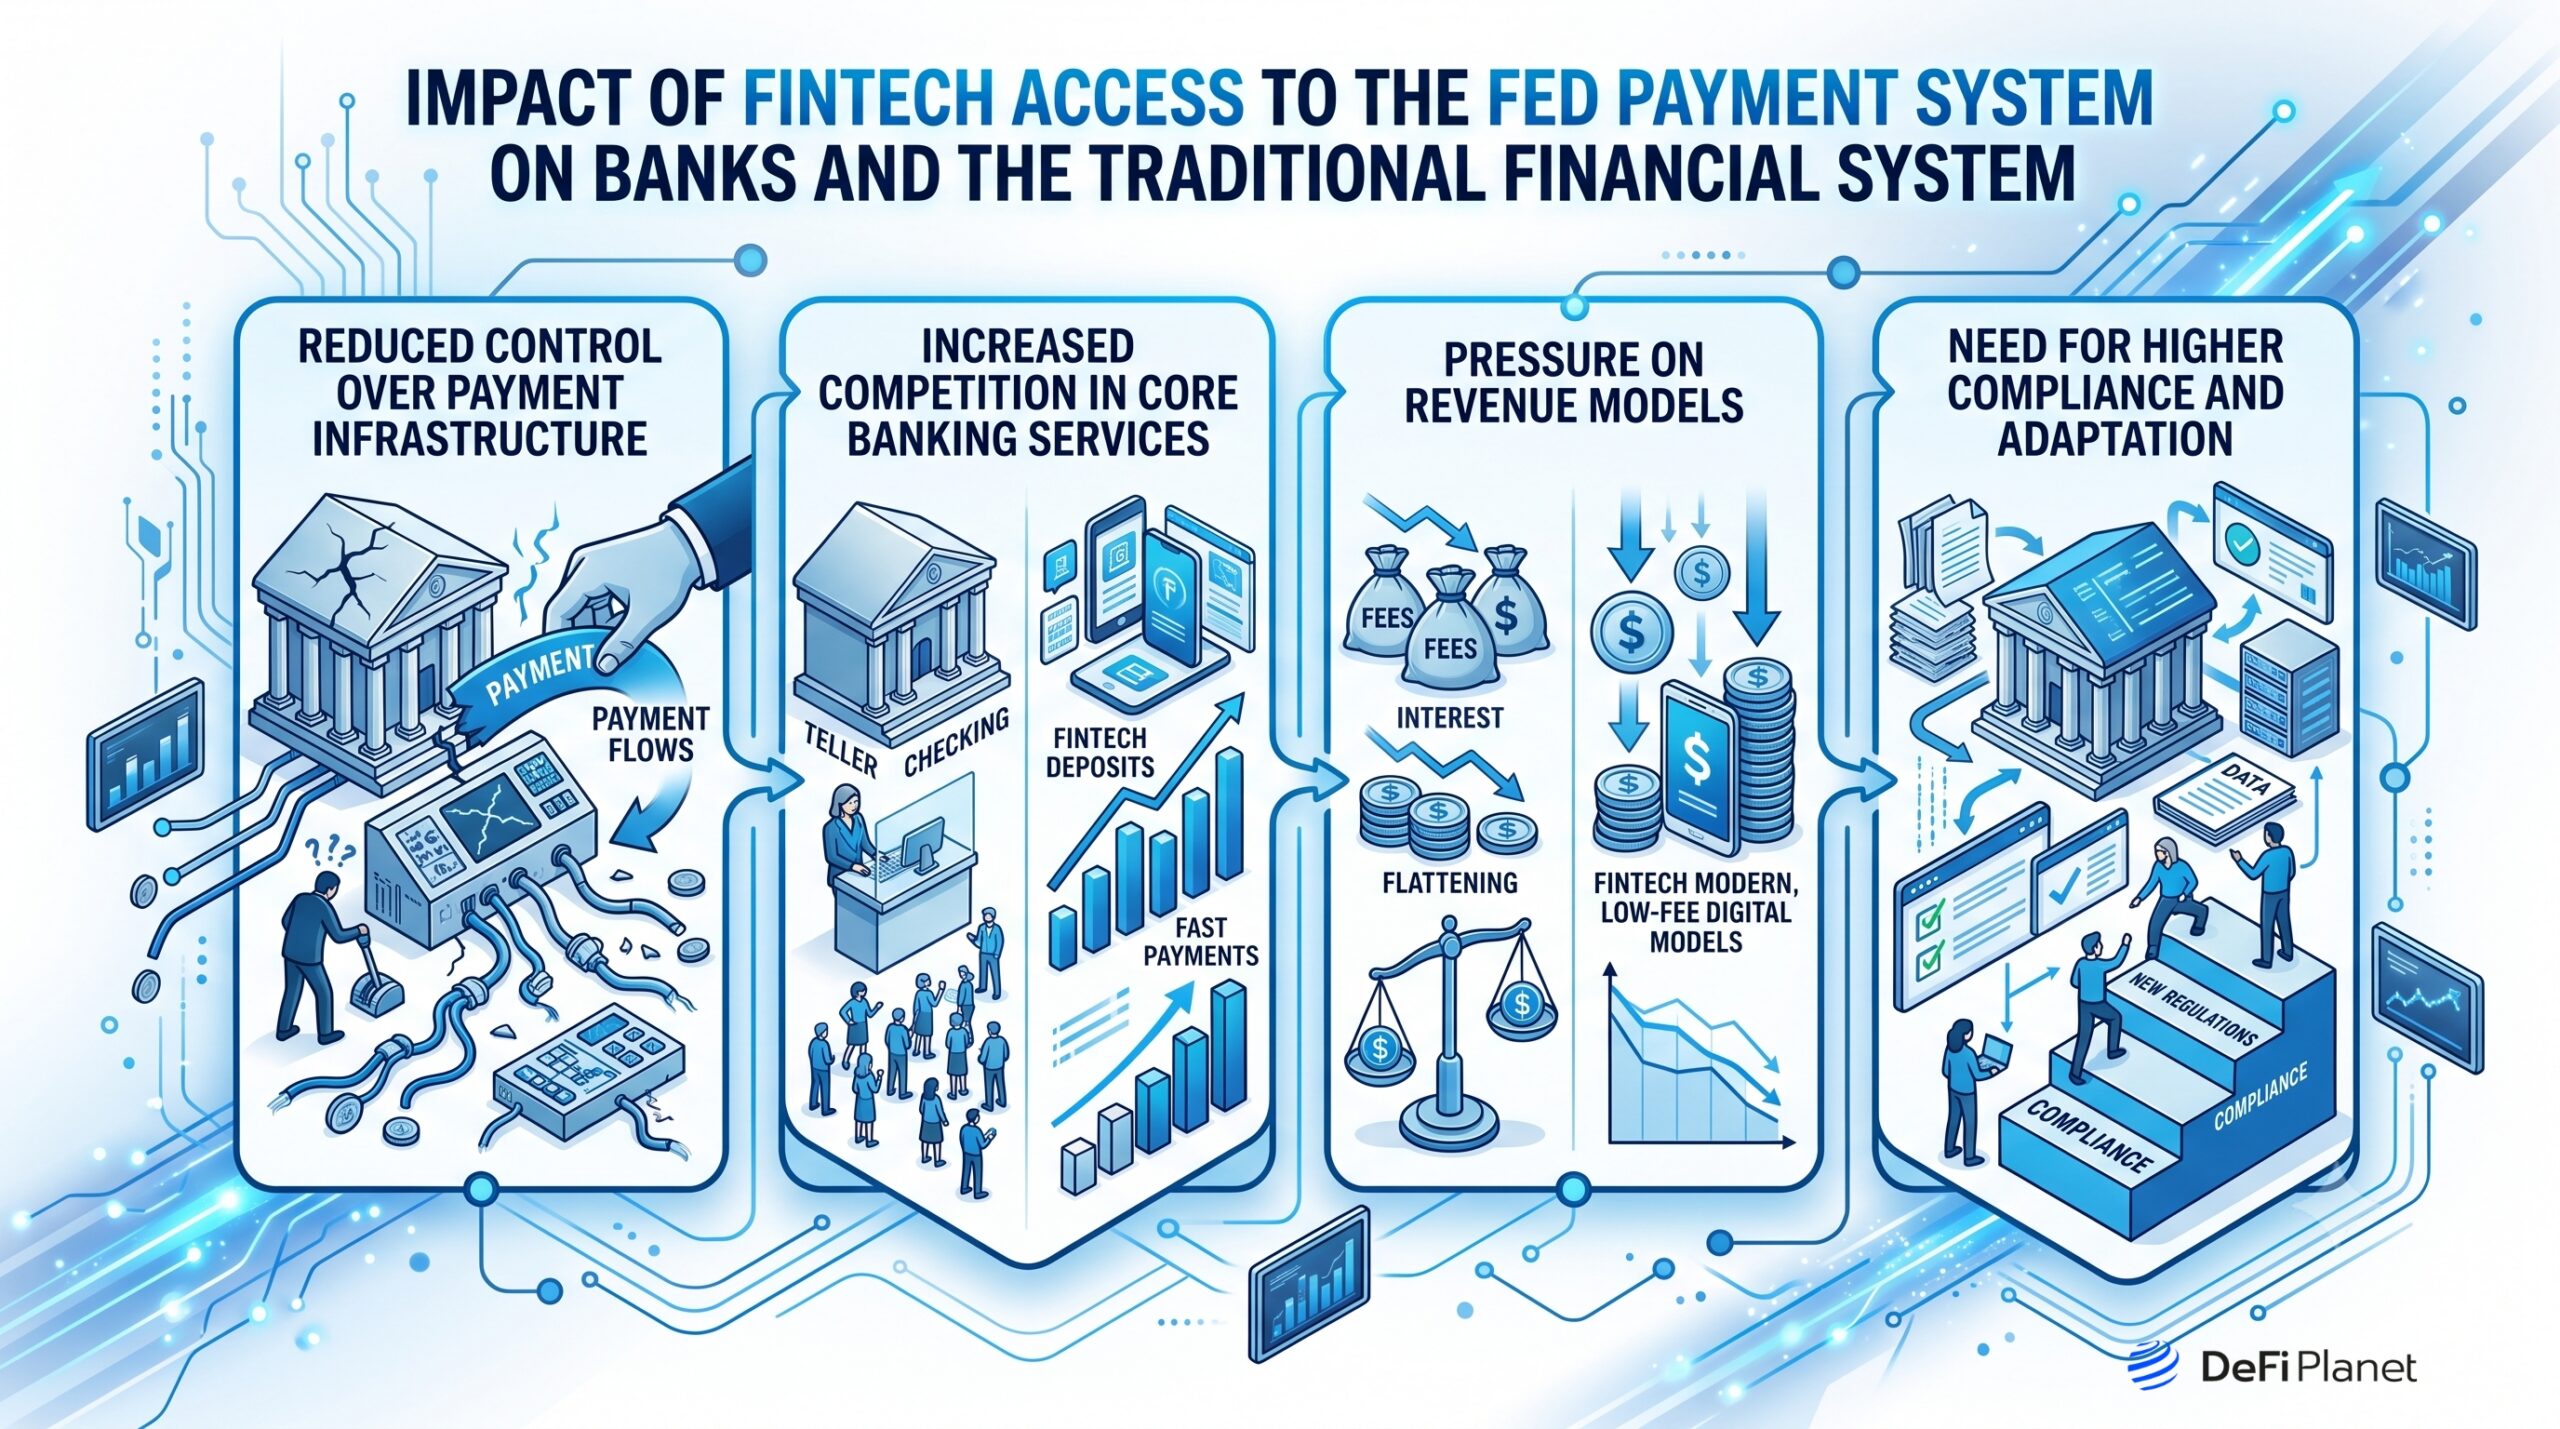
Diminished management over cost infrastructure
Banks at the moment act as intermediaries for accessing the Federal Reserve’s cost techniques. Elevated entry by fintechs can restrict banks’ means to keep up management over the infrastructure. It is going to have an effect on their means to regulate one of the vital features of the monetary sector.
Elevated competitors in core banking providers
Expanded entry by fintechs can enhance competitors in offering providers historically provided solely by banks. These embrace transactions and transfers. The stress will likely be associated to cost and repair supply.
Strain on income fashions
The banks obtain a good portion of their income from cost processing and transaction providers. Moreover, many banks derive revenue from appearing as intermediaries in fintech partnerships. Fintechs will discover methods to keep away from intermediaries, resulting in losses in income for the financial institution.
Want for larger compliance and adaptation
The enlargement of entry would require that banks adapt to working with fintechs. That is as a result of altering nature of the cost surroundings.
Potential Outcomes of Expanded Entry to the Fed Fee System
If fintech corporations acquire broader entry to Federal Reserve cost infrastructure, it might reshape competitors, innovation, and the construction of the US monetary system.
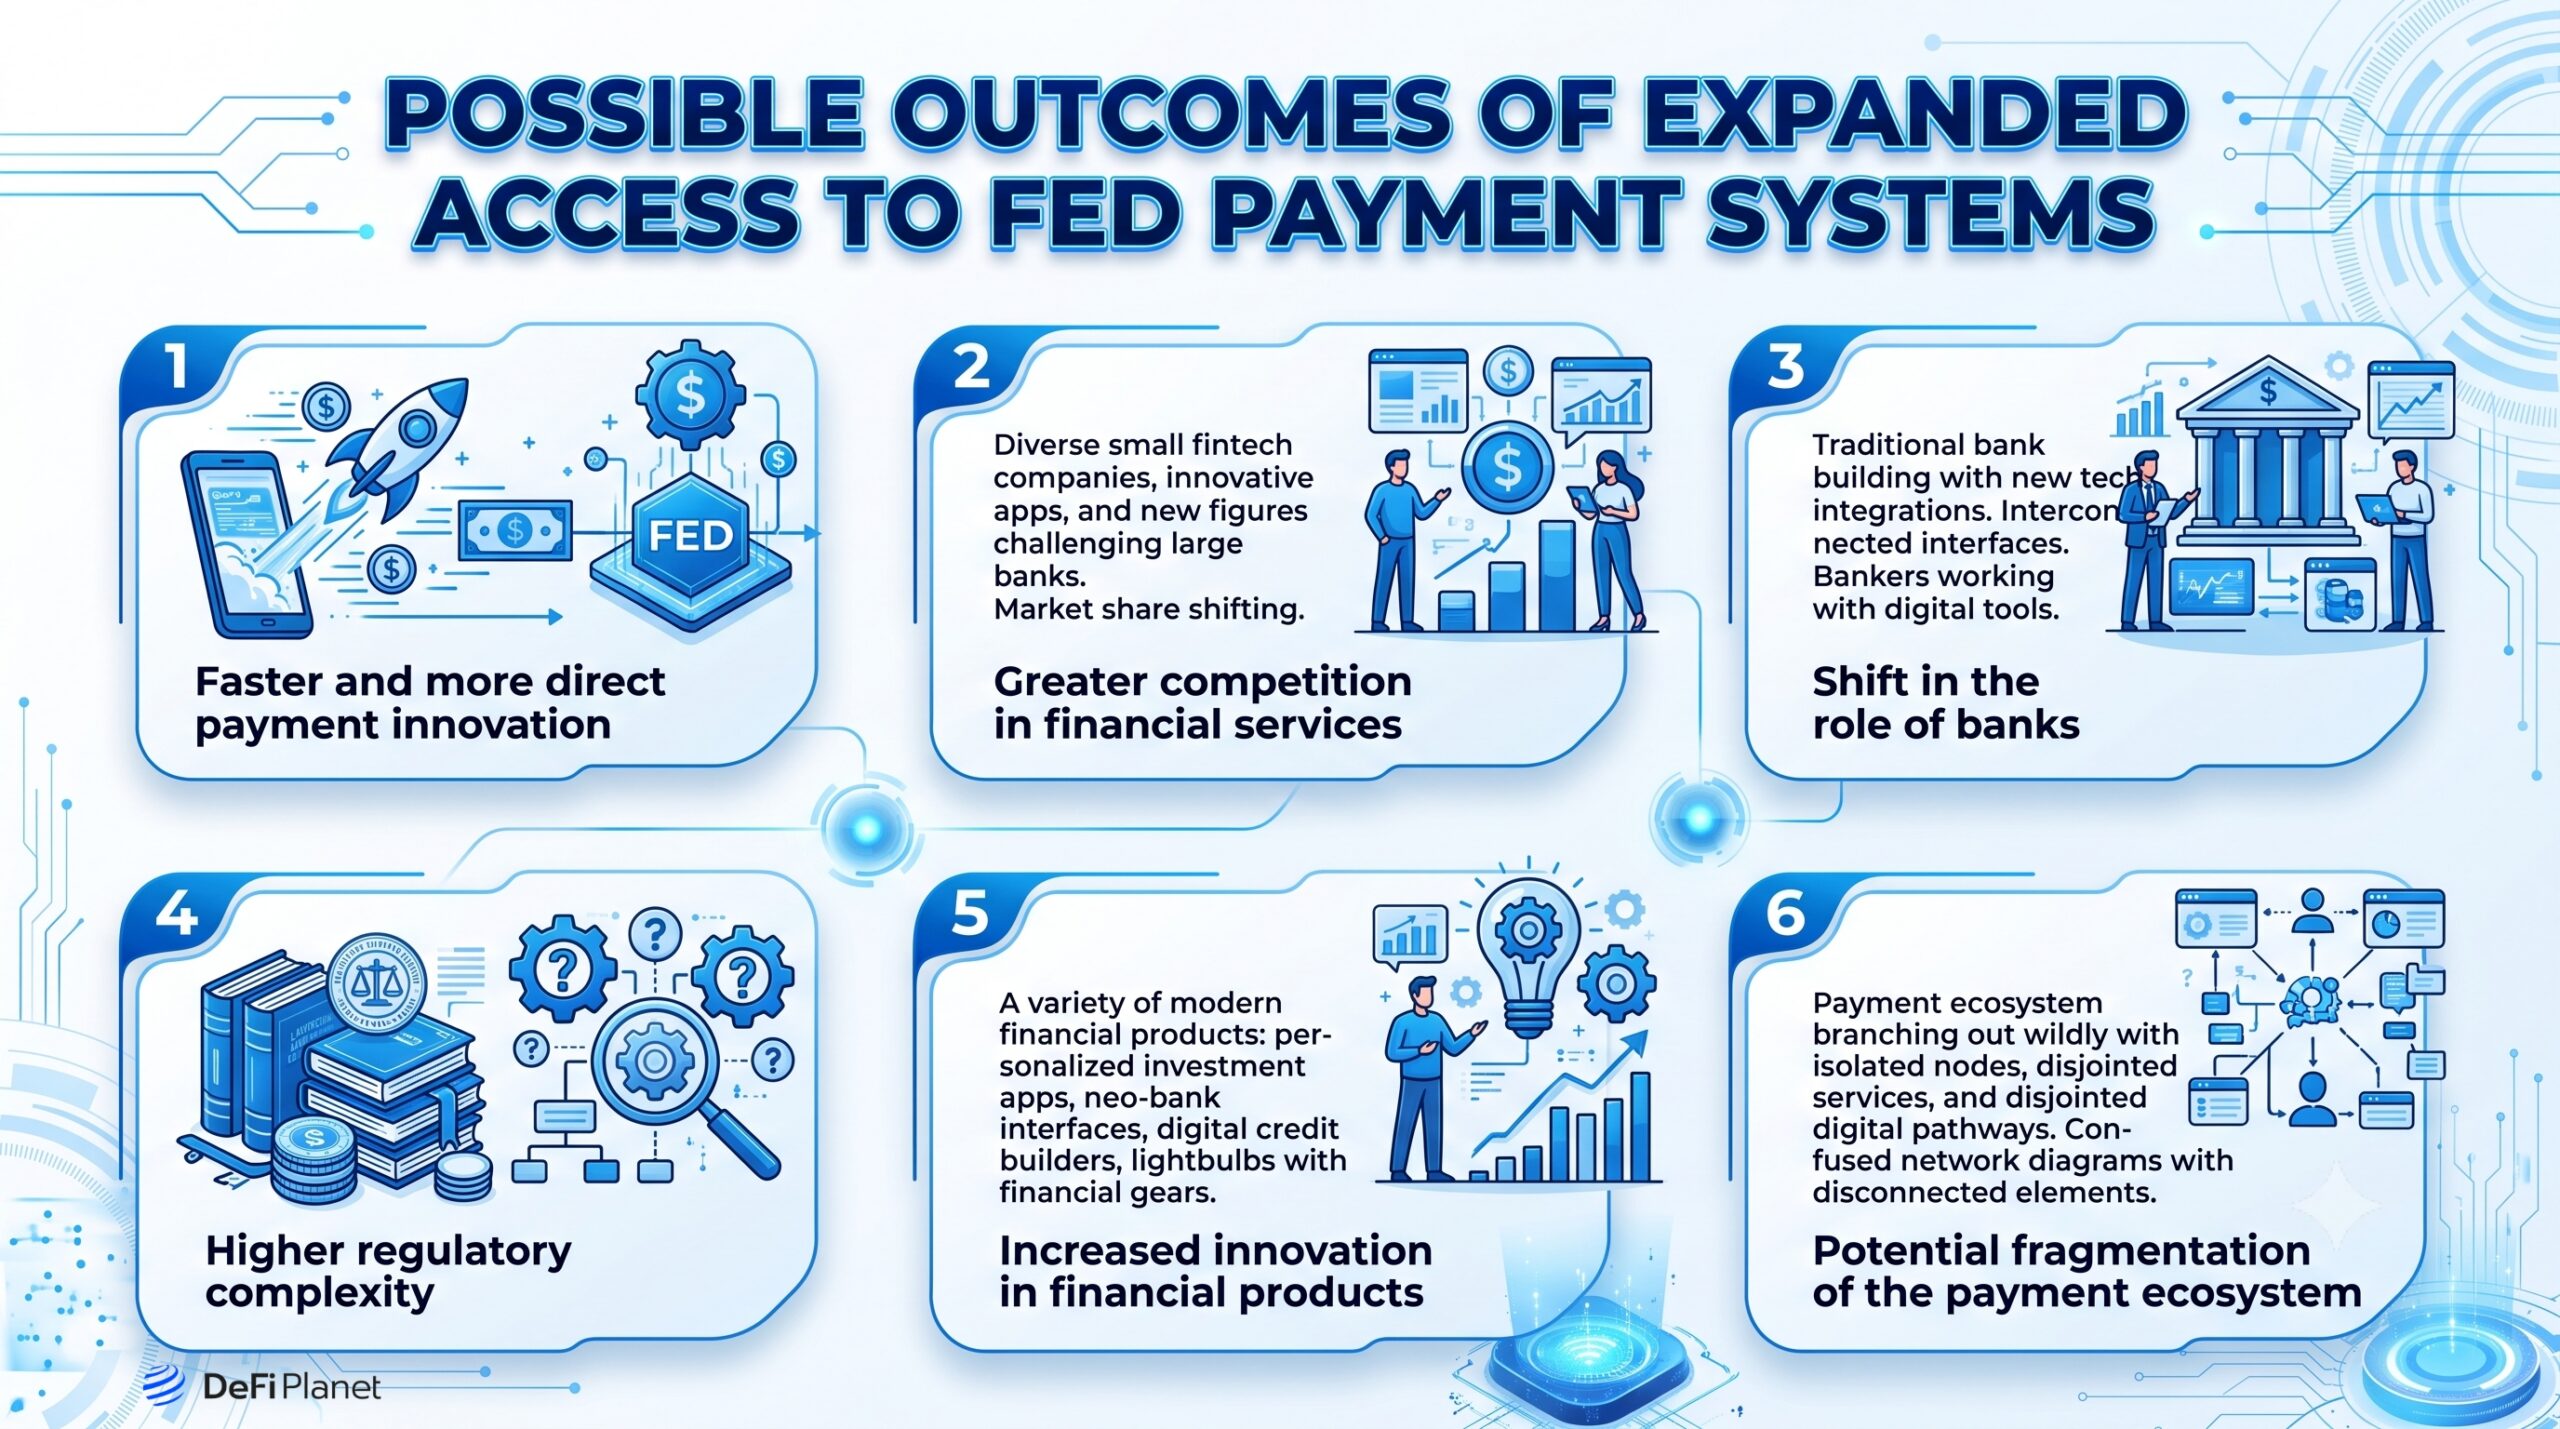
Sooner and extra direct cost innovation
Fintechs would have the ability to develop and introduce their cost options independently of the partnering banks. In flip, this may permit accelerating the introduction of improvements similar to real-time funds, automation of assorted monetary processes, and embedded finance. Ultimately, this may speed up the tempo of implementing novel options for patrons.
Larger competitors in monetary providers
By going on to customers and retailers, many Fintechs would have the ability to compete within the cost house beforehand unique to established banks. Furthermore, that is prone to result in value competitors, improved service high quality, and extra shopper decisions for funds and cash transfers. It could additionally diminish the aggressive edge banks maintain in cost ecosystems.
Shift within the function of banks
The function of conventional banks as main suppliers and gatekeepers of cost infrastructure would possibly progressively shift in the direction of compliance, liquidity, and threat administration inside Fintechs. This might imply a diminished function for banks as suppliers of economic providers and an elevated emphasis on supporting infrastructure.
Larger regulatory complexity
The growing variety of entities that immediately hyperlink to the Fed infrastructure would necessitate the event of higher oversight mechanisms to make sure its stability. This might contain nearer scrutiny, enhanced compliance measures, and much more refined instruments to fight fraud and operational threat.
Elevated innovation in monetary merchandise
With wider entry to such a cost system, revolutionary monetary providers may very well be created which can be at the moment infeasible inside the framework of the bank-based monetary sector. Fintech firms would possibly discover the chance to provide you with cost providers which can be personalized to clients’ wants.
Potential fragmentation of the cost ecosystem
With the emergence of quite a few members immediately linked to the cost system, it’s seemingly that points stemming from the complexity and fragmentation of this surroundings will come up. Numerous approaches to coping with totally different features of the cost course of might complicate its operation.
International Competitiveness Angle (EU, Chinese language Fintech techniques)
The controversy over fintech entry to the Federal Reserve’s cost techniques shouldn’t be solely a home coverage difficulty. It additionally has to do with how the US compares with different main economies which can be already experimenting with extra open or state-driven cost infrastructures.
Europe’s extra open banking mannequin
Laws such because the Fee Companies Directive 2 (PSD2) within the European Union require banks to share their clients’ account knowledge with any third-party supplier licensed to take action. This follow is named “open banking” and makes it potential for fintechs to create revolutionary providers constructed on prime of typical banking by way of standardized APIs.
Consequently, funds, knowledge change, and monetary providers turn out to be way more interoperable amongst totally different fintech corporations. In america, this instance places stress on the case for introducing a extra versatile entry coverage to speed up fintech growth.
China’s platform-driven funds ecosystem
A completely distinct instance is China, the place the fintech purposes Alipay and WeChat Pay present cost providers at scale. The platforms work inside an ecosystem that integrates funds, lending, and different monetary providers inside a single ecosystem.
This instance is slightly efficient but in addition demonstrates a extra centralized construction with excessive regulatory scrutiny and the presence of only some dominant corporations.
The US is regulated however fragmented
The US occupies an middleman place between these two techniques. On the one hand, it has a particularly sturdy and dependable cost infrastructure. On the similar time, accessibility is decrease because it requires a partnership with banks.
Fintechs might have issue getting into the core cost system by way of a financial institution, which could take extra time than in additional open international locations abroad.
Strain as a consequence of strategic competitiveness
As cost techniques proceed to develop, entry to cost infrastructure might turn out to be a part of strategic competitiveness in monetary innovation. If US fintech companies face extra restrictions than these in Europe or Asia, the migration of innovation, funding, and expert personnel to different areas might happen.
On the similar time, loosening entry within the US have to be balanced in opposition to the necessity to preserve the safety and stability of one of many world’s most crucial monetary networks.
Are We Headed In direction of a “Extra Open” Infrastructure System?
The US Fed cost system seems to be to be shifting towards gradual openness, however in all probability not towards a totally open system anytime quickly. Strain from fintech firms and policy-related points might result in better flexibility and availability over time, particularly for non-bank corporations working below sure laws.
However the present structure of the cost techniques operated by the Fed is not going to bear main modifications as a result of connection between the cost system and monetary stability. The possible situation is a gradual extension and elevated fintech entry, however solely below tight regulatory management and never based mostly on an open-architecture method.
Disclaimer: This text is meant solely for informational functions and shouldn’t be thought-about buying and selling or funding recommendation. Nothing herein must be construed as monetary, authorized, or tax recommendation. Buying and selling or investing in cryptocurrencies carries a substantial threat of economic loss. All the time conduct due diligence.
Loved this? Bookmark DeFi Planet, discover associated subjects, and observe us on Twitter, LinkedIn, Fb, Instagram, Threads, and CoinMarketCap Group for seamless entry to high-quality trade insights.
Take management of your crypto portfolio with DEFI PLANET PRO, DeFi Planet’s suite of analytics instruments.


