
Crypto scams begin on-line with a pretend financial institution alert, a cloned voice, a romance message, or a tech-support pop-up. Then, the final instruction is normally way more bodily: withdraw money, discover a crypto kiosk, scan a QR code, and hold the scammer on the telephone till the cash is gone.
Nonetheless, that final step is popping Bitcoin ATMs and different crypto kiosks right into a stress level in America’s fraud downside.
The FBI’s Web Crime Report mentioned that Individuals submitted 181,565 complaints involving cryptocurrency, with reported losses exceeding $11 billion. A later IC3 cryptocurrency-kiosk PSA put a smaller however extra concrete mechanism underneath the highlight: 13,460 complaints involving crypto kiosks in 2025 and $388,981,267 in adjusted losses.
On-line fraud creates the assumption that cash should transfer instantly. The kiosk creates the cost rail a frightened sufferer can function in a comfort retailer, gasoline station, or grocery store whereas a legal provides directions in actual time.
As soon as money turns into crypto and strikes right into a pockets managed by the scammer, the window to interrupt the switch normally closes.
The kiosk turns into the purpose the place households, banks, operators, and state regulators nonetheless have an opportunity to step in.
The $11B downside has a street-level endpoint
The FBI’s 2025 numbers present the size of the broader fraud pipeline. IC3 obtained 1,008,597 whole complaints in 2025, and the FBI mentioned cyber-enabled crimes defrauded Individuals of practically $21 billion.
Cryptocurrency complaints had been the highest-loss descriptor within the report, whereas AI-related complaints added practically $893 million in losses.
The rise of generative AI has helped scammers get victims to succeed in the kiosk already primed to behave. The FBI mentioned scammers now use pretend social profiles, voice clones, identification paperwork, and plausible movies depicting public figures or family members.
These instruments don’t want to the touch a blockchain to push somebody towards the machine. They create the stress, authority, or panic that sends a sufferer out the door with money.
The kiosk PSA reveals what occurs subsequent. IC3 mentioned cryptocurrency kiosks are ATM-like units or terminals that permit customers to alternate money for cryptocurrency.
It mentioned criminals could direct victims to ship funds by them, and that complaints involving the units rose 23% in 2025 whereas losses rose 58% from 2024.
Official measure2025 figureReader consequenceCryptocurrency-related IC3 complaints181,565 complaints and greater than $11 billion in reported lossesShows the nationwide scale of crypto-linked fraudCryptocurrency-kiosk complaints13,460 complaints and $388,981,267 in adjusted lossesShows the bodily last-mile channelKiosk pattern from 2024Complaints up 23%; losses up 58percentShows the issue is acceleratingPeople over 50 in kiosk complaintsMore than half of complaints; over $302 million in lossesShows the place client hurt is concentrated
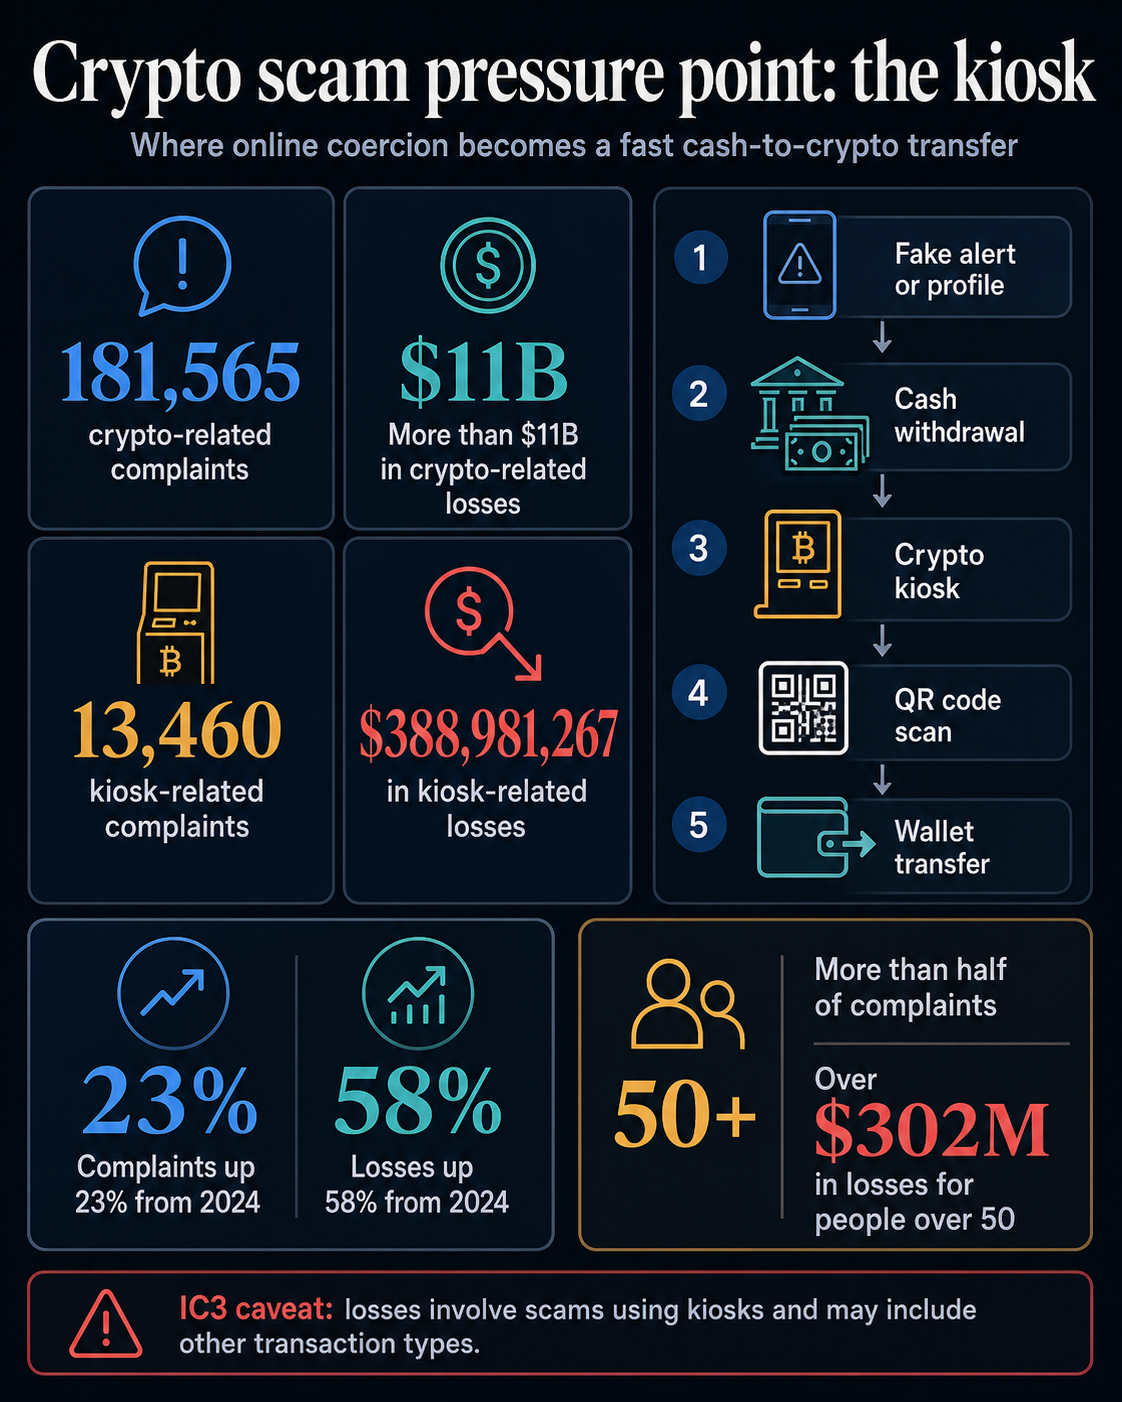
IC3 additionally warned that its kiosk information covers scams involving cryptocurrency kiosks and should embrace different transaction varieties. Nonetheless, kiosks have gotten a recurring a part of the cost path in scams which have already moved from on-line persuasion to real-world money motion.
The scammer doesn’t want to the touch the machine
The mechanics are easy sufficient to make the gadget harmful. IC3 mentioned typical kiosk complaints contain criminals offering detailed directions on withdraw money from a financial institution, find a kiosk, and deposit and ship funds utilizing it.
Its warning indicators embrace individuals holding QR-code documentation they can’t clarify, making giant first-time money withdrawals, talking on the telephone whereas showing confused at a financial institution or kiosk, or lingering across the machine.
California’s Division of Monetary Safety and Innovation describes the identical sample in its client warning.
A scammer contacts the sufferer, creates a way of urgency, directs them to a crypto ATM, stays on the telephone through the transaction, and should ship a QR code that routes the bought belongings on to the scammer’s pockets. The DFPI additionally highlights the hazard in that the transactions are fast and rapid and can’t be reversed.
FinCEN’s 2025 discover on convertible digital foreign money kiosks explains why that workflow is enticing to criminals.
A CVC kiosk buy seems like a normal ATM transaction to a person, however the pockets handle that receives the crypto could belong to another person and is usually embedded in a QR code. FinCEN mentioned scammers usually hold victims in fixed telephone or on-line contact till cost is accomplished.
It additionally mentioned scammers could instruct victims to separate deposits throughout quantities or machines to keep away from safeguards.
The economics add one other clue. Kiosk charges can vary from 7% to twenty%, however scammers tolerate the fee as a result of crypto can transfer shortly upon receipt, and restoration might be tough.
For a respectable purchaser, a excessive payment is a foul deal. For a legal making an attempt to transform a sufferer’s money into fast-moving crypto, it may be a part of the enterprise mannequin.
That’s the reason the gadget sits on the heart of the query of duty. The sufferer would be the one urgent buttons, however the transaction usually contains seen warning indicators earlier than the funds transfer.
The warning indicators embrace a big money withdrawal, a nervous buyer, a telephone name that doesn’t finish, a QR code equipped by another person, repeated deposits, or a vacation spot pockets the client can not clarify.
Operators and banks are actually a part of the management floor
FinCEN has urged monetary establishments to determine and report suspicious exercise involving CVC kiosks. It additionally warned that the danger of illicit exercise is larger when operators fail to fulfill Financial institution Secrecy Act obligations.
That places stress on each side of the kiosk enterprise. Operators have to watch the client and the transaction. Banks and credit score unions that serve the operators have to grasp whether or not a kiosk enterprise has actual anti-fraud and anti-money-laundering controls.
FinCEN mentioned non-compliant operators are particularly susceptible to abuse by scammers and different criminals. It mentioned some scammers direct victims to particular kiosks, typically throughout state strains, prone to keep away from stronger controls.
California’s DFPI says the state’s Digital Monetary Property Regulation prohibits kiosk operators from accepting greater than $1,000 per particular person per day.
CryptoSlate’s current protection of Florida’s new crypto ATM legislation described one other mannequin with warnings, receipts, transaction caps, registration, and conditional refunds that may shift a few of the rip-off danger onto operators.
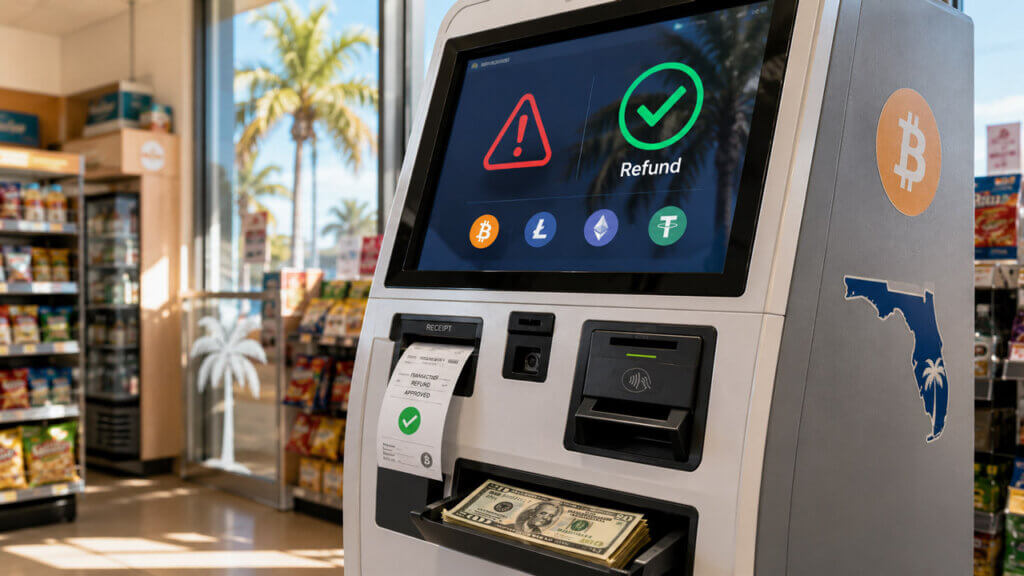
These examples type a state-level menu moderately than a nationwide customary: decrease day by day limits, clearer warnings, stay buyer assist, refund rights, operator registration, financial institution monitoring, and direct calls from operators when a transaction seems to be fraudulent.
Every strategy goals on the identical small window of time between money withdrawal and blockchain settlement.
The FTC’s earlier Bitcoin ATM information highlight helps clarify the urgency. It mentioned reported fraud losses involving Bitcoin ATMs elevated practically tenfold from 2020 to 2023 and topped $65 million within the first half of 2024, with a median reported lack of $10,000 in that six-month interval.
It additionally mentioned older adults had been hit disproportionately.
IC3’s 2025 kiosk figures framed that concern inside a bigger official context. Greater than half of the kiosk complaints concerned individuals over 50, leading to losses of over $302 million.
That could be a household-finance danger, usually arriving by the identical locations the place individuals already purchase gasoline, groceries, and convenience-store items.
The subsequent check is whether or not these on a regular basis touchpoints can change into interruption factors. A financial institution teller who questions a rushed money withdrawal, an operator who blocks a suspicious transaction, a state cap that stops a full account drain, or a member of the family who acknowledges the script can all change the result earlier than the cash strikes.
After the transaction, the instruments are weaker. The fraud should still be traceable on-chain, however the funds can transfer by wallets and exchanges sooner than a sufferer can perceive what occurred.
That asymmetry is drawing scrutiny as a result of the kiosk would be the final sensible place to cease the switch.
If operators, banks, and lawmakers can not make that second safer, the official numbers level towards a harsher conclusion. The weakest hyperlink within the crypto rip-off pipeline would be the ATM-like machine that turns worry right into a crypto switch earlier than anybody else can intervene.

