
A number of rising markets, together with Vietnam, India, and Nigeria, are actively exploring new methods to enhance SME entry to credit score by increasing what might be accepted as collateral or by utilizing different credit score programs. One proposal gaining consideration is Vietnam’s plan to permit SMEs to make use of digital property, digital property, and mental property as mortgage collateral.
The transfer displays an effort to enhance financing choices for companies that battle to safe conventional financial institution loans. If adopted, it may permit lenders to simply accept a wider vary of non-traditional property when assessing creditworthiness.
However for SME lending in rising markets: are digital property secure as collateral for loans with out rising danger within the monetary system?
TL;DR
Vietnam is exploring digital property as mortgage collateral to assist SMEs entry financing past conventional property like land and property.
Utilizing digital property may unlock funding alternatives, particularly for digital-first, crypto, and Web3 companies that battle with typical lending necessities.
The transfer additionally introduces dangers, together with value volatility, valuation challenges, custody issues, and the necessity for stronger regulatory safeguards.
Why SMEs in Rising Markets Wrestle with Conventional Collateral Necessities
SMEs in rising markets typically discover it exhausting to get financial institution loans as a result of following causes:
SMEs typically don’t have bank-acceptable collateral like land or property
Many small companies in rising markets function with out proudly owning formal property that banks acknowledge. For instance, a meals vendor or small retail store might have tools, inventory, or a gentle money stream, however these should not normally accepted as robust collateral. As an alternative, banks usually choose land titles or registered property as safety.
Many SMEs run from rented areas or casual places, so even when they’re worthwhile, they nonetheless don’t meet the usual collateral necessities wanted to safe a mortgage.
Weak authorized programs make asset restoration tough for lenders
In some rising markets, recovering property after a mortgage default could be a sluggish and tough course of, typically stretching over months and even years. In Nigeria, as an example, the Asset Administration Company of Nigeria (AMCON) has reported that 1000’s of mortgage restoration instances stay caught within the courts, with authorized technicalities often delaying closing rulings.
Extended enforcement course of makes it more durable for lenders to rapidly reclaim collateral. In consequence, banks turn out to be extra cautious and have a tendency to impose stricter lending necessities to scale back the danger of losses.
Excessive perceived danger results in over-collateralization
As a result of SMEs are seen as extra prone to default, banks typically ask for collateral price greater than the mortgage quantity itself. For instance, a enterprise may want a $10,000 mortgage however be required to supply property price $15,000–$20,000. This degree of demand shuts out many in any other case viable companies.
Casual companies don’t have any credit score information
Many SMEs shouldn’t have formal banking histories or audited monetary statements. A small provider who offers principally in money transactions might don’t have any credit score rating in any respect, even when they’ve been operating for years. With out this information, banks battle to guage how reliably they’ll repay a mortgage.
How Vietnam’s Proposal Modifications What Counts as Mortgage Collateral
Underneath the proposed framework of Vietnam’s Ministry of Finance (MoF), Vietnam would transfer away from the present system the place banks principally require bodily property like land or buildings earlier than giving loans. As an alternative, the definition of “acceptable collateral” could be expanded to incorporate a a lot wider vary of enterprise worth.
In observe, this implies SMEs may use issues like mental property (for instance, patents, software program, or model rights), digital and digital property, enterprise possession rights, and even sure property anticipated to be created sooner or later as safety for loans. So as a substitute of needing a store constructing or farmland, a tech startup may doubtlessly use its software program code or licensing rights as collateral.
The proposal additionally modifications how banks assess lending danger. Slightly than focusing primarily on what bodily property a enterprise owns, lenders could be inspired to look extra at credit score scores, money stream, enterprise plans, and market potential. This shifts a part of the lending resolution from “what are you able to pledge right now” to “how robust is your enterprise and future earnings prone to be”.
Advantages of Utilizing Digital Property as Collateral for SME Financing
Utilizing digital property as collateral may assist SMEs unlock financing in ways in which higher replicate how trendy companies truly create worth.
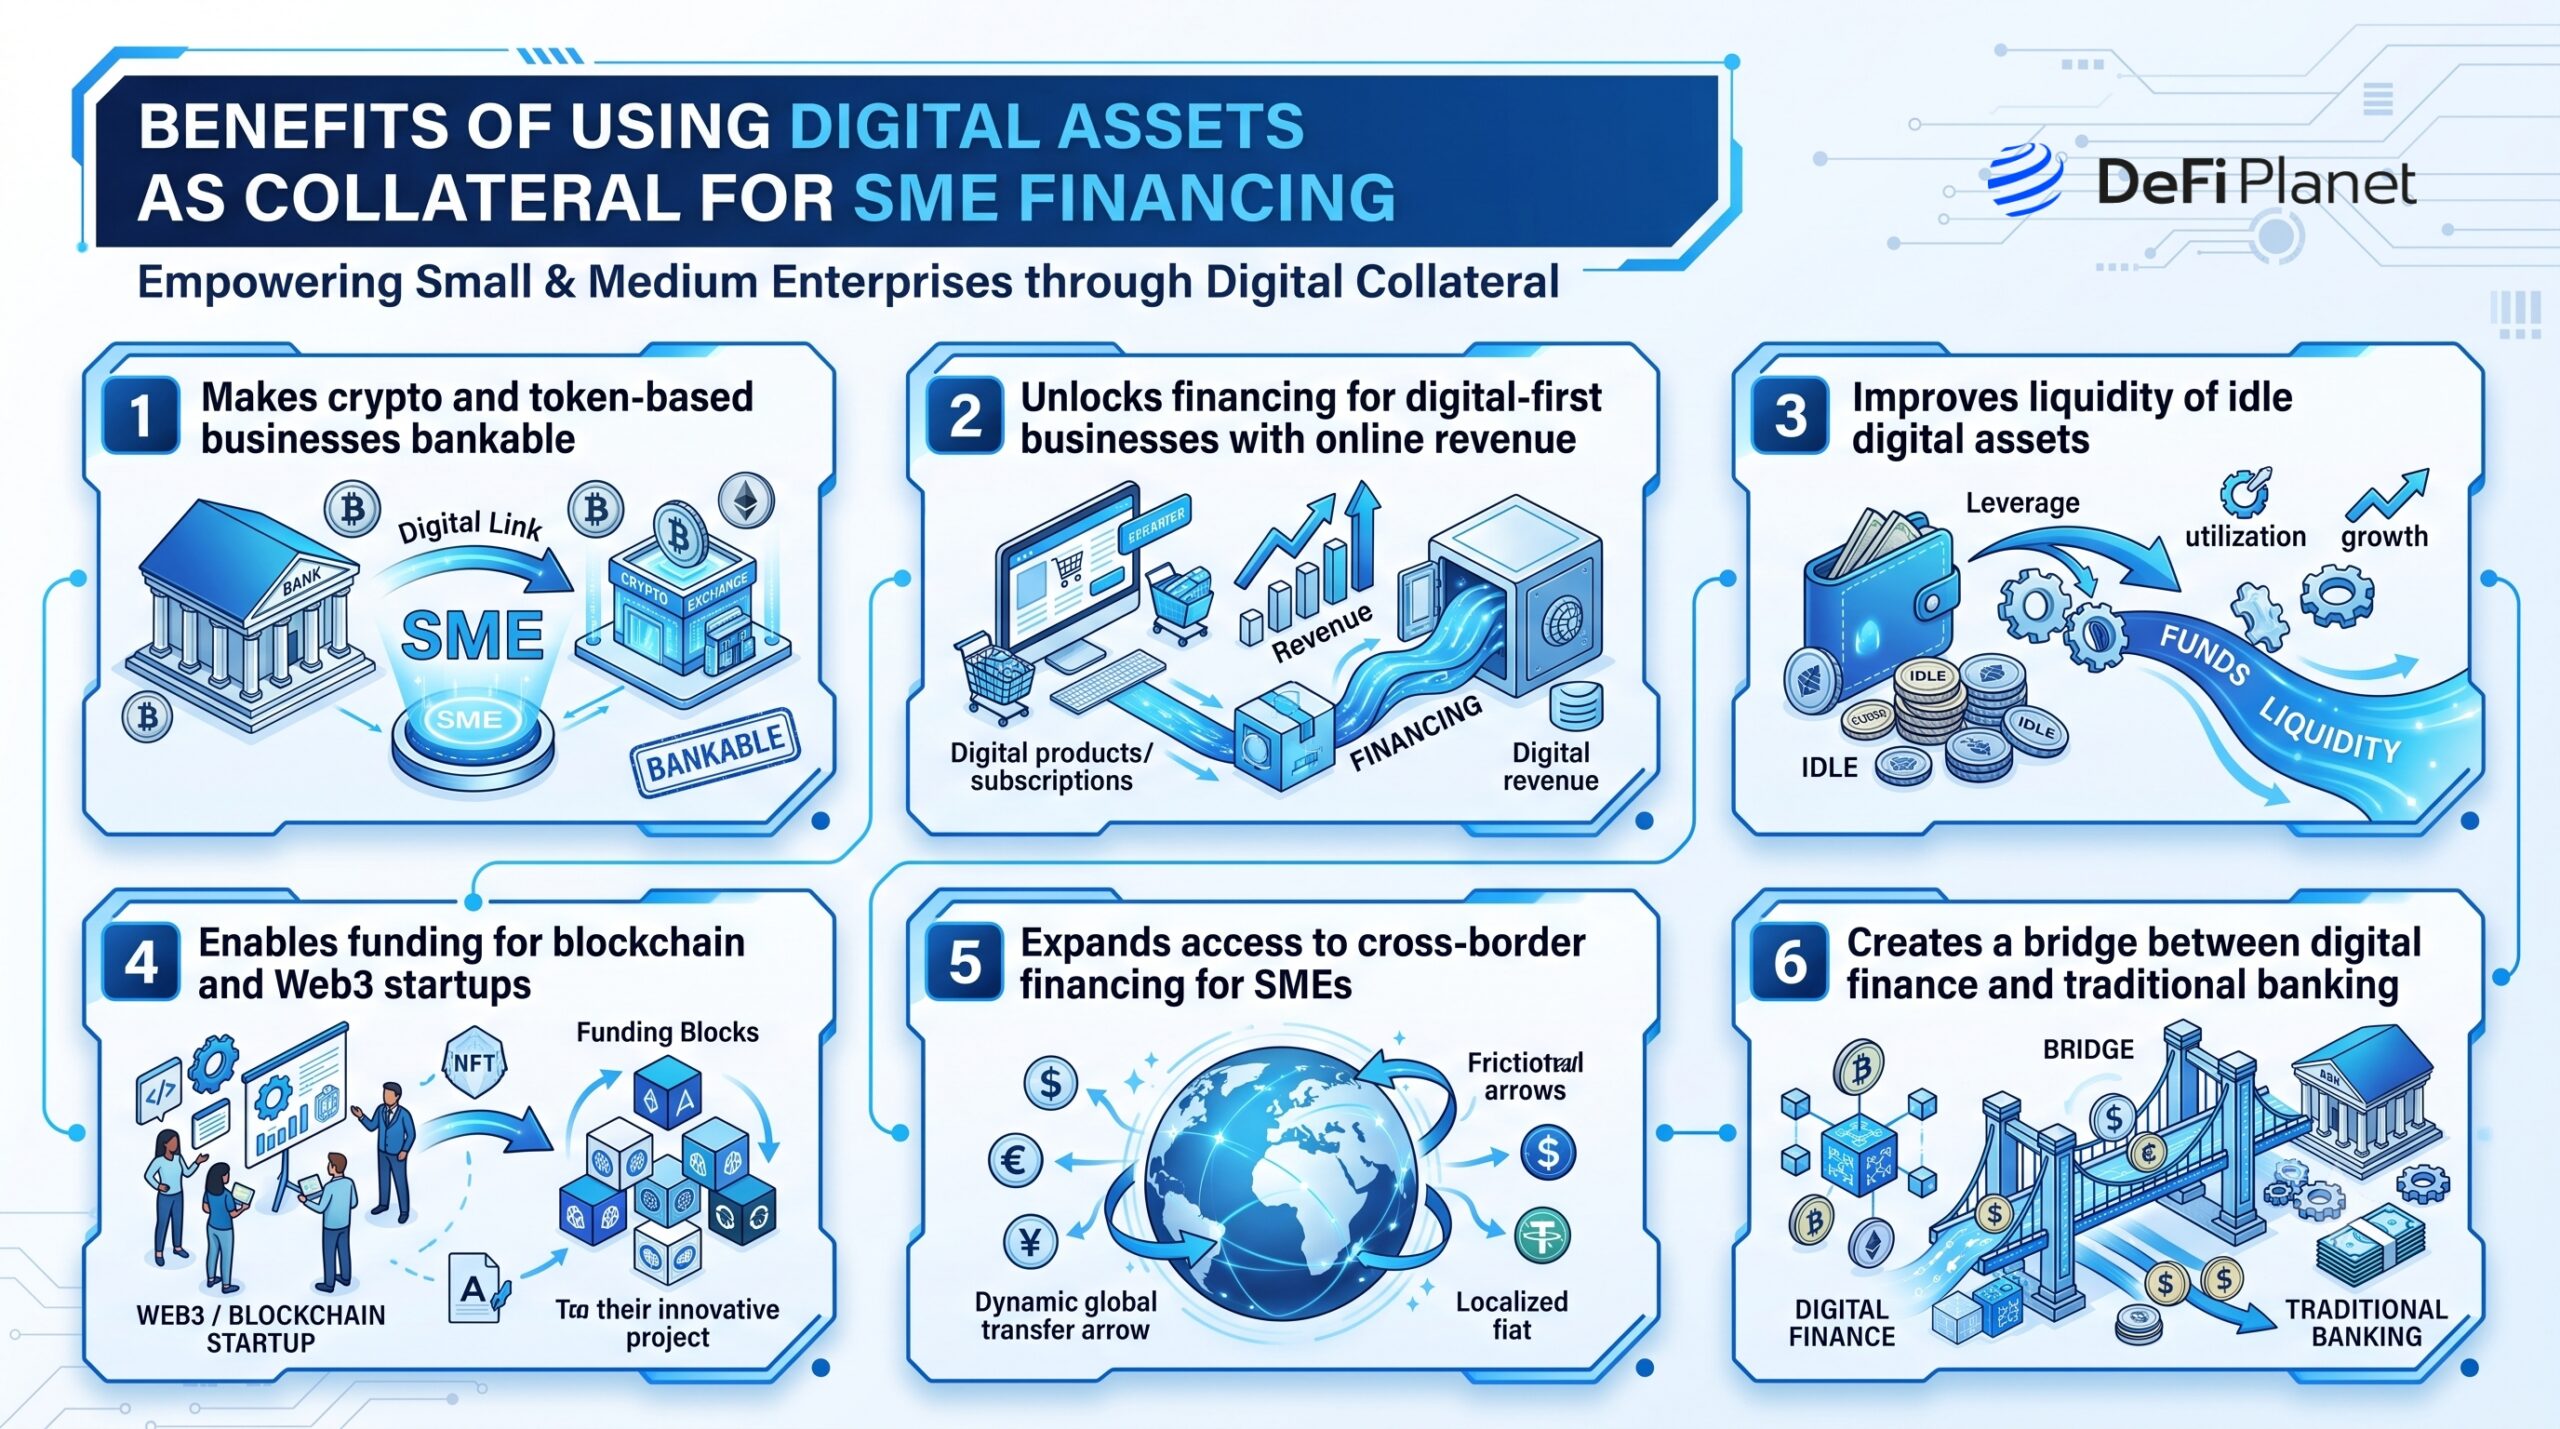
Makes crypto and token-based companies bankable
A number of SMEs could possibly retailer their worth in cryptocurrencies or token-based rewards. As an illustration, a fintech startup firm might have stablecoins as a part of its treasury or earn income in digital tokens. But the startup might face challenges securing a financial institution mortgage. Accepting real digital property as safety will allow such corporations to amass loans with out having to promote all their property by means of money gross sales.
Unlocks financing for digital-first companies with on-line income
There exist corporations that earn digitally and lack any bodily property. These corporations can now make the most of their earnings as safety to entry finance. It will make it potential for Shopify retailers and even cellular app creators to lift cash from their digital earnings.
Improves liquidity of idle digital property
Some SMEs might need idle digital property. These digital property embrace cryptocurrencies, in-game foreign money, or platform-based credit. As an alternative of leaving these property idle, corporations might pledge them towards loans. This is able to imply {that a} gaming agency holding digital tokens may use them to fund sport growth.
Permits funding for blockchain and Web3 startups
As many of the worth of a Web3 firm can be tied up in tokens, sensible contracts, and protocol possession, the corporate is not going to require any typical collateral for its operations. The acceptance of those digital property may open the door to funding of innovation-based corporations that lack bodily property however want vital funding to flourish.
Expands entry to cross-border financing for SMEs
Cross-border transfers of digital property are far faster than these of typical collateral comparable to property deeds. For instance, a small-scale exporter primarily based in Kenya or Vietnam that receives funds in USDT can use these property to safe loans from international lenders while not having any home banking companies. It ensures sooner cross-border SME financing by means of digital property.
Creates a bridge between digital finance and conventional banking
Banks’ willingness to simply accept digital property as collateral would assist set up strategies for the valuation, safekeeping, and danger administration of blockchain property. Consequently, conventional monetary establishments could be higher in a position to combine the digital world into their processes quite than deal with it as an alien idea.
Key Dangers for Banks, Regulators, and SMEs
Whereas digital property can increase entry to credit score for SMEs, additionally they introduce new dangers for banks, regulators, and debtors that aren’t totally current in conventional lending.

Value volatility and collateral instability
Bitcoin and Ethereum costs can fluctuate closely inside a short time. It implies that a enterprise that takes out loans utilizing $100,000 price of Bitcoin as collateral will face challenges if costs plummet by 20-30% and it fails to fulfill the required collateral price.
It turns into tough to plan repayments as a result of digital property can not predictably preserve their worth the way in which tangible property can.
Problem in valuation and standardization
Not like actual property, digital property shouldn’t have a single commonplace approach of valuation. For instance, a nonfungible token (NFT), a loyalty asset, or a digital proper associated to sure software program might be valued in a different way relying on the platform. Whereas some lenders see excessive worth and demand, others may think about the digital asset to be of low worth as a consequence of an absence of liquidity.
Custody and safety dangers
Digital property depend on non-public keys and digital wallets. An SME proprietor may lose entry to a digital pockets containing their crypto collateral. Moreover, if there may be any hacking within the custodial platform, the property might be gone for good. One such incident includes the theft of hundreds of thousands of {dollars} in person funds from exchanges.
Regulatory uncertainty throughout jurisdictions
There are vital variations within the regulation of the digital asset area throughout jurisdictions. As an illustration, an SME in Vietnam utilizing crypto-backed financing would face completely different authorized issues if it expands into different jurisdictions, comparable to Singapore or the EU. Such inconsistencies complicate banks’ efforts to design cross-border lending merchandise.
Restricted liquidation choices in confused markets
Throughout market volatility, promoting one’s investments turns into more durable. As an illustration, throughout a market panic and sharp value declines, it turns into difficult for banks holding crypto collateral to rapidly promote it within the secondary market with out incurring vital losses, in contrast with promoting different typical property like equipment and industrial buildings.
The place Digital Asset-Backed Lending Might Be Headed
Within the early levels, the usage of digital property as collateral will stay restricted and intently regulated. The regulators may allow banks to experiment with small-scale pilots that contain the usage of solely low-risk digital property like stablecoins and tokenized state property as collateral to check their behaviour beneath sure circumstances and regularly transfer in the direction of extra sophisticated crypto.
In due time, rules will turn out to be clearer relating to the standards for acceptable collateral, valuation of these property, and the strategies of their storage. The participation of licensed custodians, liable for storing digital property in a fashion much like present collateral, may turn out to be a part of future practices.
A possible development related to the event of digital asset-secured loans might be thought-about tokenization. Varied real-life collaterals like invoices, receivables of corporations, and even property rights may turn out to be tokenized and used as collateral for additional loans. This is able to permit SMEs to unlock worth from property which can be normally exhausting to make use of in conventional lending programs.
Additionally, lending selections might turn out to be extra data-driven. Slightly than utilizing the collateral method, lenders may consider corporations primarily based on the transactions they’ve carried out, their revenues, and their normal pockets behaviour. For instance, if a small firm had strong, common money flows, it might be eligible for loans even with out proudly owning conventional property.
In the long run, digital property may additionally result in a very world SME financing mannequin, since they aren’t tied to geographic places. Therefore, a startup working in creating international locations comparable to Kenya, Vietnam, or Nigeria would have the ability to elevate funds rather more simply on the worldwide market than on the native one.
A Transition That Is Nonetheless Taking Form
Digital property have been regularly remodeling themselves from speculative devices into constructing blocks for sensible credit score frameworks. Ought to this development proceed, SME financing would possible see a transition away from dependence on tangible property to reliance on worth era in digital/hybrid enterprises. However the course will rely closely on how rapidly banks, regulators, and markets can construct belief round valuation, custody, and enforcement.
What’s changing into clear is that collateral is now not restricted to what a enterprise owns in bodily type. The larger query now’s how monetary programs will steadiness alternative with danger as they begin recognizing digital worth. The end result will possible decide whether or not this turns into a narrow-niche experiment or a structural change in how small companies entry credit score in rising markets.
FAQs
How will banks truly confirm digital property used as collateral?
Banks might depend on third-party custodians, blockchain analytics instruments, and audited pockets proofs to substantiate possession and worth. In observe, this implies a lender might require property to be held in regulated wallets quite than self-custody earlier than they’re accepted.
Can stablecoins be safer than different digital property for lending functions?
Sure, in lots of instances. As a result of stablecoins are pegged to fiat currencies just like the US greenback, they cut back value volatility danger. This makes them simpler for lenders to worth persistently in comparison with property like Bitcoin or smaller tokens.
What occurs if a borrower defaults on a mortgage backed by digital property?
If a borrower fails to repay, the lender can liquidate the digital collateral by means of exchanges or custodial platforms. Nevertheless, the velocity and worth recovered depend upon market liquidity on the time, which may differ broadly throughout unstable durations.
Will SMEs have to convert their digital property into money earlier than utilizing them as collateral?
Not essentially. In lots of proposed fashions, property can stay in digital type and be pledged immediately, which means companies don’t have to promote them. As an alternative, the property are locked or held in custody till the mortgage is repaid.
Might digital asset collateral enhance lending dangers for small companies?
Sure, particularly if asset values fall sharply or if regulatory guidelines change rapidly. SMEs might face margin calls or tighter mortgage circumstances in comparison with conventional collateral, making danger administration extra necessary than earlier than.
Disclaimer: This text is meant solely for informational functions and shouldn’t be thought-about buying and selling or funding recommendation. Nothing herein must be construed as monetary, authorized, or tax recommendation. Buying and selling or investing in cryptocurrencies carries a substantial danger of monetary loss. All the time conduct due diligence.
Loved this? Bookmark DeFi Planet, discover associated subjects, and comply with us on Twitter, LinkedIn, Fb, Instagram, Threads, and CoinMarketCap Neighborhood for seamless entry to high-quality business insights.
Take management of your crypto portfolio with DEFI PLANET PRO, DeFi Planet’s suite of analytics instruments.

