

Ten dairy cows in Paraná, Brazil, carried encrypted identities that Cowmed collars had constructed from every animal’s well being, habits, and site information into B3 this week.
These identities turned the cows into collateral for almost $20,000 in credit score, and the file behind them goals to shrink the haircut lenders apply and cease lenders from pledging the identical animal twice.
Brazil’s pilot proves the mechanics work at a small scale, and the larger alternative sits in international locations the place farmers personal precious livestock and can’t borrow in opposition to it as a result of they lack the land titles banks require.
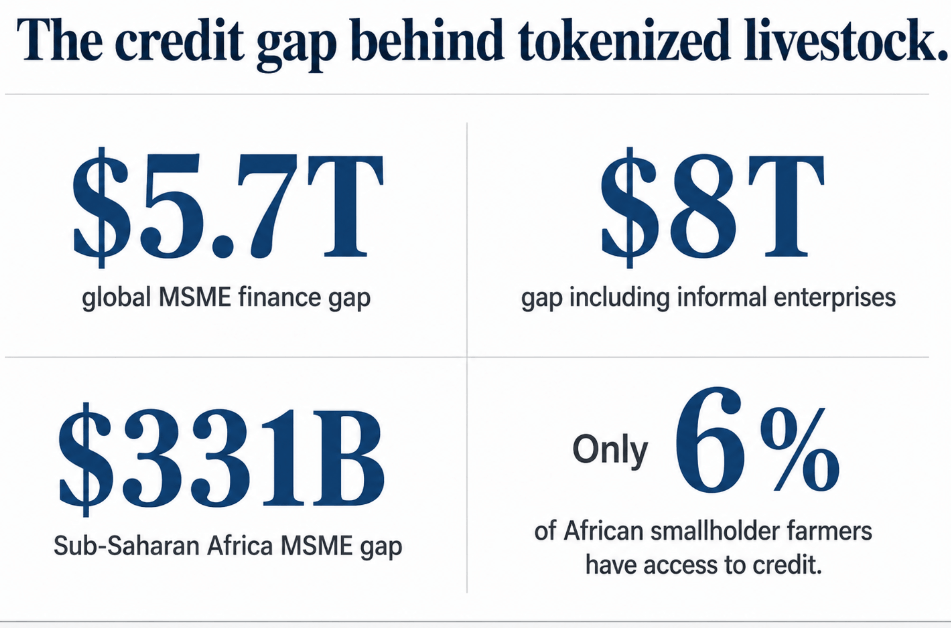
The worldwide hole between what small companies must borrow and what they will entry runs to $5.7 trillion, climbing to $8 trillion as soon as casual enterprises rely too. Sub-Saharan Africa alone accounts for roughly $331 billion of that hole, and the African Growth Financial institution places credit score entry amongst African smallholder farmers at simply 6%.
Livestock represents wealth these farmers already personal, so the check turns into whether or not digital identification, collateral registries, insurance coverage and lender claims can join effectively sufficient to show that wealth right into a mortgage a financial institution will make.
The place the infrastructure already exists
Ethiopia holds Africa’s largest livestock inhabitants, and its central financial institution already runs an digital registry that names cattle, camels, sheep, goats and poultry as eligible collateral.
The nation can also be constructing an official livestock identification and traceability system, and its 2025-2030 agricultural finance roadmap places financing demand for livestock prices and herd replenishment at roughly ETB 911 billion.
Ethiopia has each authorized recognition and an identification layer taking form, however lenders nonetheless lack dependable valuation, insurance coverage, well being information and a transparent strategy to recuperate the mortgage if a borrower defaults.
Nigeria carries the most important near-term financing hole within the group, with the IFC placing unmet credit score demand amongst Nigerian small companies at about $32.2 billion.
A central financial institution registry already lets farmers pledge livestock, together with unborn offspring, and checks whether or not the identical animal has already secured one other mortgage elsewhere.
A separate identification system tags cattle with ear tags and digital passports, and a $500 million livestock program working by means of 2028 units apart $70 million particularly for entry to finance.
Nigeria already has the registry, the animal identification system and the financing program as separate items, with no single product but connecting them into one mortgage course of.
Kenya’s Movable Property Safety Rights Registry runs across the clock, and the nation’s agricultural information methods had registered over 7.2 million farmers by 2025.
Lenders registered 34,638 livestock belongings as collateral within the 12 months to June 2023, a part of roughly KSh 5.1 trillion in credit score that movable belongings supported total.
That makes Kenya the group’s management case, with a centralized registry that already accepts livestock at scale there, so tokenization has to show it lowers the haircut, cuts the rate of interest, and confirms an animal continues to be alive and wholesome.
It additionally has to hurry substitution when an animal dies or is offered, and cease lenders from pledging the identical animal twice, one thing the centralized registry might already deal with by itself.
Fewer than 200,000 of Pakistan’s 3.2 million small and medium enterprises have formal credit score entry. Livestock nonetheless accounts for about 14.6% of GDP and over 62% of agricultural worth added.
In Sindh province, simply over 10% of farmers maintain formal loans, and roughly 80% of rural livestock holders haven’t any land to pledge. Banks typically decline animals as collateral as a result of livestock insurance coverage barely exists, and the World Financial institution discovered solely 16% of farmers holding seven to 50 animals certified as bankable below present situations.
Dying, illness, theft, and drought can nonetheless wipe out a herd, and banks want insurance coverage in place earlier than they are going to settle for livestock as collateral in any respect.
Pakistan makes the clearest case that tokenization wants insurance coverage and dependable veterinary information bundled in. Rural debtors already danger taking up bigger loans in opposition to animals that keep uninsured and {that a} financial institution may nonetheless seize if the mortgage fails.
CountryWhat already existsWhy it mattersMain lacking linkEthiopiaLivestock-eligible collateral registry; animal ID system in growth; ETB 911B livestock finance demandClosest to linking animal identification with authorized collateral recognitionBank merchandise, insurance coverage, valuation, restoration processNigeriaCollateral registry; cattle ear tags and digital passports; $500M livestock program with $70M for financeBiggest near-term financing hole and a number of methods already being builtIntegration into one lender-ready productKenya24/7 movable collateral registry; 7.2M+ registered farmers; 34,638 livestock collateral assetsControl case displaying strange registries can already scaleProof tokenization improves mortgage termsPakistanLarge livestock economic system; extreme SME credit score gapStrongest want for non-land collateralInsurance, financial institution acceptance, borrower protectionMongoliaWeb-based movable-property registry with livestock pledges at scaleShows blockchain shouldn’t be required to file livestock collateralEvidence tokenization provides worth past registry data
The place this goes from right here
Mongolia launched a web-based registry for movable property, and livestock made up 24% of the roughly 90,000 early pledge notices because it was carried out, and later information put livestock close to 25% of the 670,000 pledge notices recorded by June 2023, all with no blockchain concerned.
Trendy digital registries already deal with the core work of recording collateral and setting creditor precedence, some extent the World Financial institution has traced straight. Connecting animal identification, well being information, insurance coverage protection, market worth and authorized claims throughout separate methods is the work interoperability nonetheless has to complete.
A digitally verified animal has to unlock an even bigger mortgage, a decrease rate of interest, a quicker approval, a less expensive insurance coverage premium or a greater restoration price than the identical animal will get below strange underwriting. Borrowing phrases carry the proof, measured in what a financial institution lends and at what value.
Within the bull case, Ethiopia hyperlinks its animal identification system to its collateral registry, and Nigeria connects its registry, ear-tag system, and financing program into one lending product.
Kenya’s current scale provides each a template to repeat: insurance coverage and veterinary information turn out to be a part of the underwriting course of, haircuts shrink, approval instances drop, and loan-to-value ratios climb.
Livestock stops being an asset farmers merely personal and turns into one they will borrow in opposition to, at scale, throughout a couple of nation.
Within the bear case, the registries and identification methods by no means join. Pakistan’s insurance coverage hole sits because the clearest failure level, and Nigeria’s final result may tip the identical means if its registry, animal IDs and financing program by no means mix right into a mortgage product.
Farmers tackle debt in opposition to animals that go uninsured, are disputed inside households, or are unimaginable for a lender to repossess. Illness, drought, or theft can then wipe out that collateral, together with the borrower’s revenue, in the identical occasion, leaving tokenization as a pilot with no measurable impact on who can borrow.
A traditional database in Kenya and Mongolia can already file which animal secures which mortgage.
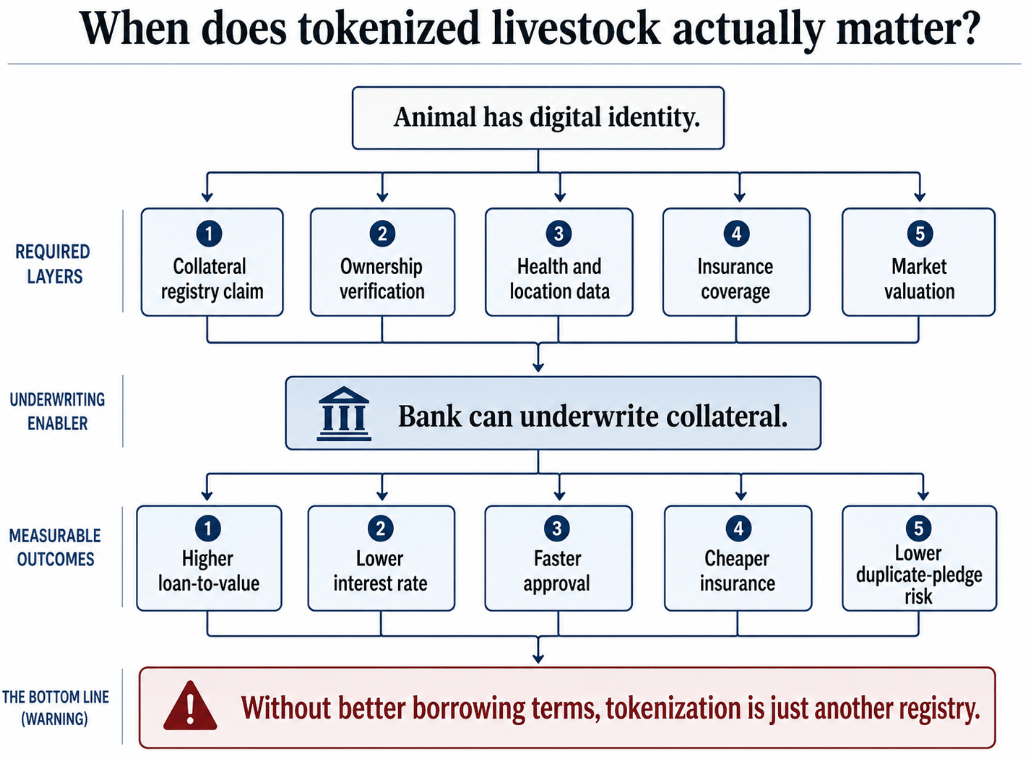
The true check asks whether or not Ethiopia, Nigeria, Kenya, and Pakistan can join identification, insurance coverage, and creditor claims into loans that didn’t exist earlier than, at phrases higher than farmers get at this time.
Brazil’s ten cows proved the mechanics work at a small scale, and whether or not that mechanism turns into rural credit score infrastructure for tens of millions of farmers relies on insurance coverage and registries.


