

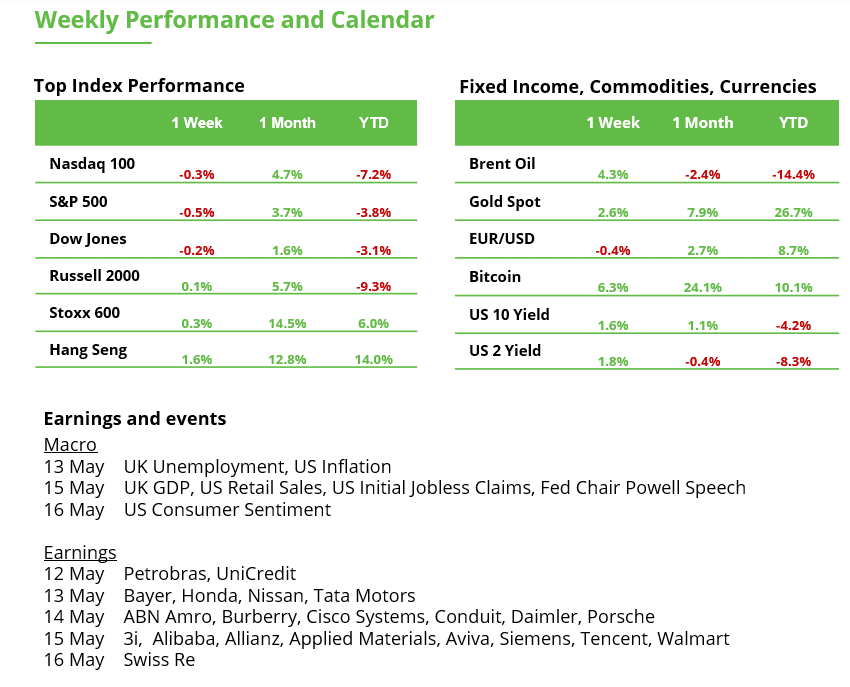
Markets caught a breather as commerce tensions cooled, not less than on paper. The US struck a sector-friendly cope with the UK, whereas talks with China in Geneva had been labeled “substantial progress.” No fireworks but, however the temper music is shifting.
Tariff Détente?
The US and China say they made “substantial progress” in Geneva commerce talks and even arrange a brand new channel for ongoing negotiations. No offers but, however officers promise “excellent news for the world” quickly.
UK-US Commerce Deal: A Aid, however not a Revolution
This week’s UK-US commerce deal might not dismantle Trump’s 10% baseline tariff, nevertheless it delivers strategic wins for key UK exporters, particularly in autos, aerospace, and metal. Jaguar Land Rover (Tata Motors), Bentley (Volkswagen), and McLaren (CYVN Holdings) are respiratory simpler: UK automotive exports to the US will now face only a 10% levy (down from a possible 27.5%) on the primary 100,000 automobiles, successfully protecting 99% of present commerce volumes. Jaguar Land Rover hailed the deal as “important progress,” with implications for long-term funding. Count on stability in JLR’s US-facing gross sales and bullish sentiment for auto-adjacent suppliers. Father or mother firm Tata Motors may even see US-facing income stabilize, whereas components suppliers like TI Fluid Techniques and Johnson Matthey additionally stand to learn.
Rolls-Royce gained tariff-free entry for its jet engines, sending shares up 3.6%. That ought to bolster future transatlantic orders and cut back enter price uncertainty. In the meantime, Boeing rose 2.8% on experiences of a $10bn cope with IAG (British Airways’ guardian), a diplomatic win leveraged by UK aerospace cooperation. Metal producers like Tata Metal UK additionally profit: £370mn of annual metal exports to the US are actually on firmer footing.
But not all are celebrating. UK foods and drinks exporters nonetheless face 10% tariffs, and home farmers worry a flood of sponsored US ethanol and beef. The macroeconomic uplift will likely be modest, however sector-specific readability matters- significantly in capital-intensive industries.
Critically, this settlement units a precedent. Trump rewarded a cooperative accomplice, suggesting future sectoral offers – probably with Europe, Japan, and Korea – might hinge on comparable concessions. Buyers ought to look ahead to alternatives in export-sensitive UK equities and US multinationals benefitting from reciprocal entry. That is tariff diplomacy by quota and the mannequin might stick.
Vitality Lags Whereas Earnings Shine
US Q1 earnings have outperformed expectations, with income up 4.6% and earnings climbing 13.6%, even in opposition to a softer GDP backdrop. However Vitality stands out because the clear weak spot, dragged down by falling oil costs, a pattern unlikely to reverse in Q2. In the meantime, Well being Care posted robust outcomes, and Communication Providers continued to outperform, buffered from tariff-related headwinds. Maybe the largest takeaway this earnings season is how clearly the outcomes spotlight the divergence between the S&P 500 and the broader financial system.
iBot, You Bot, We All Bot For AI Apple’s secret search weapon is threatening Google’s money cow
Google misplaced $180B in market cap this week after one offhand remark: Apple may construct its personal AI-powered search into Safari. That was sufficient to resume fears about Google‘s dominance in search which nonetheless drives nearly all of its advert {dollars}.
It capped off a brutal week for Alphabet (-6.4%) whereas Apple surged (+4%) on hopes of turning into an AI front-runner with out even launching a chatbot (but).
Hold watching: Apple’s Worldwide Builders Convention in June might shift the AI narrative once more, and additional erode Google’s moat.
A Story of Two Retailers
Subsequent Plc and JD Wetherspoon thrive, whereas M&S and others scramble
UK retailer Subsequent popped to an all-time excessive after mountain climbing revenue forecasts (once more), helped by hotter climate and stable on-line gross sales. Funds pub chain JD Wetherspoon additionally toasted a 6% income (like-for-like gross sales) bump. However not all UK client names had been elevating a glass: M&S took a £30-40 million hit from a cyberattack, with extra losses presumably brewing.
What’s subsequent: Walmart and Alibaba report earnings this Thursday, providing a peek at how world retail giants are faring in very totally different economies.
ETH/BTC Ratio Breaks Out
The ETH/BTC ratio seems to be turning to the upside, signalling that Ethereum is gaining power in opposition to Bitcoin, as technical indicators like oversold RSI ranges and a technical breakout recommend a cyclical reversal. Moreover, on-chain information exhibits decreased alternate provide and whale accumulation, additional supporting ETH’s bullish momentum. For extra on this, take a look at: – https://youtu.be/L2it3-Kdjo0
Tailwind for Cyclicals? Commerce Talks Give Markets Hope
Tariffs stay the dominant theme within the markets, hitting cyclical sectors significantly arduous. Industrials, Supplies, and Shopper Discretionary are particularly affected. These sectors are extremely export-oriented and react sensitively to disruptions in world provide chains.
However there’s additionally hope: In accordance with media experiences, the US and China have made “substantial progress” in two days of talks in Switzerland geared toward easing commerce tensions. The prospect of decrease tariffs reduces dangers for world commerce and supplies tailwind for cyclical sectors.
Decrease tariffs imply stronger progress, rising demand, and a extra constructive outlook – particularly for Expertise, Shopper Discretionary, and Industrials. Price cuts might additionally transfer again into focus, which might profit progress shares like Tech, in addition to Actual Property and Utilities. Financials, then again, have a tendency to learn extra from larger rates of interest.
Defensive sectors proceed to function stability anchors. Well being Care, Shopper Staples, and Utilities are likely to carry out nicely in periods of elevated uncertainty.
Three of the largest underperformers to date this yr are Communication Providers, Data Expertise, and Shopper Discretionary. The important thing query stays: Will momentum shift quickly? The broader market is approaching key technical ranges.
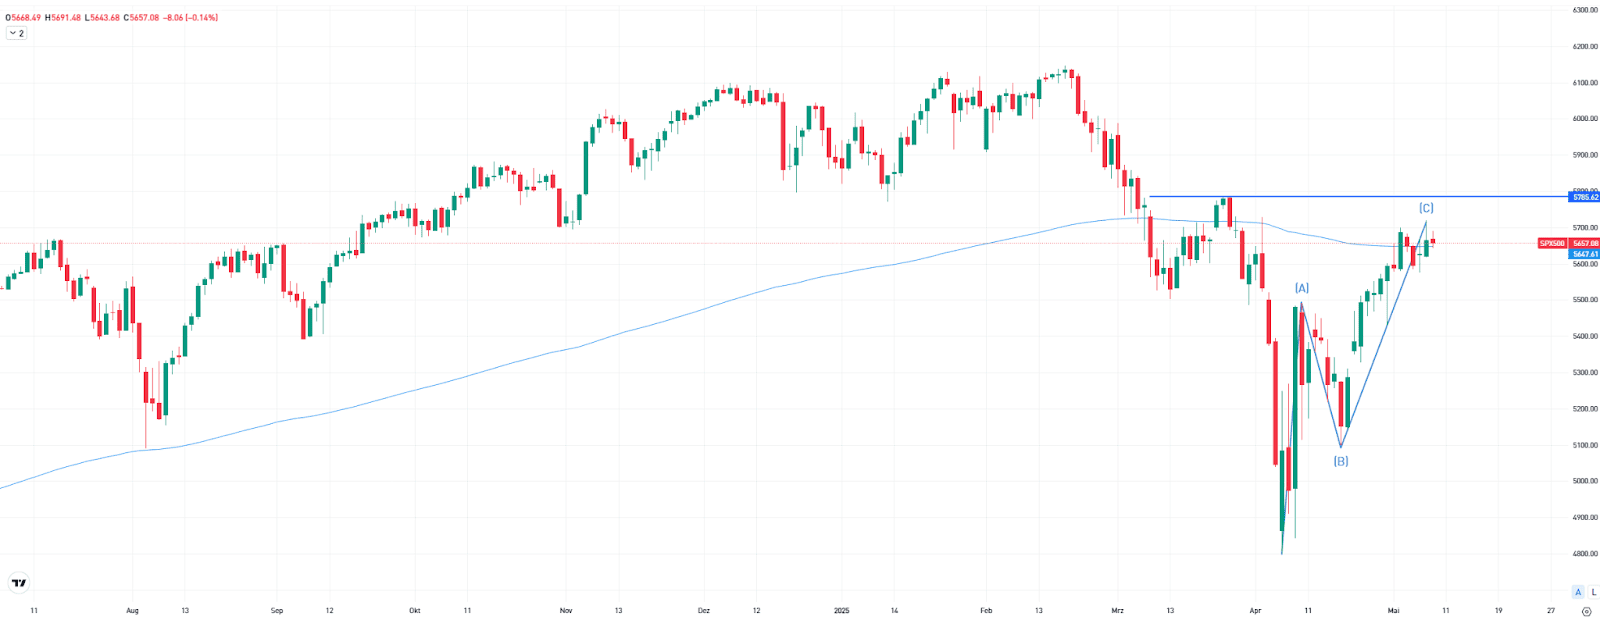
The S&P 500 has seen a transparent restoration over the previous weeks within the type of an ABC sample and has returned above the intently watched 200-day transferring common (see chart). Nevertheless, the upward motion stalled just under the March 25 excessive of 5,786 factors. This degree have to be sustainably breached for a short-term uptrend to evolve right into a medium-term pattern.
S&P 500 – Every day Chart
Tight Vary, Huge Transfer? GBP/USD Approaches a Determination Level
Subsequent week might be particularly fascinating for GBP/USD merchants, with the financial calendar full of key information from the UK and the US – an atmosphere that guarantees elevated volatility.
On Tuesday, UK labor market information and US CPI inflation take middle stage. On Thursday, we’ll see UK Q1 GDP and US retail gross sales, adopted by a US actual property and client sentiment information bundle on Friday.
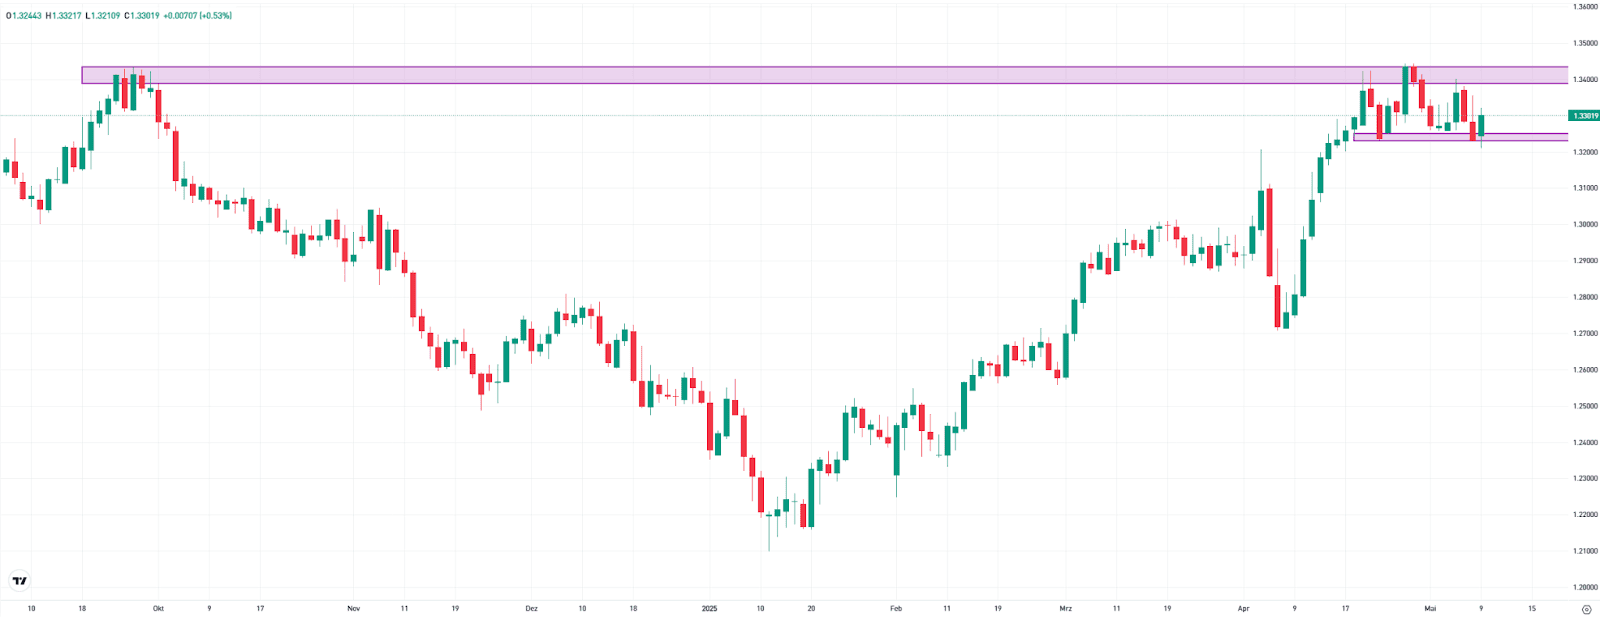
GBP/USD is presently buying and selling in a slender vary between 1.3230 and 1.3440 (see chart). The general uptrend stays intact. The each day chart exhibits a construction of upper highs and better lows. The September excessive initially blocked additional positive aspects, however bulls not too long ago defended the important thing help degree from April 23.
Merchants ought to put together for potential setups. A second check of the September excessive is feasible if help at 1.3230 holds. Wanting additional forward, a big resistance zone lies round 1.36. A break under 1.3230, nonetheless, would clearly weaken the chart image and sure set off a correction towards 1.30.
GBP/USD – Every day Chart
This communication is for info and schooling functions solely and shouldn’t be taken as funding recommendation, a private suggestion, or a proposal of, or solicitation to purchase or promote, any monetary devices. This materials has been ready with out taking into consideration any explicit recipient’s funding aims or monetary state of affairs and has not been ready in accordance with the authorized and regulatory necessities to advertise unbiased analysis. Any references to previous or future efficiency of a monetary instrument, index or a packaged funding product will not be, and shouldn’t be taken as, a dependable indicator of future outcomes. eToro makes no illustration and assumes no legal responsibility as to the accuracy or completeness of the content material of this publication.


