

Analyst Weekly, July 21, 2025
Banks Earnings: From Protection to Deployment
We’ve got reviewed earnings calls from main US banks, together with Goldman Sachs, JPM, Blackrock, Citi, Wells Fargo, BNY, BoA, MS, and PNC. The temper has notably shifted, and for the higher.
To us, Banks more and more appear to be levered performs on financial normalization and tech infrastructure, not simply rates of interest.
Listed below are our broad takeaways:
Deregulation:
Compliance prices will probably be a key metric to look at over the approaching months, as they could provide the clearest sign that deregulation is beginning to take maintain. Whereas regulatory adjustments usually take time to materialize, declining compliance spend might recommend the early influence of coverage shifts, probably offering a tailwind to earnings. We count on these adjustments to help the monetary sector over the subsequent 12 months. Decreased regulatory friction might additionally assist unlock capital markets exercise, together with a pickup in IPOs and M&A.
Earnings transcripts from main banks reinforce this view, exhibiting early indicators that regulatory rollbacks are starting to take impact. Compliance prices, lengthy a drag on profitability, look like peaking, with some corporations guiding for a decline beginning in 2026. On the similar time, reductions in stress capital buffers (SCBs) and anticipated recalibrations of the SLR and GSIB surcharges are rising capital flexibility. Executives broadly welcomed this shift, citing improved circumstances for capital deployment, deal-making, and competitiveness.
Macro to Micro:
There’s a clear pivot from macro defensiveness to client-driven development. The strongest momentum is in funding banking, structured credit score, and different methods.
CEO Tone: Sharply Extra Constructive
Executives are decisively extra forward-leaning than in current quarters. Sentiment is particularly sturdy for companies tied to capital markets, options, and financing.
“The accelerated innovation and disruption from AI is ready to create important demand-related infrastructure and financing wants.” — Goldman Sachs CEO
“Buyer habits additionally modified and matched digitization… Now we have now an opportunity to seize the worth of that with the brand new enhanced capabilities of AI.” — Financial institution of America CEO
Strategic Themes Gaining Traction:
AI and Platform Fashions are shifting from testing to monetization.
Capital aid (SCB, SLR, GSIB revisions) is already influencing buyback plans and ROE steerage.
IB pipelines are rebounding, with sequential development in M&A and IPO exercise.
Mortgage development is modest however enhancing, with indicators of re-leveraging in Prime, ABS, and center market.
AI adoption is actual and firm-wide, banks count on measurable margin elevate in 2–3 years.
Tokenization goes institutional: main gamers are positioning to anchor digital asset infrastructure.
Dangers: Nonetheless Current, However Downplayed:
Business actual property (CRE) and broader credit score issues stay, however administration commentary has shifted from “watchful” to “underneath management.”
Funding Takeaway: Within the US, we predict that banks are benefiting from deregulation, tax certainty, and a situation which will see stabilising inflation with no imminent recession (a steeper curve). After 18+ months of macro warning, banks are shifting into deployment mode, with clearer visibility on regulatory aid, rising shopper demand, and monetization of AI and digital infrastructure investments. From a positioning perspective, we don’t see large-cap banks as simply rate of interest performs; they’re now levered autos on capital markets normalization, personal credit score growth, and enterprise tech adoption.
Sector Focus: Broader Financials
IPOs, Credit score, and M&A Selecting Up:
Capital markets exercise is rebounding decisively:
IPO issuance in H1 25 is up ~11% y/y, and greater than +100% versus the lows of 2022 to 2023.
Company bond issuance (IG & HY) stays sturdy, regardless of powerful comps from 2024.
M&A deal circulation is regular, although deal closures stay a watchpoint.
Total, expectations that had overshot post-election and undershot at mid-cycle lows now seem appropriately aligned with precise market exercise. This normalization strengthens the case for sustained upside in financials by way of year-end.
Fundamentals & Valuations:
Following early Q2 earnings stories, anticipated earnings development for the sector jumped from 2.7% to 7.8%, whereas income forecasts rose from 1.2% to 2.1%. With deregulation unfolding and a probably steeper yield curve, profitability might proceed to shock to the upside. Valuations (P/B) have normalized, whereas ROEs stay stable, supporting the funding case.
Deregulation Tailwinds:
The deregulation story stays an vital tailwind for financials over the subsequent 12 to 24 months. Past enhancing profitability, it considerably improves capital flexibility, fueling share buybacks and dividends. Financials have been the second-largest patrons of their very own inventory, repurchasing over $190B prior to now 12 months, and that quantity might rise as regulatory constraints ease.
One of the vital impactful developments was the slashing of funding for the Client Monetary Safety Bureau (CFPB) underneath the brand new tax invoice.The CFPB is the US company liable for regulating client finance merchandise like bank cards, auto loans, and private lending. Reducing its funding is anticipated to scale back regulatory oversight and enforcement, significantly for client finance corporations, that are already exhibiting the strongest upward earnings revisions for 2025 and 2026.
Magazine 7 Earnings Begin This Week
What we’re watching: whether or not corporations, particularly the massive tech “hyperscalers” like Amazon, Microsoft, and Google, will maintain spending closely on AI infrastructure. This spending is an element of a bigger capital expenditure cycle that’s been fueling the AI increase.
To this point, these corporations are prone to keep and even enhance funding, particularly as early indicators present that AI is beginning to increase earnings.
A key coverage angle comes from the brand new tax invoice within the US, which incorporates enterprise tax incentives geared toward encouraging corporations to deliver ahead (pull ahead) their spending into 2025, serving to to offset the price of new tariffs.
Traditionally, tax breaks like full expensing (the place corporations can instantly deduct the price of investments) have helped industrial corporations, and we predict it might additionally profit software program corporations this time, particularly these constructing or promoting AI instruments.
Tesla & Alphabet (July 23): Deal with automobile supply developments and cloud development.
Meta (July 30): Search for particulars on AI/information middle investments and person advert income.
Apple & Amazon (July 31): iPhone demand and AWS profitability + steerage.
Nvidia (Aug 27): Investor consideration on Blackwell chip rollout and export restrictions.
Microsoft (July 30): Azure/AI income momentum and margin developments.
GENIUS Act: The US Goes All-In on Stablecoins
The US has signed the GENIUS Act into regulation, the primary main piece of US crypto laws, setting a transparent regulatory framework for the issuance and buying and selling of stablecoins.
This long-awaited readability opens the door for banks, asset managers, retailers, and cost processors to actively enter the stablecoin house with out regulatory ambiguity.
The regulation comes at a pivotal second: stablecoins have develop into the core liquidity layer connecting crypto and conventional finance, enabling quick, dollar-denominated transactions with out friction.
Analysts ought to watch three potential implications:
Capital flows into regulated stablecoin infrastructure might speed up, probably unlocking trillions in on-chain cost rails, tokenized securities, and automatic finance.
The Act reinforces Ethereum’s dominant place because the core blockchain for stablecoin issuance, because of its transparency, composability, and institutional adoption.
The subsequent battleground is regulatory readability on the broader crypto market construction: tokenized securities, personal fairness, and custody guidelines are actually in focus.
The GENIUS Act will not be the tip of the street—it’s the start of regulated crypto infrastructure at scale on this planet’s largest economic system.
Merchants Eagerly Await The ECB Curiosity Fee Choice
The ECB will announce its rate of interest determination on Thursday. No change is anticipated. Nonetheless, the next press convention with Christine Lagarde might set off volatility within the markets. Traders are hoping for clues concerning the future rate of interest path. Feedback on commerce coverage, inflation dangers and development prospects will assist assess how the central financial institution views the present state of affairs, and whether or not the euro’s appreciation in current months is justified.
EURUSD has skilled a decline for the reason that begin of July. In the midst of final week, the pair reached the truthful worth hole zone between 1.1543 and 1.1574. Nonetheless, value motion has since entered a sideways vary, as patrons had been held again by one other zone round 1.1650. The broader uptrend stays intact, making a transfer towards 1.18 the almost definitely situation. A break beneath 1.1543, nevertheless, might open the door for sellers to focus on earlier lows at 1.1449 and 1.1373.
EURUSD within the every day chart, correction inside the uptrend
Can SAP Justify the Advance of Belief? Quarterly Outcomes on Tuesday
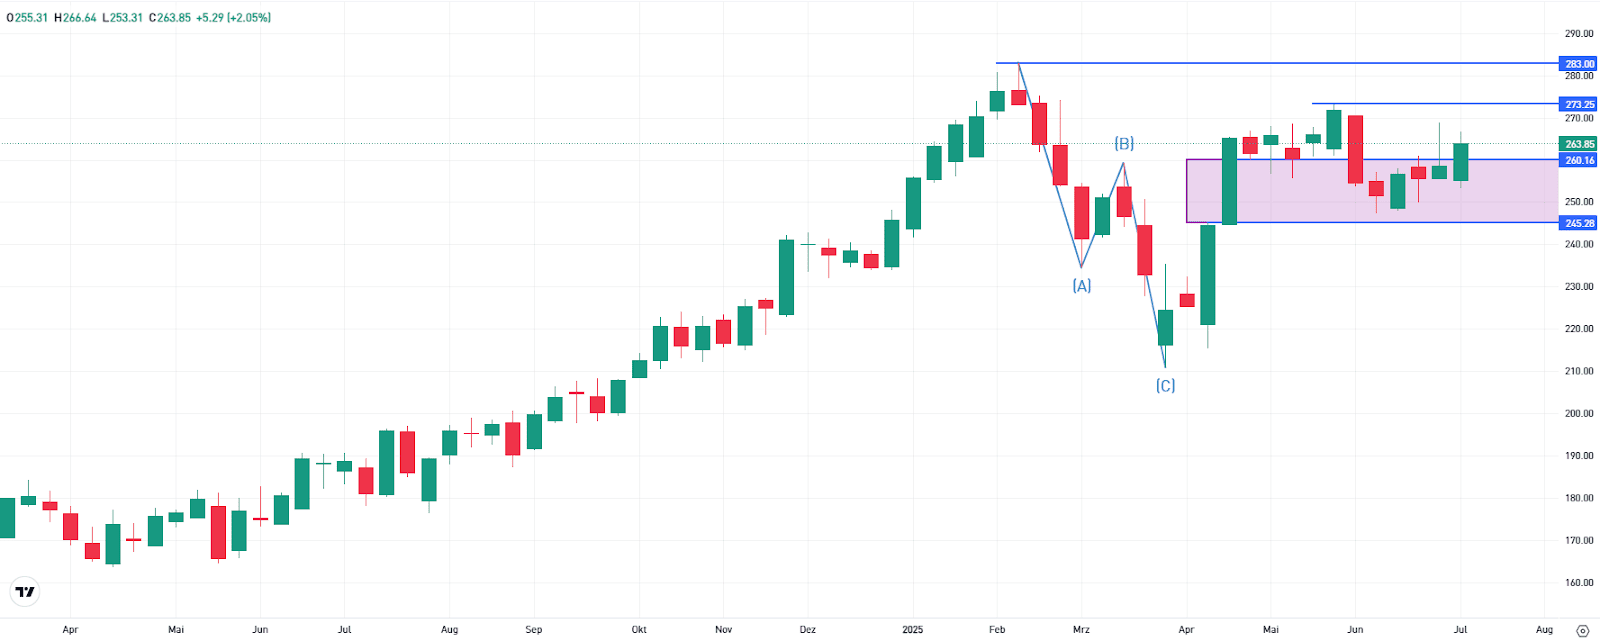
The SAP inventory, with its value enhance final week, has supplied a great setup to succeed in a brand new document excessive within the coming weeks; it’s 7% away. Nonetheless, the inventory’s excessive valuation makes it susceptible to short-term profit-taking. The ahead P/E ratio stands at 42, considerably increased than that of friends like Microsoft, Oracle, and Salesforce.
However, SAP has persistently demonstrated sturdy operational efficiency. As well as, the forecasts for the second-quarter outcomes are promising, and analysts see potential for an upward revision of the earnings outlook. In instances of commerce conflicts, SAP additionally advantages from a structural benefit in comparison with different sectors. The corporate doesn’t promote {hardware} however as an alternative focuses on cloud options and synthetic intelligence, making it solely not directly uncovered to the influence of tariffs.
Technical launchpad?
SAP shares ended final week up 2% at €263. After stabilizing in current weeks, the inventory noticed renewed curiosity inside a medium-term help zone. Following a robust rebound from the April low, a so-called Truthful Worth Hole shaped – a value hole between €245 and €260. The share value fell again into this zone, the place the sell-off was halted.
Earlier than the April low, the inventory confirmed a textbook ABC correction sample. The present hole to the document excessive is about 7%. For the possibilities of retesting that top to enhance, patrons must push by way of the June excessive at €273 first.
This communication is for info and training functions solely and shouldn’t be taken as funding recommendation, a private advice, or a proposal of, or solicitation to purchase or promote, any monetary devices. This materials has been ready with out taking into consideration any specific recipient’s funding goals or monetary state of affairs and has not been ready in accordance with the authorized and regulatory necessities to advertise unbiased analysis. Any references to previous or future efficiency of a monetary instrument, index or a packaged funding product should not, and shouldn’t be taken as, a dependable indicator of future outcomes. eToro makes no illustration and assumes no legal responsibility as to the accuracy or completeness of the content material of this publication.


