

Analyst Weekly, August 4, 2025
Large Tech feasts, the remainder nibble. Microsoft and Meta crushed Q2 earnings, however half of S&P 500 firms reported margin declines. Whereas traders cheer AI-fueled development, the actual financial system’s displaying indicators of a tariff hangover and rising price complications.
Earnings Season: Power on the Prime, Stress in Sure Pockets
The newest earnings season has underscored a widening divide in US fairness markets. On the prime, tech giants and large banks have posted sturdy outcomes. Microsoft, Meta, JPMorgan, and Goldman Sachs all delivered double-digit revenue development, reinforcing a notion of resilience in key segments of the index.
Beneath these headline beats, nevertheless, the story is extra nuanced. Latest weeks have introduced tariff-related volatility, a weaker-than-expected jobs report, and softer earnings throughout shopper and cyclical sectors. Corporations like Ford and GM reported losses tied on to tariff prices. Supplies and industrial companies additionally warned of margin compression. Oil majors Chevron and Exxon noticed earnings decline 31% and 23%, respectively, whilst they maintained buybacks and dividends.
Throughout the S&P 500, income development stays constructive, however earnings are beneath pressure, particularly in sectors tied to the actual financial system corresponding to vitality, supplies, and industrials. Eight of 11 sectors reported year-over-year declines in internet revenue margins in Q2 2025. Regardless of this broad trailing weak spot, index-level earnings forecasts stay unfiltered, because of sturdy margin efficiency in know-how, monetary, and communication companies.
What we’re seeing then, shouldn’t be uniformly broad-based energy, however reasonably a market the place sturdy efficiency from a small variety of mega-cap shares continues to form the headline narrative, successfully muting the underlying softness in additional cyclically delicate elements of the financial system.
Supply: Bloomberg, as of July 31, 2025.
Why the S&P 500’s Valuation Doesn’t Inform the Entire Story
Regardless of indicators of weak spot throughout giant elements of the index, the S&P 500 continues to commerce at ~22–24x ahead earnings. Progress-oriented shares commerce close to 32x, whereas worth names stay nearer to 18x, highlighting a widening disconnect in how future earnings are being valued. That is because of the outperformance of a slim set of extremely capitalized, tech-driven companies whose management now disproportionately shapes index-level valuations.
This focus is seen in sector weights too. NVIDIA alone now accounts for 7.7% of the index, on its solution to equaling your entire healthcare sector at 9.0%. Conventional defensive sectors corresponding to utilities (2.4%), staples (6.0%), and healthcare (9.0%) have fallen to their lowest mixed index share (17.4%) in over twenty years.
Historically, traders turned to those defensive fairness sectors in addition to long-duration Treasuries to hedge draw back dangers. However with defensive sectors out-weighed by Magazine 7 names and bonds nonetheless underwater practically 10 months after the primary fee reduce, these hedges have confirmed ineffective.
Because of this, investor curiosity has shifted towards extra constant draw back safety and valuation help, together with:
Actual belongings, commodities and infrastructure performs
Uncorrelated diversifiers, together with digital belongings and gold
Multi-asset earnings methods
Regional and worldwide worth performs
Throughout each theUS and worldwide markets, there are pockets of firms buying and selling at 6–10x normalized earnings, usually with stability sheet energy and free money movement yields effectively above market averages. In sectors like vitality, regional banking, and industrial manufacturing, valuations have compressed regardless of steady or bettering operational efficiency. Many of those companies are priced close to or under e-book worth, with dividend protection supported by working money flows reasonably than development projections.
In a market more and more pushed by momentum and concentrated development narratives, these missed segments provide a extra grounded path, not essentially as contrarian bets, however as a part of a extra balanced, valuation-aware method to portfolio building.
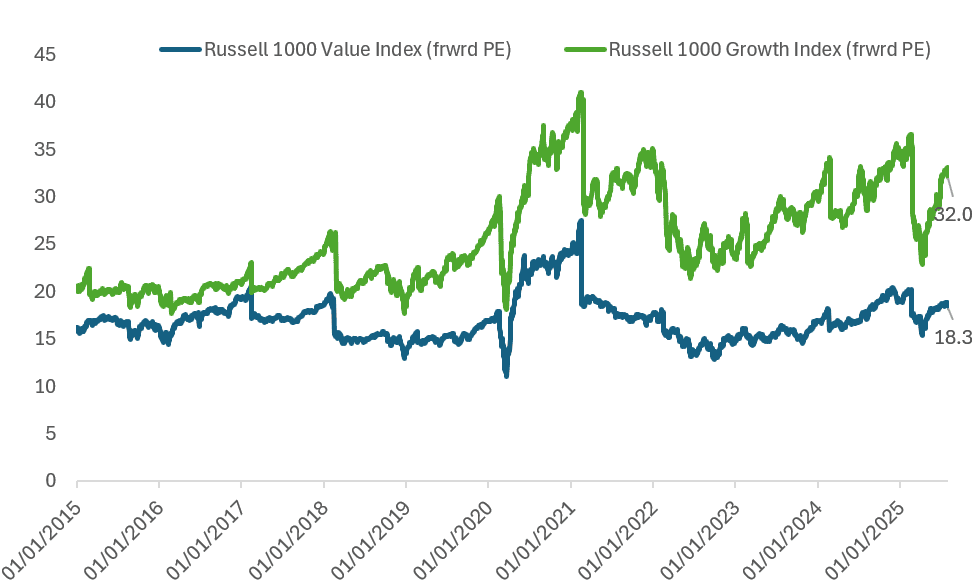
Supply: Bloomberg, as of August 3, 2025.
Conclusion: Recalibrating Valuation Consciousness
The S&P 500’s energy is being pushed by a small group of sectors, primarily tech and financials, boosted by AI-related spending and funding. However beneath the floor, many elements of the actual financial system, like autos, airways, and shopper items, are seeing shrinking margins, and extra unsure earnings. On this context, the index’s headline a number of not displays the typical underlying enterprise.
For traders reconsidering how they construct their portfolios, it might make sense to concentrate on methods which are diversified, valuation-aware, and grounded in fundamentals like regular earnings, stable stability sheets, and the flexibility to carry up in harder situations.
Comeback of the Buck?
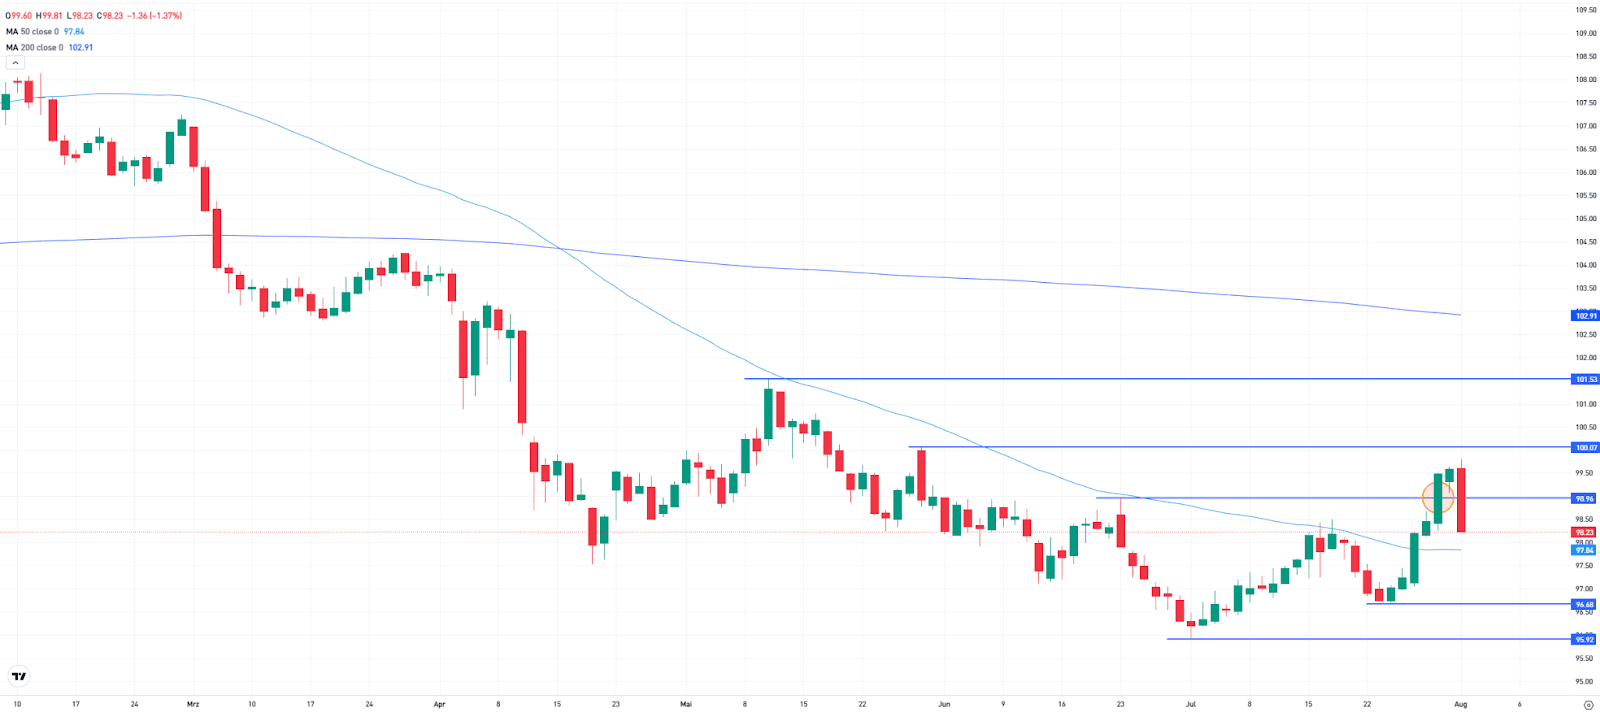
The U.S. Greenback Index ended final week with a achieve of 1.0%, closing at 96.68. At its peak in the course of the week, the greenback was up as a lot as 2.6%. Nonetheless, Friday’s lengthy pink candlestick, within the type of a bearish engulfing sample, signifies that merchants have not too long ago pulled again from the greenback within the quick time period.
Within the medium time period, the breakout above the June 23 excessive at 98.96 could have marked the start of a brand new upward pattern. If the rally continues, the decrease highs from this yr’s earlier downtrend may function potential upside targets: 100.05 and 101.52. Additional above, the long-term 200-day shifting common is situated at 102.91.
The 50-day shifting common may act as key help in case of a deeper pullback. Then again, a decisive break under it may deliver the latest low at 96.67 and the July low at 95.91 again into focus.
U.S. Greenback Index within the each day chart
Key Week for German Q2 Earnings
Infineon: A semiconductor producer enjoying a key position within the vitality transition, digitalization, and e-mobility. Nonetheless, competitors is intense. Market chief TSMC, the producer of Nvidia chips, is adopted by U.S. giants corresponding to Broadcom, AMD, and Qualcomm, in addition to European heavyweights like ASML. Infineon stays closely depending on the automotive sector. With regard to U.S. tariffs, it is going to be notably fascinating to see on Tuesday how the corporate plans to strategically place itself going ahead. The inventory prolonged its losses by 1.8% final week and is at the moment in a correction part.
Siemens Power: World vitality demand is predicted to rise considerably within the coming years because of e-mobility and the AI increase. Siemens Power is effectively positioned to play a key position right here. Strategically, the corporate holds vital applied sciences wanted to help the technical aspect of the vitality transition. Buyers ought to watch carefully on Wednesday how Siemens Power manages its initiatives within the U.S. The corporate plans to start out producing giant industrial energy transformers within the U.S. by 2027. Siemens Power is the third-best DAX performer year-to-date, with the share value practically doubling. Simply final week, it reached a brand new document excessive.
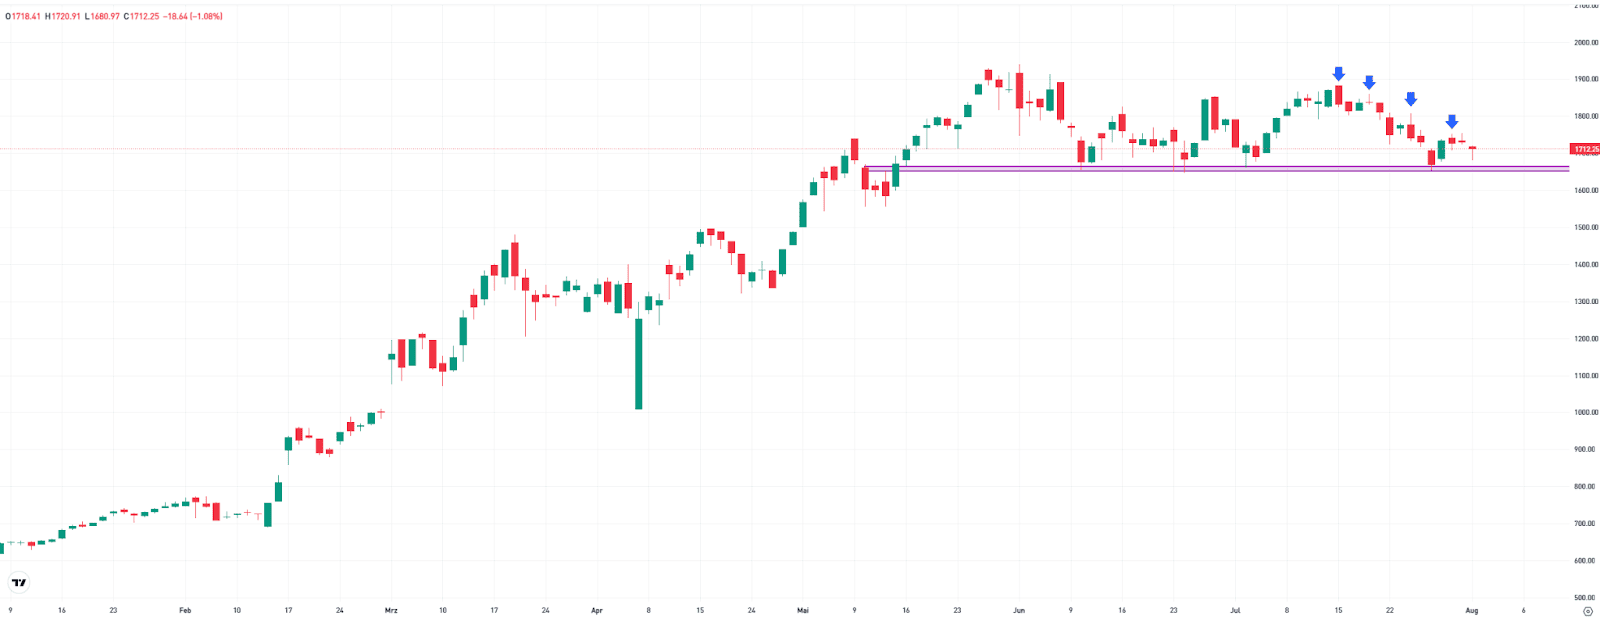
Rheinmetall: Rheinmetall is considerably extra extremely valued than most of its defense-sector friends. This will increase the strain to ship sturdy earnings. As well as, the latest commerce deal between the U.S. and the EU may drawback European protection firms, as billions in EU protection budgets are anticipated to shift towards U.S. merchandise. Regardless of these dangers, the protection increase stays intact. Structural demand continues to help the trade. On Thursday, traders ought to focus particularly on Rheinmetall’s strategic course, order consumption, and any steerage revisions. The inventory is at the moment holding above a key help stage.
Rheinmetall within the weekly chart
Different DAX firms reporting this week:
Siemens (Thursday): Business and automation know-how
Deutsche Telekom (Thursday): Telecommunications and IT companies
Allianz (Thursday): Insurance coverage and asset administration
Munich Re (Friday): Reinsurance and threat administration
This communication is for info and schooling functions solely and shouldn’t be taken as funding recommendation, a private suggestion, or a suggestion of, or solicitation to purchase or promote, any monetary devices. This materials has been ready with out taking into consideration any specific recipient’s funding aims or monetary state of affairs and has not been ready in accordance with the authorized and regulatory necessities to advertise impartial analysis. Any references to previous or future efficiency of a monetary instrument, index or a packaged funding product should not, and shouldn’t be taken as, a dependable indicator of future outcomes. eToro makes no illustration and assumes no legal responsibility as to the accuracy or completeness of the content material of this publication.


