

Analyst Weekly September 15, 2025
From EM tech power to file US buybacks, market drivers are stacking up forward of the Fed’s first price reduce of 2025. With US progress nonetheless uneven and inflation expectations anchored, Powell is anticipated to ship a 25 bp reduce this week, however markets will likely be watching his steerage on the tempo of additional easing simply as intently.
Tech is the New EM Engine
Rising markets (EM) have usually been seen as unstable and onerous to navigate, however the newest earnings season suggests issues could also be turning a nook. Whereas general EM earnings progress was flat in Q2, the breadth of earnings revisions is bettering for the primary time in months, particularly in Asia, because of tech power and supportive coverage strikes.
Semis lead the pack: The standout theme is expertise. Firms tied to the worldwide AI cycle are fueling earnings upgrades. Taiwan and South Korea, each tech-heavy markets, delivered strong revenue progress because of sturdy demand for superior chips. Taiwan’s TSMC and Korea’s SK Hynix are clear beneficiaries, with management in areas like AI accelerators and high-bandwidth reminiscence.
Web shake-up: China’s massive e-commerce companies like Alibaba, JD, and Meituan stay beneath stress from intense competitors, particularly in meals supply and fast commerce. Nevertheless, Alibaba’s cloud and worldwide companies are serving to offset home challenges. In the meantime, ASEAN web companies reminiscent of Seize and Sea are thriving. They’re exhibiting sturdy consumer progress, resilient profitability, and increasing into fintech and digital companies. For traders long-term structural progress in EM, this can be a key theme: the digital economic system is alive and nicely outdoors of China.
Financials Regaining Energy: One other shiny spot is financials. Chinese language banks (like China Retailers Financial institution, Financial institution of China) noticed income rebound in Q2, helped by greater payment revenue. Indian and Brazilian banks additionally reported resilient outcomes, with names like ICICI Financial institution and Itau Unibanco highlighted as well-positioned leaders. Robust capitalization and regular mortgage progress make them standouts in areas which are nonetheless under-owned by world traders. For retail purchasers, this implies the monetary sector, lengthy a spine of EM indices, is regaining relevance as a driver of regular returns.
Watch place sizes & FX Threat: EM strikes might be sharp, pacing publicity helps handle swings– broad EM or Asia ex-Japan ETFs assist clean out country-specific shocks. Pair EM tech/financials with publicity to gold (a basic EM hedge) or developed markets. To get rid of foreign money danger, traders can spend money on a foreign money hedged fairness ETF; exchange-traded foreign money (ETCs); or via CFDs or unfold bets.
Funding Takeaway: Rising markets might look boring on the floor, however momentum is quietly constructing. Tech is flourishing, banks are stabilizing, and coverage assist is boosting home demand. The dreaded “tariff shock” from US commerce coverage has been much less extreme than anticipated, giving exporters some respiration room. AI and tech cycles stay a world resilience issue, serving to offset weak spots like shopper staples. Alternatives are broadening from Taiwan semis to Indian banks to Southeast Asian web platforms. With valuations nonetheless low cost and progress selecting up together with Fed price cuts, EM publicity could possibly be a option to stability portfolios tilted closely towards US mega-caps.
Large Buybacks, Greater Impression
US firms are shopping for again inventory at file ranges in 2025. Practically $1 trillion in buyback bulletins have been made to this point this 12 months, placing 2025 on tempo to surpass final 12 months’s whole. Tech giants are main the way in which; Apple ($100B), Google ($70B), and Nvidia ($60B) all unveiled large buyback applications this earnings season. Large banks like JPM ($50B), GS ($40B), WFC ($40B), and BAC ($40B) have additionally dedicated tens of billions every.
For traders, buybacks matter as a result of they scale back the variety of shares in circulation. That may enhance earnings per share, present worth assist, and sign that administration is assured within the firm’s future. However the exercise is extremely concentrated – a handful of mega-caps characterize about 66% of all buybacks this 12 months. For retail portfolios tilted towards tech and financials, that focus means buybacks might play an outsized position in driving returns.
VIX Slips as Markets Keep Pinned
Volatility retains grinding decrease (14.76), with the VIX sliding as key financial knowledge passes with out sparking main swings. Market focus has shifted extra towards indicators of labor market weak spot than inflation, whereas the backdrop of doable stagflation, slower progress alongside sticky costs, stays a part of the dialog. AI-related shares past the “Magazine 7” have been a shiny spot, serving to sentiment stabilize.
Nonetheless, supplier positioning into month-end suggests rallies are offered into and pullbacks are purchased, conserving the S&P 500 range-bound. As soon as September choices and quarter-end expirations are behind us, the market might commerce extra freely, although company buyback blackouts might take away a layer of assist. With volatility low, some traders are eyeing October as a very good window so as to add safety with methods reminiscent of QQQ put unfold collars – which cap upside in change for cheaper draw back safety – drawing elevated consideration.
South Korean Shares With Dynamic Restoration
The EWY (iShares MSCI South Korea ETF) ended final week with a 7% acquire at 78.66 factors. In the long run, there’s nonetheless catching as much as do in comparison with the U.S. and European inventory markets. The final file excessive was reached on the finish of 2020 at 96.20 factors. The hole has now narrowed to 18%. Within the medium time period, traders have more and more turned again to South Korean shares. Because the low in April, the index has risen 62%, whereas the S&P 500 gained solely 37% over the identical interval. From a technical perspective, EWY might proceed its restoration within the coming weeks and months – at the least so long as the assist zone between 70.96 and 69.59 factors (Honest Worth Hole) holds.
EWY within the weekly chart. Supply: eToro
Cloud Enterprise Triggers a Surge in Oracle Shares
Oracle’s inventory skyrocketed final week, gaining over 25%. Robust cloud offers fueled a large order increase. In only one quarter, a number of multibillion-dollar contracts have been signed, together with with OpenAI, Nvidia, and TikTok. The order backlog surged to $455 billion — greater than 4 instances the earlier 12 months’s stage. On the danger aspect, Oracle faces extraordinarily excessive investments, which put stress on money movement and margins. As well as, there’s a sturdy dependence on just a few main clients.
The market was closely overbought at instances, however situations have since eased considerably. Traders ought to watch the reactions within the two Honest Worth Gaps created by the rally: between $241 and $296, and between $219 and $234. Bullish reversal alerts in these zones might point out {that a} new upward transfer is about to start.
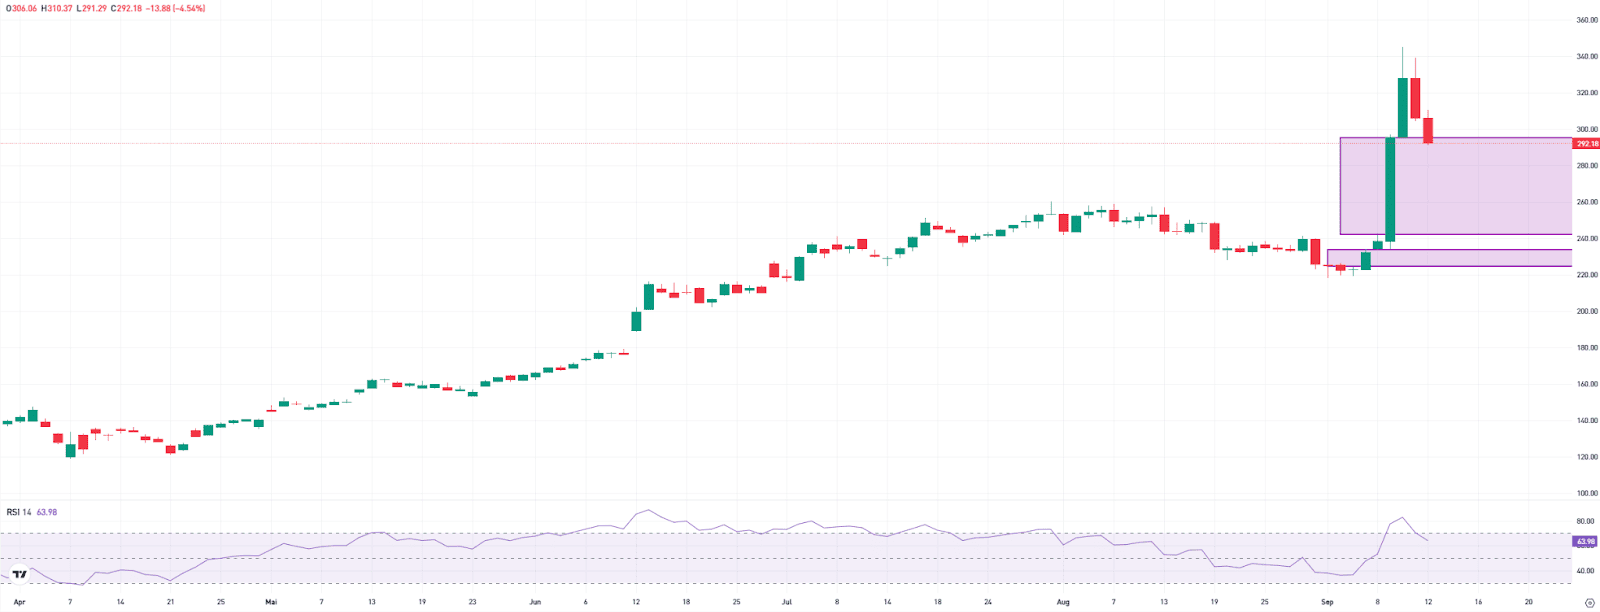
Oracle within the each day chart. Supply: eToro
Macro Calendar: All Eyes on Powell
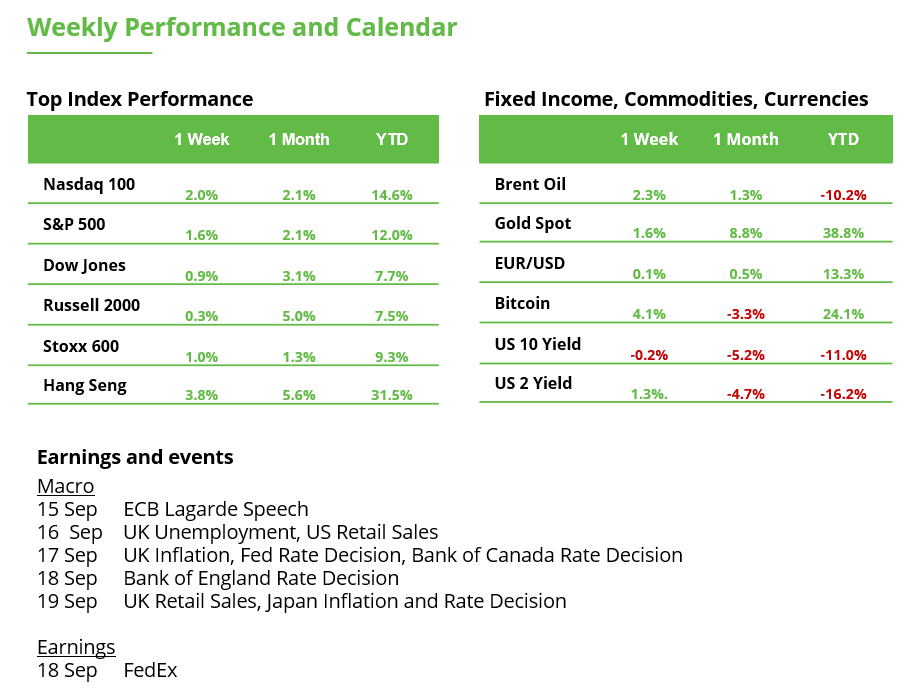
The Fed is anticipated to chop rates of interest on Wednesday for the primary time this 12 months (determination at 8:00 p.m.). Weak point within the labor market offers the Fed the inexperienced mild for a reduce. A small step of 25 foundation factors to a spread of 4.00 to 4.25 p.c is anticipated. By the top of 2026, markets anticipate a complete of six small cuts. Persistently excessive inflation might sluggish this tempo. That’s why the brand new quarterly projections from the central financial institution will likely be decisive. In June, the Fed projected core PCE inflation of two.4% for 2026 and a couple of.1% for 2027. A downward revision would give shares and bonds a lift. As well as, Jerome Powell’s press convention at 8:30 p.m. might present key steerage on what occurs after the September assembly.
This communication is for info and schooling functions solely and shouldn’t be taken as funding recommendation, a private suggestion, or a proposal of, or solicitation to purchase or promote, any monetary devices. This materials has been ready with out bearing in mind any specific recipient’s funding aims or monetary scenario and has not been ready in accordance with the authorized and regulatory necessities to advertise unbiased analysis. Any references to previous or future efficiency of a monetary instrument, index or a packaged funding product usually are not, and shouldn’t be taken as, a dependable indicator of future outcomes. eToro makes no illustration and assumes no legal responsibility as to the accuracy or completeness of the content material of this publication.


