
The Day by day Breakdown takes a better take a look at Palo Alto Networks as shares have misplaced one-third of their worth from the latest highs.
Earlier than we dive in, let’s ensure you’re set to obtain The Day by day Breakdown every morning. To maintain getting our each day insights, all you must do is log in to your eToro account.
Deep Dive
We’ve spent loads of time on the AI-driven selloff in software program — and it’s now spilling into areas like bank card networks, ranking companies, and cybersecurity. The irony is that many bulls view AI as a catalyst for cybersecurity, not a menace. That’s to not say AI can’t introduce new dangers, however it’s a reminder that Wall Road will be short-term and emotional. With that in thoughts, a contemporary take a look at the charts pushed us to take a deeper dive into Palo Alto Networks.
Palo Alto Networks supplies cybersecurity services globally, spanning next-gen firewalls, cloud safety, safe entry, and menace prevention/detection. It additionally sells subscriptions for menace intelligence, malware safety, and knowledge loss prevention, alongside skilled providers, coaching, and assist.
Typically seen as a blue-chip within the house, Palo Alto might not provide the identical top-line development as friends like CrowdStrike, Zscaler, or Fortinet, however it tends to carry stronger financials. The corporate is solidly worthwhile, generates constant free money circulate, and has used that power to take a position for the long run. Most notably, it lately acquired CyberArk — a deal Palo Alto framed as a option to capitalize on key AI-driven tendencies.
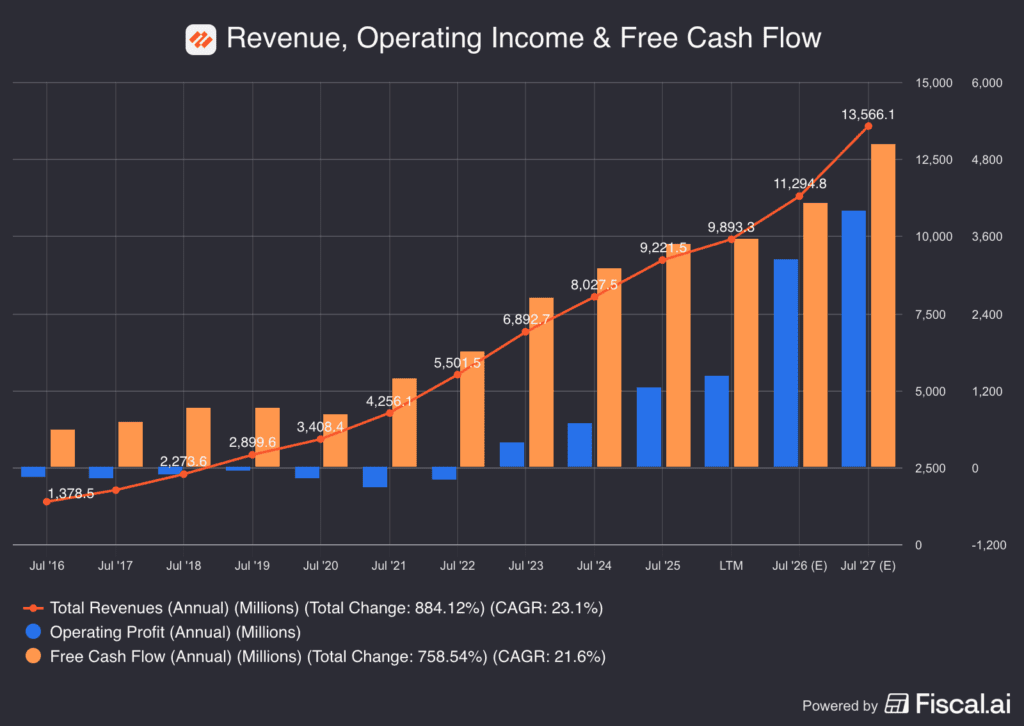
Future Development Projections
The corporate’s fiscal yr ends in July (that means fiscal 2026 ends on July 31, 2026). In accordance with Bloomberg, analysts venture the next:
Earnings Development: 10.8% in 2026, 7.8% in 2027, and 16.8% in 2028
Income Development: 22.2% in 2026, 19.8% in 2027, and 13.7% in 2028
Free Money Circulate Development: 17.4% in 2026, 23.2% in 2027, and 14.4% in 2028
Analysts at the moment have a consensus worth goal of ~$215 on PANW inventory, implying about 44% upside to right now’s inventory worth.
Wish to obtain these insights straight to your inbox?
Enroll right here
Diving Deeper — Valuation
With cybersecurity shares usually richly valued, that alone generally is a hurdle for some buyers. Whereas Palo Alto doesn’t command the nosebleed multiples of some friends, it nonetheless trades at a premium to many extra conventional industries.
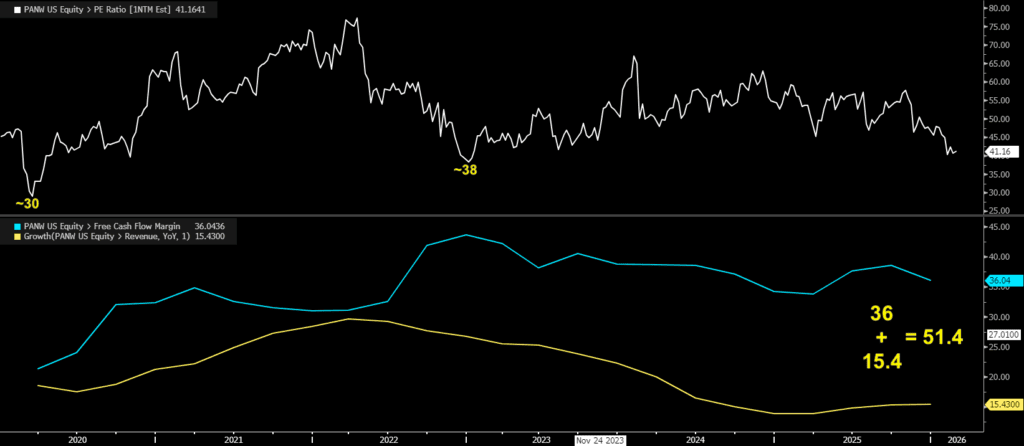
The highest chart exhibits PANW’s ahead P/E ratio, which has fallen to its lowest degree in a number of years. Throughout the 2022 bear market, the a number of bottomed close to 38x, whereas the COVID-19 selloff in 2020 pushed it right down to roughly 30x.
The underside chart highlights free money circulate margin and income development. The “Rule of 40” — a key SaaS (Software program as a Service) metric — says an organization’s income development charge plus its free money circulate margin must be a minimum of 40%. Utilized by buyers to judge firm well being, this components balances fast development with profitability. By that measure, Palo Alto at the moment scores 51.4.
Dangers
There are a number of dangers for Palo Alto — and a few have been on show lately. The largest near-term overhang is AI-disruption concern; even when it proves overblown, the notion alone can strain sentiment and the a number of. Past that, a broader tech selloff may weigh on shares, and intense competitors may gradual development.
The Backside Line
For some buyers, the uncertainty is just too excessive or the valuation nonetheless isn’t compelling. For others, the latest ~30% pullback might appear to be a lovely entry level to begin constructing a place.
Disclaimer:
Please notice that as a consequence of market volatility, a number of the costs might have already been reached and situations performed out.


