
SOFI inventory has been hammered from its highs, but its progress estimates stay promising. The Each day Breakdown digs into the dip.
Concerned about extra Deep Dive content material? Try our newest analysis.
Deep Dive
It’s been a unstable run for SoFi Applied sciences, with shares down nearly 40% to this point this yr. Even so, the inventory continues to be up about 50% over the previous yr and even traded beneath $5 as just lately as Might 2023. So what’s the story behind this roughly $20 billion financial institution?
SoFi Applied sciences is a digital monetary companies firm that gives banking, lending, investing, and different money-management merchandise by way of a single app. It positions itself as a one-stop platform geared toward serving to members borrow, save, spend, make investments, and defend their cash.
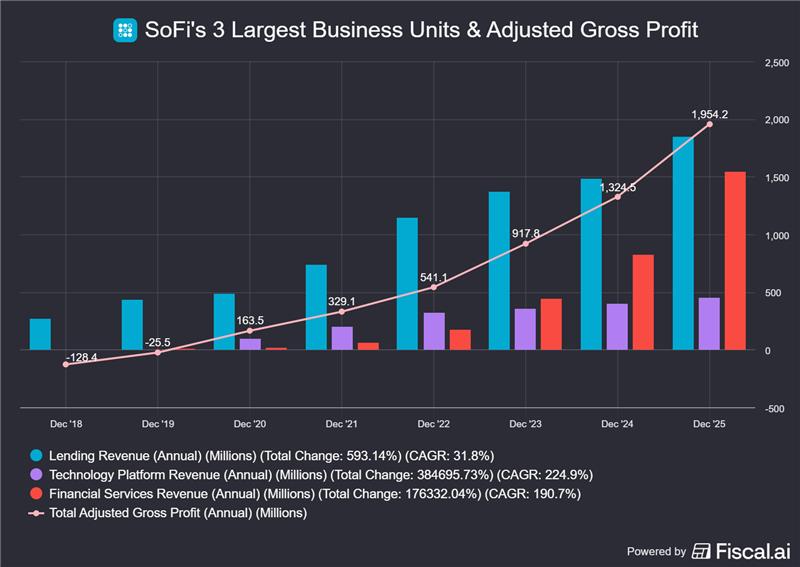
When SoFi started buying and selling publicly in 2020, the inventory opened round $11 earlier than rapidly climbing into a large buying and selling vary of roughly $14 to $24. The following bear market then dragged shares into the one digits, with the inventory falling as little as $4.24. Regardless of that volatility, the enterprise has continued to develop. As proven above, SoFi’s three largest companies have expanded every year, whereas whole adjusted gross revenue has additionally continued to climb.
Future Development Projections
So far as analysts are involved, that progress ought to proceed into the longer term, too. In response to Bloomberg, analysts venture the next:
Earnings Development: 56% in 2026, 32% in 2027, and 23.5% in 2028
Income Development: 30.1% in 2026, 21.3% in 2027, and 13.9% in 2028
Analysts presently have a consensus value goal of ~$23.88 on SOFI inventory, implying about 47% upside to as we speak’s inventory value.
Need to obtain these insights straight to your inbox?
Join right here
Diving Deeper — Valuation
Valuing youthful corporations with robust progress may be tough. In SoFi’s case, although, that progress has helped make the valuation extra cheap:
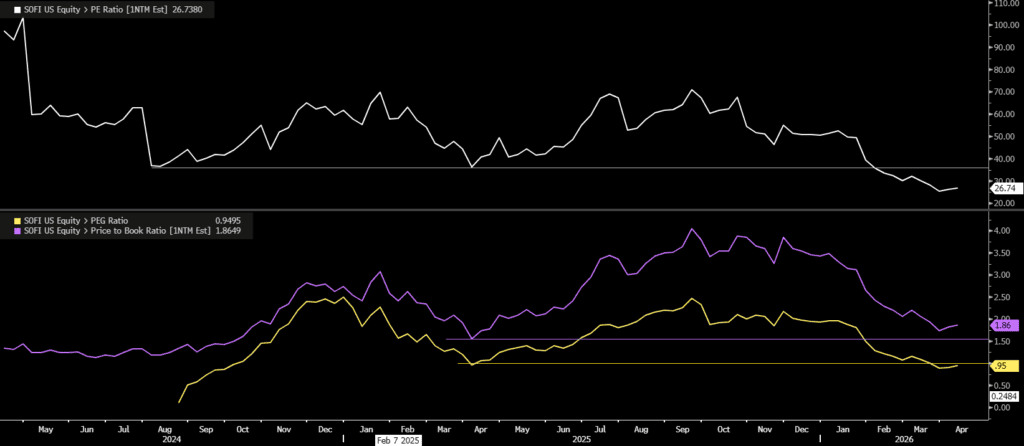
The ahead P/E ratio is now close to a multi-year low of roughly 26.5x, whereas the price-to-book ratio — a standard measure for financial institution shares — is beneath 2x and close to the 2025 low, (though the inventory value is up about 90% from that interval).
Lastly, SoFi’s PEG ratio — which measures valuation relative to anticipated earnings progress — is again beneath 1.0. A typical rule of thumb is {that a} PEG ratio round 1.0 suggests a inventory is pretty valued, beneath 1.0 could point out undervaluation, and above 1.0 can suggest the inventory is pricey relative to its progress.
Dangers
A few of SoFi’s major company-specific dangers embody its heavy publicity to non-public lending and credit score efficiency, reliance on deposits and capital-markets funding to help mortgage progress, and regulatory and compliance threat tied to working a nationwide financial institution. Elements of the enterprise, significantly pupil lending, are additionally delicate to rates of interest and authorities coverage. Like all banks and lenders, SoFi would additionally face broader recession threat, together with weaker mortgage demand and better credit score losses.
The Backside Line
The bull case is that SoFi continues to be rising, its ecosystem is maturing, and after such a steep drop from the highs, the valuation is much simpler to abdomen. The bear case is that that is nonetheless a shopper lender and financial institution dealing with credit score, recession, funding, and regulatory dangers. So whereas the selloff has helped de-risk the inventory, buyers nonetheless want confidence that progress can outweigh these headwinds.
Disclaimer:
Please word that attributable to market volatility, among the costs could have already been reached and situations performed out.


