
The Every day Breakdown dives into ServiceNow, which regardless of beating on earnings, tumbled after its report and weighed on software program shares.
Focused on extra Deep Dive content material? Try our newest analysis.
Deep Dive
Simply when it seemed just like the worst could also be behind it, shares of ServiceNow tumbled 17.6% on Thursday. Regardless of beating earnings and income estimates and elevating full-year steering, traders punished the inventory amid ongoing issues that its moat could possibly be eroded by AI. That worry isn’t distinctive to ServiceNow — the broader software program area pulled again on Thursday, with many names nonetheless nicely under their 52-week highs even because the Nasdaq 100 has returned to document highs. So what’s the deal?
ServiceNow sells cloud software program that helps enterprises digitize and automate workflows throughout IT, customer support, HR, safety, and different back-office features by means of its Now Platform. It’s more and more embedding AI into that platform by means of Now Help and newer AI brokers, which might energy search, summaries, suggestions, conversational help, and extra autonomous activity execution inside present workflows.
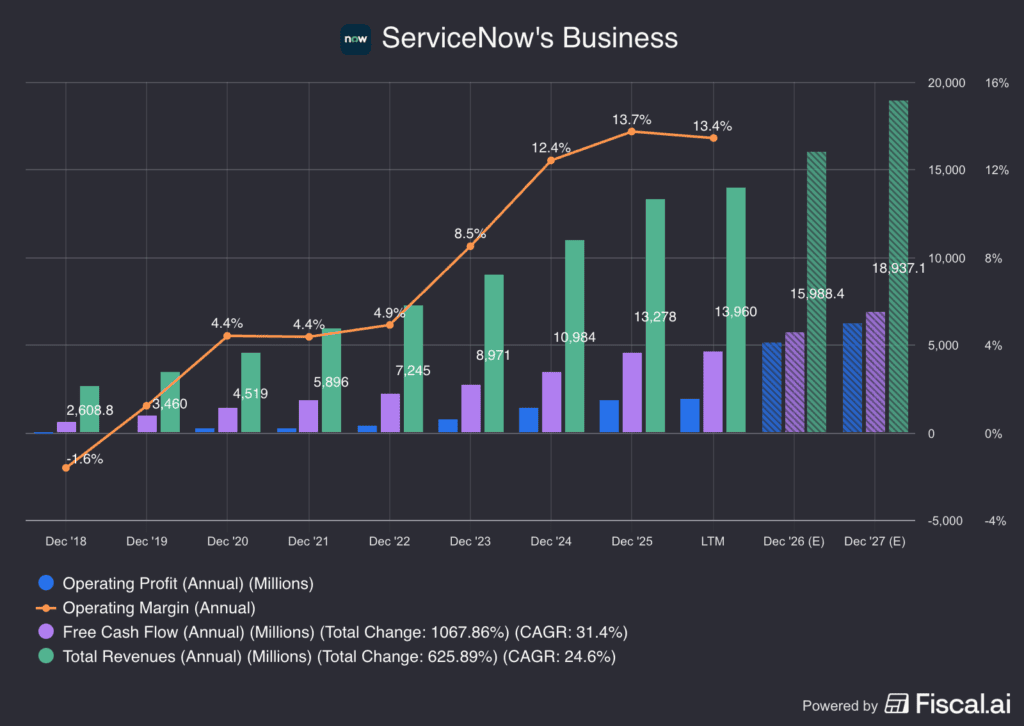
Regardless of the noise, ServiceNow continues to ship stable development, with income, working earnings, free money circulate, and margins all transferring in the proper route.
Future Development Projections
Even with the corporate’s robust monitor document and spectacular development expectations over the subsequent a number of years, traders stay uneasy in regards to the potential disruption from AI. It creates a basic Wall Avenue conundrum: Is that this merely an overreaction to an unfounded worry, or are sellers accurately getting forward of a long-term drawback?
In keeping with Bloomberg, analysts challenge the next:
Earnings Development: 19.3% in 2026, 20.1% in 2027, and 18.7% in 2028
Income Development: 20.9% in 2026, 21.6% in 2027, and 18.3% in 2028
Analysts presently have a consensus value goal of ~$149 on NOW inventory, implying about 74% upside to right now’s inventory value.
Wish to obtain these insights straight to your inbox?
Join right here
Diving Deeper — Valuation
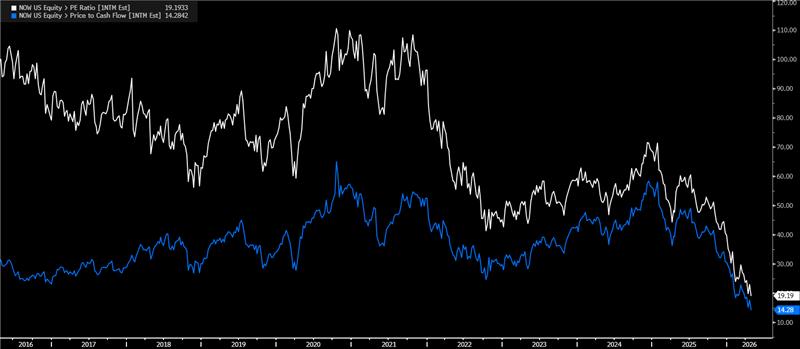
As a result of ServiceNow’s enterprise continues to develop whereas the inventory continues to fall, the valuation has change into way more approachable. The truth is, on each a price-to-earnings and price-to-free-cash-flow foundation, it has by no means been decrease:
Dangers
In Q1, we took a Deep Dive into software program shares and mentioned the affect AI is having on the group. Whereas many of those corporations could have defensible moats — and whereas many could finally profit from AI — one of many greatest dangers is valuation compression. Put one other manner, a significant re-rating throughout the trade can weigh on inventory costs even when the underlying companies are nonetheless performing fairly nicely.
ServiceNow can also be not insulated from broader financial or macro-related pressures. Working example: the corporate mentioned geopolitical turmoil within the Center East delayed a number of giant on-premise offers in Q1. Whereas a few of these offers have since closed within the first few weeks of Q2, the disruption delayed roughly $200 million in income final quarter.
The Backside Line
ServiceNow’s underlying enterprise continues to indicate stable development, and the inventory’s valuation has change into notably extra affordable after a steep decline of roughly 50% over the previous 12 months. On the similar time, bettering valuation and powerful fundamentals alone don’t assure the inventory has bottomed, notably as traders proceed to weigh AI-related disruption danger, broader software program re-rating pressures, and macro uncertainty.
Disclaimer:
Please notice that as a consequence of market volatility, among the costs could have already been reached and eventualities performed out.


