

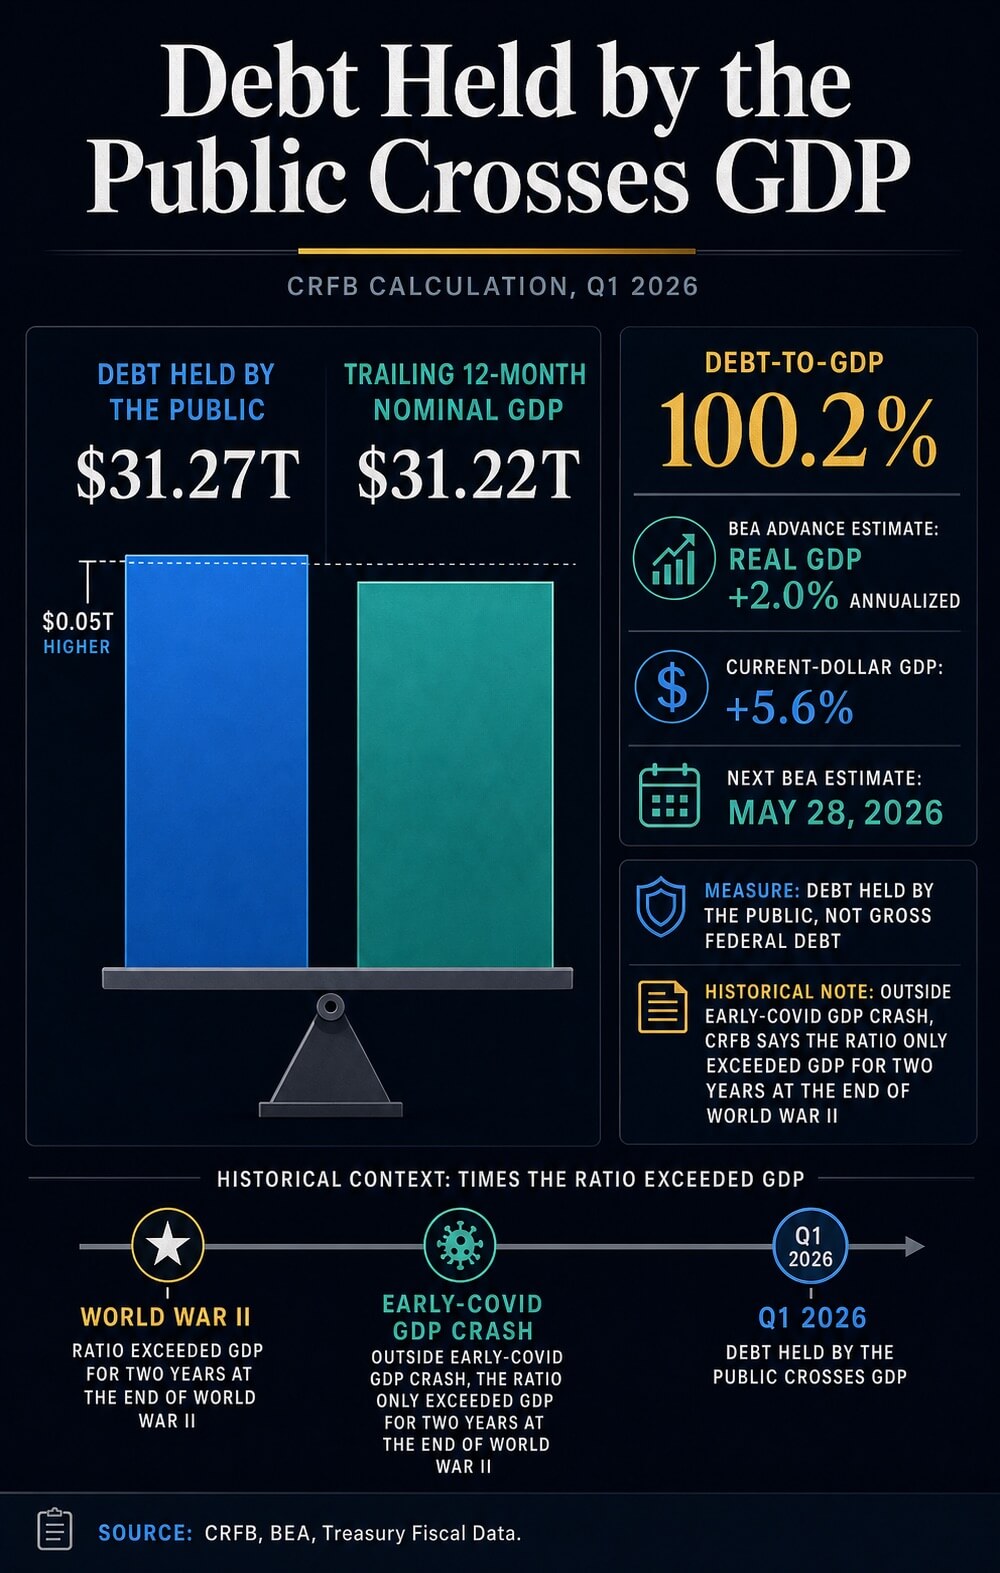
U.S. public debt has crossed the scale of the U.S. financial system on a calculation from the Committee for a Accountable Federal Finances, giving Bitcoin’s hard-money case a dwell fiscal benchmark as buyers weigh scarce belongings towards Washington’s debt path.
CRFB stated debt held by the general public reached $31.27 trillion on the finish of the primary quarter of 2026, in contrast with $31.22 trillion of trailing 12-month nominal GDP. That places the ratio at 100.2%, utilizing the Bureau of Financial Evaluation advance estimate for first-quarter output.
For Bitcoin, the brink turns an summary shortage argument right into a present macro query: whether or not a fixed-supply, non-sovereign asset turns into extra engaging when confidence in sovereign stability sheets weakens. Debt is the narrative enter. Liquidity, charges, ETF demand, and threat urge for food are the transmission mechanism.
The transfer above 100% of GDP strengthens the case buyers could make for Bitcoin as scarce financial insurance coverage. It nonetheless leaves open whether or not these buyers will add publicity whereas Treasury yields, reserve circumstances, and volatility maintain setting the value of threat.
What the debt threshold modifications
CRFB’s calculation makes use of debt held by the general public, the federal debt owed to outdoors buyers and different non-government holders. That measure carries a special market which means than complete public debt excellent, which additionally contains intragovernmental holdings.
That distinction is important as a result of the Bitcoin comparability works provided that the fiscal metric is obvious. Treasury’s Debt to the Penny knowledge, together with its March 31 API report, separates debt held by the general public from intragovernmental holdings and complete public debt excellent.
The peg sits on the public-debt measure, fairly than the bigger figures usually utilized in political debate.
CRFB additionally positioned the brink in historic context. Outdoors the temporary early-COVID GDP crash, it stated debt solely exceeded GDP for 2 years on the finish of World Battle II.
A debt ratio close to wartime extremes modifications the language buyers use round fiscal credibility, even when the U.S. Treasury market stays the middle of world collateral.
The GDP aspect of the ratio additionally wants care. BEA’s first-quarter launch was an advance estimate.
It confirmed actual GDP rising at a 2.0% annualized tempo and current-dollar GDP rising 5.6%, however the subsequent estimate is scheduled for Could 28. Which means the precise ratio can transfer.
The fiscal sign remains to be clear sufficient for market debate, whereas the exact denominator stays provisional.
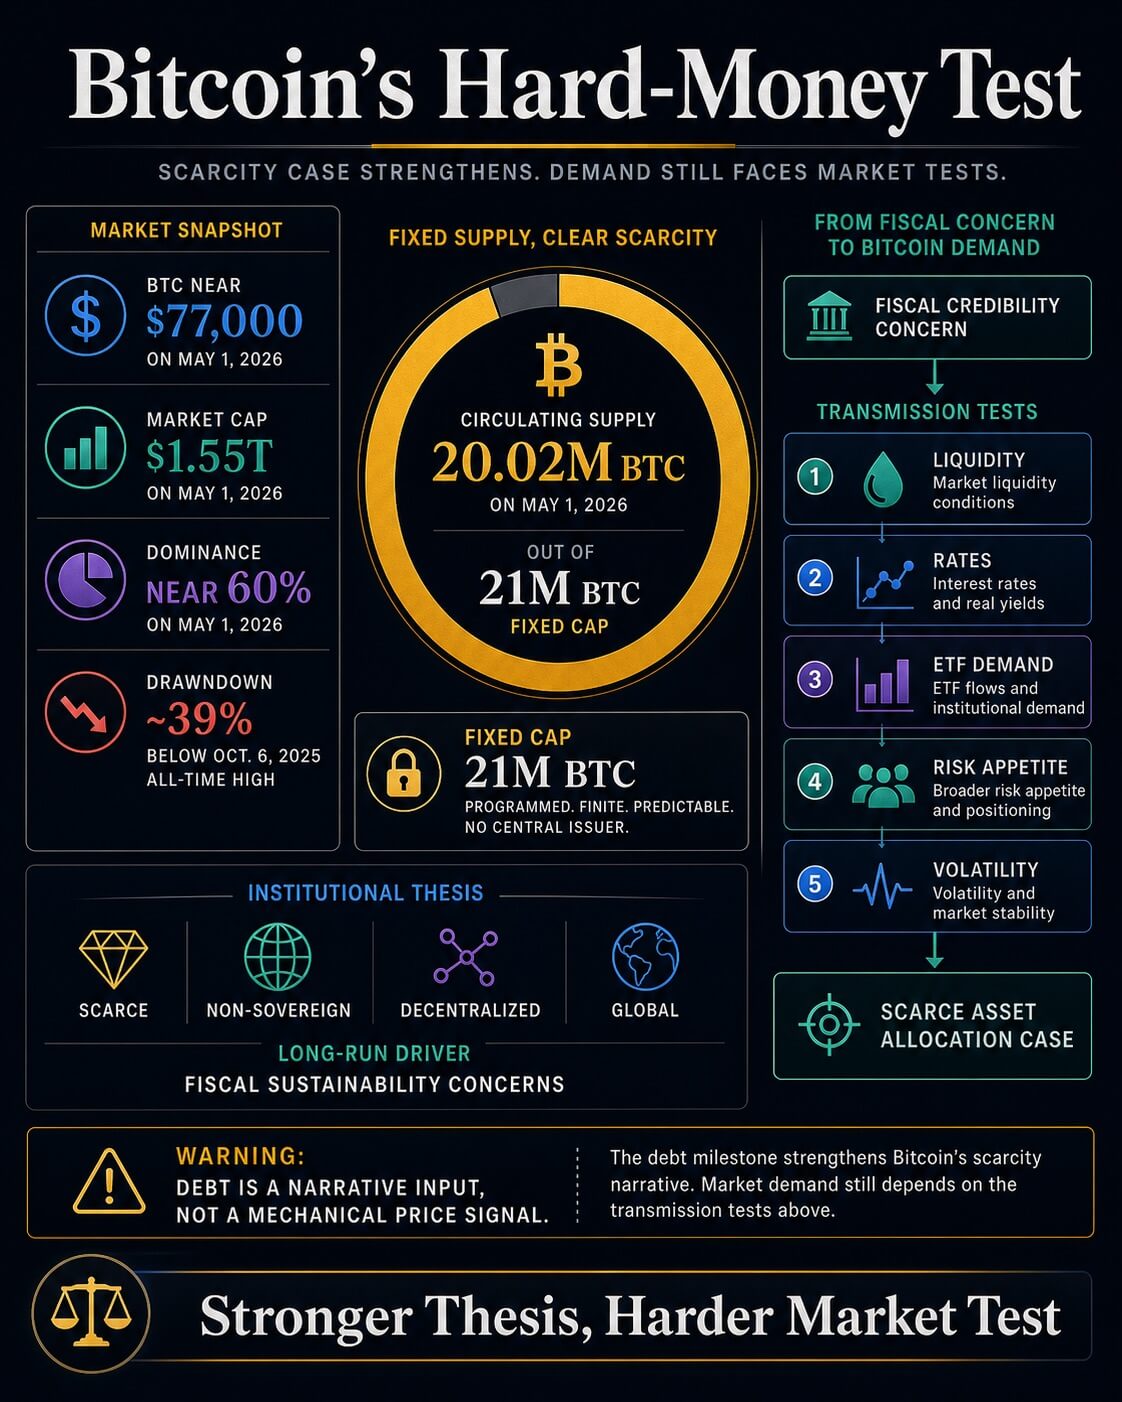
Bitcoin enters this dialogue as a result of its provide schedule gives a distinction with fiscal enlargement. CryptoSlate’s Bitcoin market web page confirmed about 20.02 million BTC circulating on Could 1, 2026, towards a most provide of 21 million.
That mounted cap is the core financial distinction with a fiscal system that may subject extra debt.
BlackRock has given the institutional model of that argument. In its Bitcoin diversifier paper, the asset supervisor described Bitcoin as scarce, non-sovereign, decentralized, and international.
It additionally stated long-term adoption could possibly be formed by considerations over financial stability, geopolitical stability, U.S. fiscal sustainability, and U.S. political stability.
That fiscal language places CRFB’s debt marker inside Bitcoin’s funding case. Allocators now have a present U.S. reference level for a thesis that may in any other case sound summary.
The argument is easy: if sovereign debt retains rising quicker than the financial system, a credibly scarce settlement asset earns extra consideration within the debate over financial hedges.
CryptoSlate’s broader market dashboard and Bitcoin web page present BTC close to $77,000 on Could 1, with a market cap of round $1.55 trillion, dominance close to 60%, and a value roughly 39% beneath its Oct. 6, 2025, all-time excessive.
A shortage asset can nonetheless commerce like a threat asset when liquidity tightens.
Liquidity nonetheless decides the transmission
Current CryptoSlate protection reveals why the debt milestone needs to be separated from near-term value habits. A debt-and-liquidity evaluation argued that U.S. debt development, Treasury issuance, reserve balances, and bank-credit circumstances can tighten the plumbing that strikes liquidity into threat belongings, even when broad cash is increasing.
That view is essential for Bitcoin as a result of the asset sits on the intersection of two completely different trades. In the long term, it may be purchased as financial insurance coverage towards fiscal and foreign money threat.
Within the medium time period, it nonetheless responds to the price of capital, leverage, ETF flows, and the extent of yields obtainable on Treasuries.
A separate CryptoSlate piece on Treasury yields and Bitcoin liquidity made the identical level by the charges channel. Greater long-end yields elevate the hurdle for belongings with no coupon or dividend.
Bitcoin can have a stronger financial narrative whereas nonetheless going through a harder comparability towards Treasury earnings.
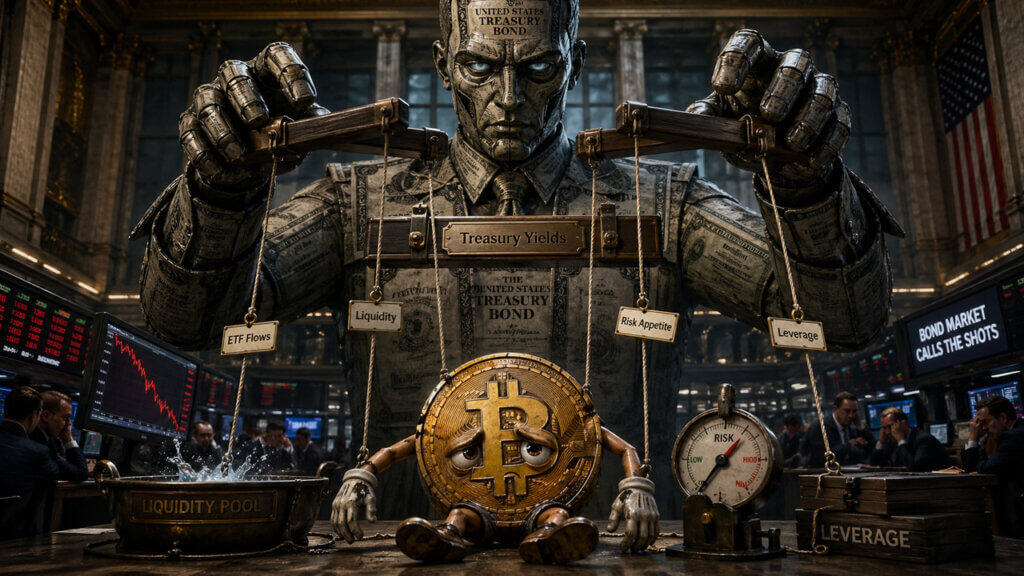
The result’s a two-layer market. The debt-to-GDP break improves the macro setup for Bitcoin.
The funding setting decides whether or not that setup turns into precise demand. Buyers utilizing the milestone as a value sign want proof from flows, yields, reserves, and volatility earlier than the allocation case turns into greater than a story improve.
Proof layerWhat it supportsWhat stays openCRFB debt-to-GDP markerPublic debt has crossed GDP on CRFB’s calculation, reviving a World Battle II-era comparability.The precise ratio can shift as GDP estimates revise.CBO baselineDebt held by the general public is projected to rise from 101% of GDP in 2026 to 120% in 2036.Sooner nominal GDP development or coverage modifications may alter the trail.BlackRock Bitcoin thesisFiscal sustainability considerations match the institutional case for a scarce, non-sovereign asset.Adoption logic and short-term value habits stay separate assessments.CryptoSlate market contextBTC nonetheless trades with liquidity, yields, ETF demand, and volatility in view.A debt milestone alone leaves circulation affirmation unresolved.
Two paths for the thesis
The Congressional Finances Workplace’s February outlook retains the fiscal stress in view. It initiatives debt held by the general public rising from 101% of GDP in 2026 to 120% in 2036, above the 106% excessive recorded in 1946.
It additionally initiatives wider deficits, with rising web curiosity prices driving a lot of the rise.
That path offers Bitcoin’s hard-money thesis a sturdy macro backdrop. If deficits keep massive, curiosity prices rise, and buyers develop into extra delicate to the provision of Treasuries, demand for belongings outdoors sovereign issuance can develop.
In that situation, the debt milestone turns into an emblem of the constraint Bitcoin was designed to sit down outdoors.
CBO’s personal uncertainty work provides the wanted restraint. In a February follow-up on how outcomes may differ from its baseline, CBO stated financial and budgetary outcomes may land above or beneath its central estimate, together with underneath paths with quicker nominal GDP development.
The fiscal trajectory is critical, however it’s nonetheless a forecast path fairly than a settled vacation spot.
CryptoSlate’s prior protection has been constructing towards the identical take a look at from different angles. A February evaluation of the decade-long debt path framed the difficulty by time period premium, greenback vulnerability, and Bitcoin’s hard-asset function.
A November piece measured U.S. debt in BTC phrases, exhibiting how rapidly fiscal enlargement can overwhelm Bitcoin’s issuance schedule. CRFB’s new marker modifications the timing: the ratio has crossed the brink now.
That leaves Bitcoin with two seemingly outcomes. Within the constructive model, inflation cools, reserve circumstances enhance, Treasury provide turns into simpler to soak up, and the debt milestone strengthens the case for a modest allocation to scarce financial belongings.
Within the restrictive model, issuance stays heavy, yields stay elevated, and Bitcoin retains buying and selling as a high-beta liquidity asset regardless of the stronger long-run narrative.
U.S. public debt crossing GDP offers Bitcoin’s shortage thesis a sharper macro anchor.
It helps the argument that some buyers will maintain in search of non-sovereign financial belongings as fiscal ratios worsen. It leaves the more durable market proof forward: whether or not liquidity, charges, and flows align sufficient for that thesis to develop into sturdy demand fairly than one other macro slogan.


