


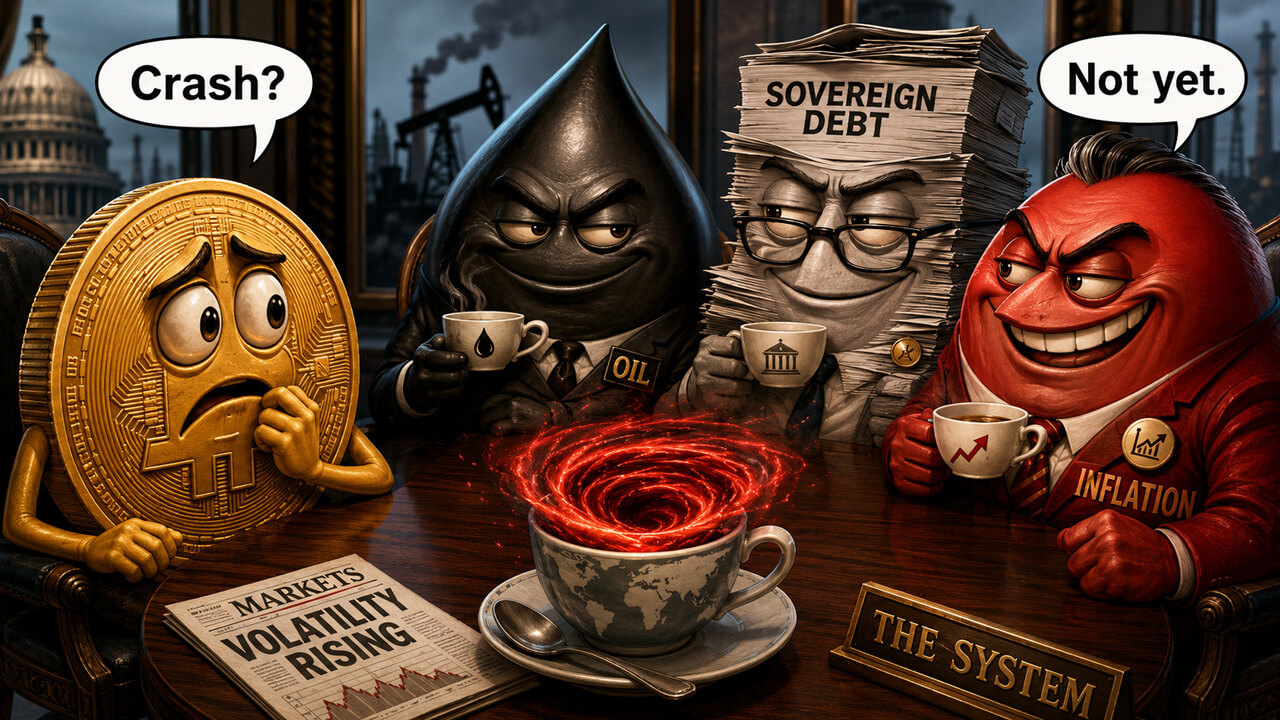
Is a world 2008-style financial crash nigh? And do present circumstances resemble the early phases of a broader international monetary disaster pushed by debt prices, inflation stress, and constrained coverage responses?
These questions have change into more durable to dismiss as a result of the stress factors are stacking within the fallacious order: excessive sovereign yields, excessive public debt, an vitality shock, sticky inflation, and stretched asset valuations.
The world has echoes of 2008, however the coverage setting is totally different. Banks are higher capitalized than they had been earlier than the worldwide monetary disaster, and the Federal Reserve’s newest financial-stability work nonetheless factors to areas of resilience in family and financial institution stability sheets.
Any 2020 analogy additionally breaks down: governments and central banks might then flood the system with assist whereas inflation was muted.
The setup is totally different as a result of the rescue tradeoff is dearer. International public debt stood at slightly below 94% of GDP in 2025 and is projected to achieve 100% by 2029 within the IMF’s April Fiscal Monitor.
The World Financial institution is warning that the Center East conflict can push vitality, meals, fertilizer, and inflation larger. The Monetary Stability Board has flagged sovereign bond markets, asset valuations, and personal credit score as areas that want shut monitoring.
The result’s a reputable, affordable worst case, with inevitability nonetheless outdoors the proof.
Sovereign yields return to international monetary disaster warning ranges
[Editor’s Note: Intraday volatility was extremely high today, May 13. Snapshot used for this article was taken around 14.00 UTC]
The bond market is the place the query begins. Intraday government-bond knowledge as we speak, Might 13, confirmed U.S. Treasurys at roughly 3.99%, 4.46%, and 5.03% throughout the 2-year, 10-year, and 30-year tenors.
U.Okay. gilts had been round 4.53%, 5.10%, and 5.78%. German Bunds had been close to 2.71%, 3.11%, and three.63%. Japanese authorities bonds sat at round 1.40%, 2.59%, and three.82%.
The historic comparability is vital right here. Nasdaq beforehand marked U.S. 2-year yields on the highest since 2007, after they reached 4%.
U.Okay. 2-year gilts are on the highest ranges since June 2008, whereas U.Okay. 10-year yields are close to 18-year highs, and 30-year gilts are close to ranges related to 1998.
Germany’s 10-year Bund is near its highest stage since Might 2011, throughout the eurozone debt disaster. Japan’s 10-year yield has reached ranges final seen in 1997, with the 2-year yield at ranges final seen in 1995.
China is the exception. Its 10-year authorities bond yield was round 1.74% on Might 13, with the 2-year close to 1.27% and the 30-year close to 2.24%, in accordance with Buying and selling Economics.
That curve factors to a distinct progress and worth backdrop, splitting the story into high-yield stress in developed markets and low-yield progress stress in China.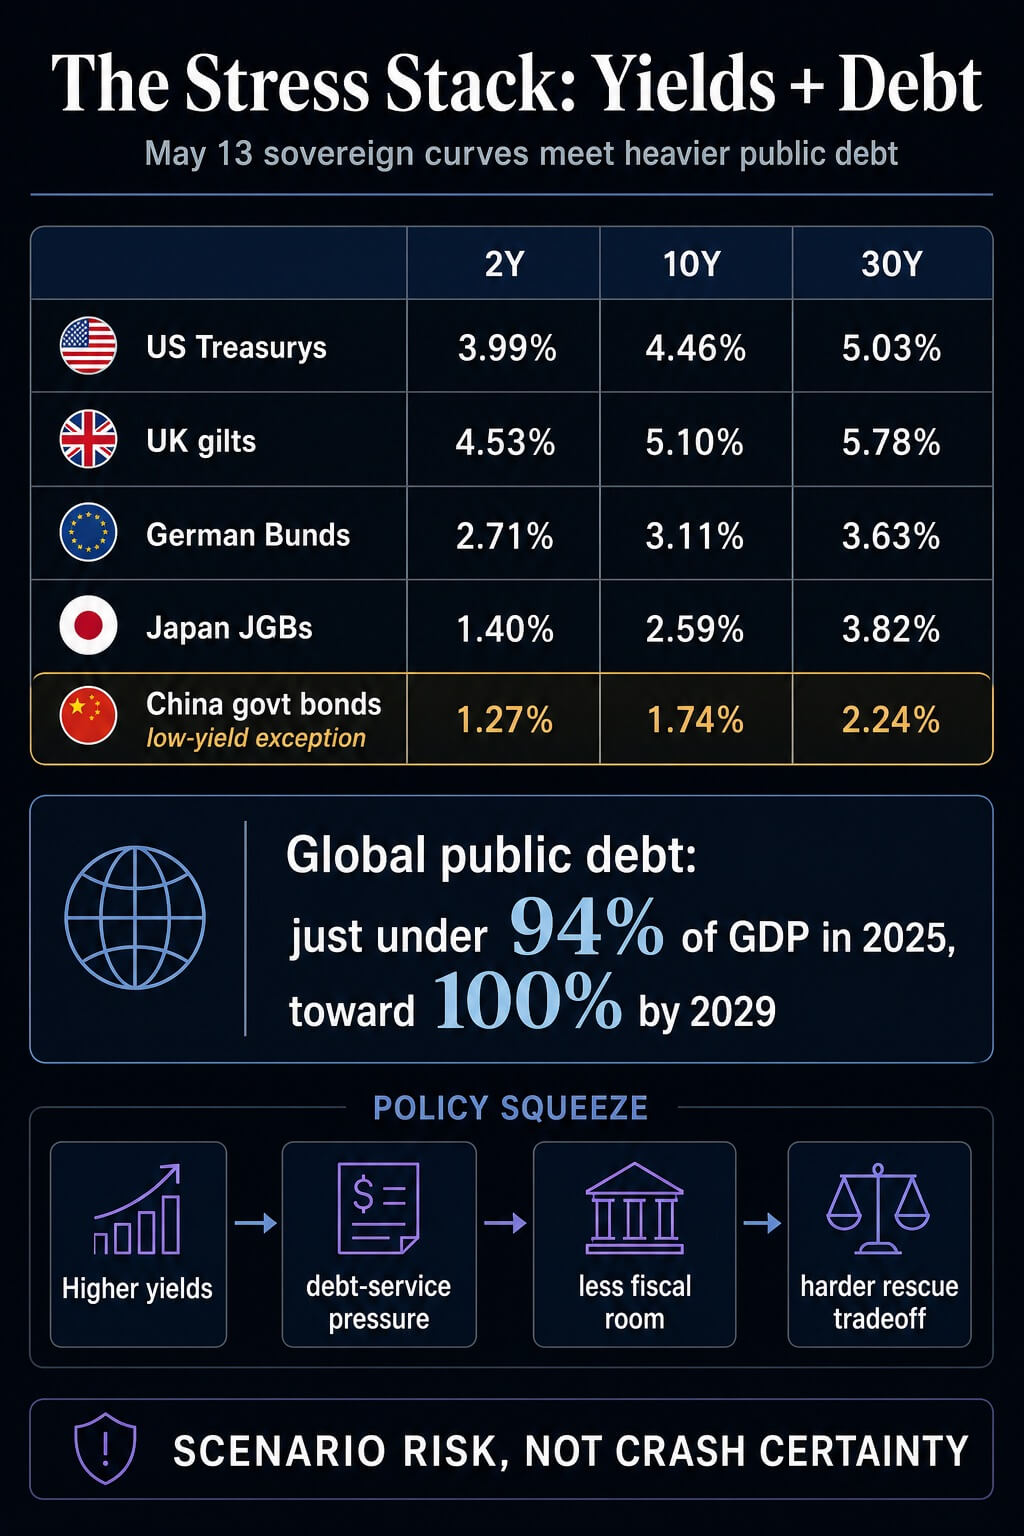
The developed-market facet nonetheless carries the larger fiscal drawback. The OECD’s 2026 debt work reveals heavy sovereign borrowing and refinancing wants throughout its member economies.
Greater yields roll into auctions, coupon prices, and political decisions over time. The longer the lengthy finish stays elevated, the extra the market forces governments to decide on between larger curiosity payments, lowered spending flexibility, and bigger deficits.
In 2008, aggressive financial rescue and balance-sheet assist helped stabilize the monetary system. In 2020, fiscal and financial enlargement bridged a sudden collapse in exercise.
In 2026, the debt inventory is greater, long-end yields are larger, inflation danger is seen, and an vitality shock is already inside the info.
Hormuz turns oil danger into coverage danger
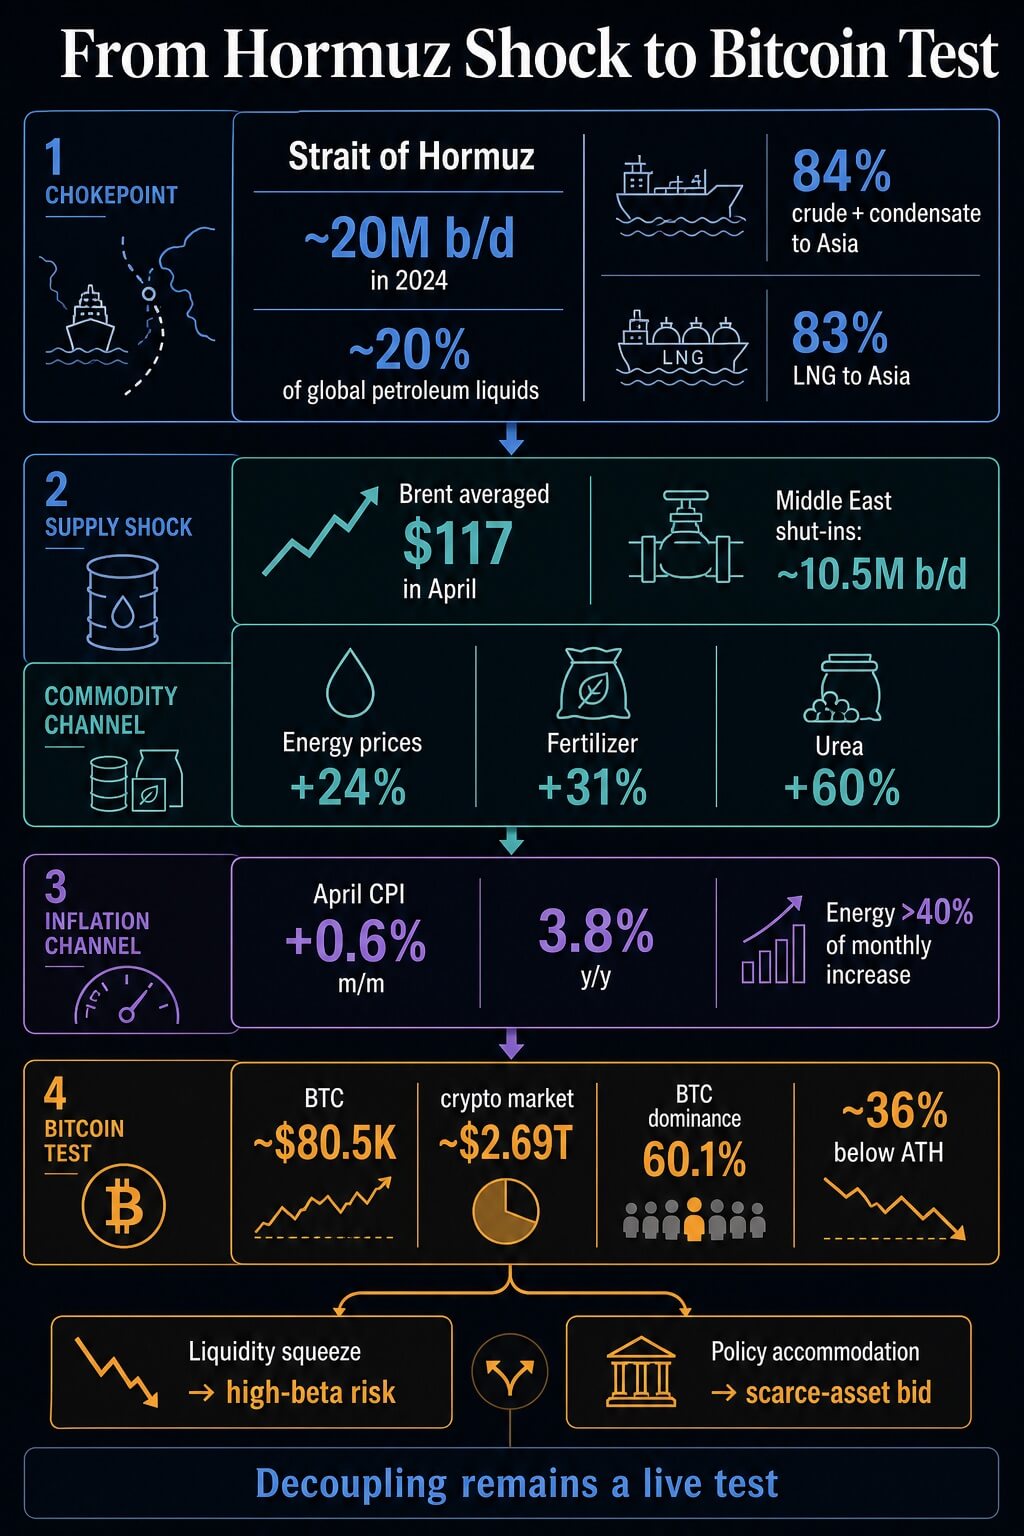
The Strait of Hormuz is the principle stress level as a result of it turns a regional battle into a world value shock. The U.S. Power Data Administration estimates that roughly 20 million barrels per day moved by the strait in 2024, equal to about 20% of worldwide petroleum liquids consumption.
The company additionally estimated that 84% of crude oil and condensate and 83% of LNG shifting by Hormuz went to Asian markets that yr.
The present shock has moved into official worth and provide forecasts. In its Might 2026 Brief-Time period Power Outlook, the EIA described Hormuz as successfully closed to transport visitors, mentioned Brent averaged $117 per barrel in April, and assessed Center East manufacturing shut-ins round 10.5 million barrels per day that month.
The company assumes flows start to renew from late Might or early June, however that assumption is itself one of many stay danger variables.
The World Financial institution’s April Commodity Markets Outlook places the macro channel in plain phrases. Power costs are projected to surge 24% this yr, Brent is forecast at $86 per barrel within the baseline, and a severe-disruption situation might push Brent as excessive as $115.
Fertilizer costs are projected to rise 31%, pushed by a 60% bounce in urea. The identical report warns that larger commodity costs will raise inflation and weaken progress, particularly in growing economies that have already got restricted fiscal buffers.
The U.S. knowledge already present a part of that pass-through. The Bureau of Labor Statistics mentioned April CPI rose 0.6% on a seasonally adjusted month-to-month foundation and three.8% over the yr earlier than seasonal adjustment.
Power accounted for greater than 40% of the month-to-month enhance.
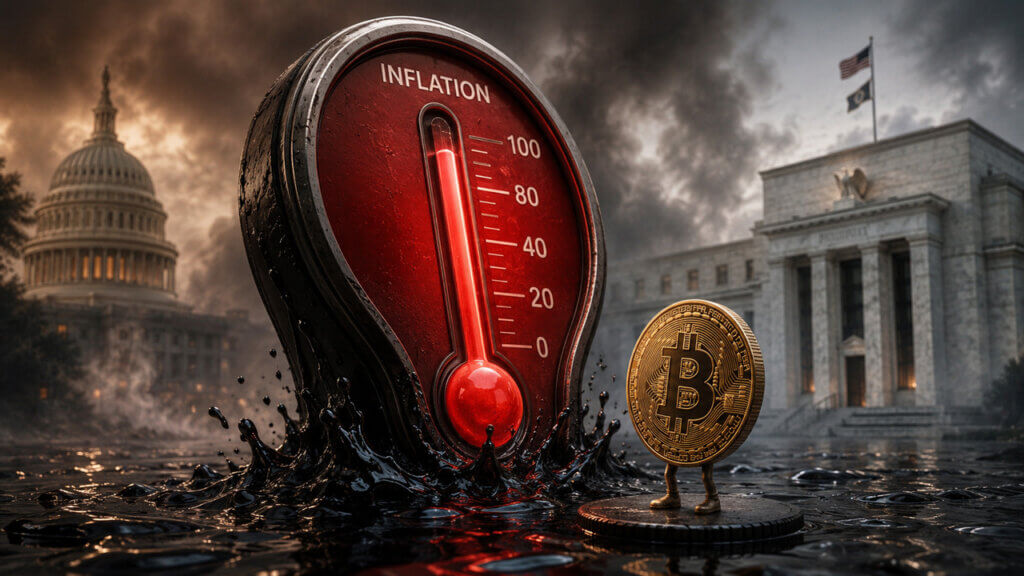
That’s the mechanism that makes the crash query credible. A shorter shock can nonetheless maintain inflation expectations agency sufficient to sluggish price cuts whereas debt-service prices proceed to climb.
If progress weakens on the similar time, the coverage alternative turns into ugly: defend inflation credibility or defend monetary stability.
TriggerTransmission pathRelease valveHigher sovereign yieldsDebt-service prices rise as governments refinanceDebt maturities stagger the affect over timeHormuz disruptionOil, LNG, fertilizer and transport prices feed inflationRerouting, demand adjustment and resumed flows can soften the primary shockSticky inflationCentral banks have much less room to chop into market stressWeak progress can nonetheless drive lodging laterHigh valuations and leverageRisk property have much less margin for unhealthy newsBank and family stability sheets nonetheless present resilienceBitcoin decoupling testBTC both trades as scarce collateral or high-beta riskRecent divergence is early and nonetheless wants affirmation
Why markets have much less coverage assist than earlier than the worldwide monetary disaster
The equity-market stress is that danger property can look calm even whereas the bond market is repricing the coverage backdrop. The Fed’s Might Monetary Stability Report mentioned ahead fairness price-to-earnings ratios remained within the higher vary of their historic distribution.
Company bond spreads had been nonetheless low by longer-run requirements. Hedge fund leverage remained close to all-time highs and was concentrated among the many largest funds.
That blend is a cushion drawback. The identical Fed report mentioned market contacts most steadily cited geopolitical dangers, an oil shock, personal credit score, and chronic inflation as salient dangers to monetary stability.
The FSB made an identical level in April, saying the Center East battle had already created a considerable international financial shock, with market reactions seen in vitality costs and authorities bond yields.
That’s the collision buyers have to observe throughout coverage conferences, auctions, and liquidity circumstances. Markets can take in excessive charges when progress is robust, inflation is falling, and financial financing seems to be manageable.
They’ll take in oil shocks when central banks can look by the value spike. They’ll take in excessive public debt when borrowing prices are pinned down. The present setup weakens every cushion directly.
A crash turns into an inexpensive worst case if the sequence tightens: Hormuz retains vitality and fertilizer costs excessive; inflation stays sticky; central banks delay assist; long-end yields keep elevated; debt-service stress grows; danger property that had priced a smooth touchdown reprice towards weaker progress and tighter liquidity.
A calmer path can also be doable. If oil flows normalize, inflation eases, actual yields soften, and central banks can pivot towards progress assist, the stress stack breaks earlier than it turns into systemic. That framing is conditional fragility.
That distinction is vital for market timing. Sovereign stress tends to construct by auctions, refinancing calendars, credit score spreads, fairness multiples, and central-bank choices. It not often pronounces itself by one clear set off.
That provides markets time to adapt, however it additionally means stress can maintain accumulating after the primary oil-price spike fades. A soft-landing commerce can survive one shock; the more durable take a look at is whether or not it survives a number of directly, with every channel limiting the coverage reply to the following.
Bitcoin turns into the macro take a look at throughout international monetary disaster fears
Bitcoin sits on the finish of this chain as a result of it’s now a part of the macro learn.
Bitcoin traded round $80,500 on Might 13, earlier than scorching PPI pushed it under $80,000, whereas the broader crypto market stood at round $2.69 trillion, and BTC dominance held at round 60.1%.
That leaves it nonetheless massive sufficient to be a macro asset, whereas its volatility retains it outdoors clean-shelter standing.
Latest CryptoSlate protection has famous home windows when Bitcoin moved otherwise from U.S. equities amid oil, yield, and greenback stress on shares. One other CryptoSlate evaluation framed the Hormuz shock as a fork for Bitcoin: both a liquidity squeeze that drags BTC again into high-beta collateral habits, or a policy-accommodation path that revives the scarce-asset commerce.
That’s the sober option to deal with Bitcoin right here. Bitcoin’s document as a secure inflation hedge stays unproven. Its separation from danger urge for food stays incomplete.
Glassnode’s newest market pulse helps warning: enhancing construction nonetheless wants affirmation amid macro stress from charges, oil, and liquidity.
A single unhealthy fairness session tells little. The take a look at is whether or not Bitcoin can maintain up if shares unload, yields keep excessive, the greenback corporations, and central banks hesitate to ease as a result of inflation remains to be being fed by vitality and meals prices.
If BTC holds that surroundings, the monetary-disorder narrative will get stronger. If it fails, the market could have handled it as one other danger asset with higher branding.
That leaves the crash query with a sensible reply. A 2008 replay stays an out of doors chance, and the declare of inevitability is simply too sturdy.
Nonetheless, the present setup is extra fragile as a result of the general public debt load is heavier, the inflation shock is actual, and the coverage response is extra constrained.
One worth chart will inform solely a part of the story; the coverage alternative will carry the larger sign. If central banks prioritize inflation management whereas oil and debt-service prices maintain rising, monetary markets will face larger stress with no rescue.
In the event that they shift towards monetary stability, Bitcoin faces its clearest take a look at as a hedge in opposition to coverage lodging and currency-credibility danger.
Both manner, the query has moved from alarmism to danger administration. What pulls it again from the brink is that a number of launch valves nonetheless exist:
The shock is conditional. If Hormuz flows resume and oil normalizes, the inflation impulse weakens.Debt stress rolls by time. Refinancing calendars stagger the hit relatively than forcing one speedy rupture.Stability sheets are stronger than 2008. The piece cites resilience in banks and households, which limits direct GFC-style contagion.Central banks nonetheless have optionality. They’re constrained by inflation, however weak progress or market stress can nonetheless drive lodging later.Markets have warning indicators. Auctions, long-end yields, credit score spreads, liquidity, fairness multiples, and BTC’s habits give a sequence to watch.


