


President Donald Trump has pushed the Federal Reserve to revisit one of the crucial contested gateways in US finance, escalating a battle over whether or not crypto and fintech corporations ought to be allowed to attach on to the central financial institution’s cost system.
On Could 19, Trump signed an government order directing the Fed to judge its insurance policies on granting payment-account entry to non-bank monetary corporations, together with corporations concerned in digital belongings, blockchain companies, and different monetary know-how companies.
The order, titled “Integrating Monetary Know-how Innovation into Regulatory Frameworks,” asks federal companies to determine guidelines and supervisory practices that will place pointless limits on monetary innovation.
The directive doesn’t instantly grant crypto corporations entry to the Fed’s cost rails. Nonetheless, it provides the central financial institution a transparent mandate to evaluate whether or not current regulation permits broader entry and, if that’s the case, how the applying course of ought to work.
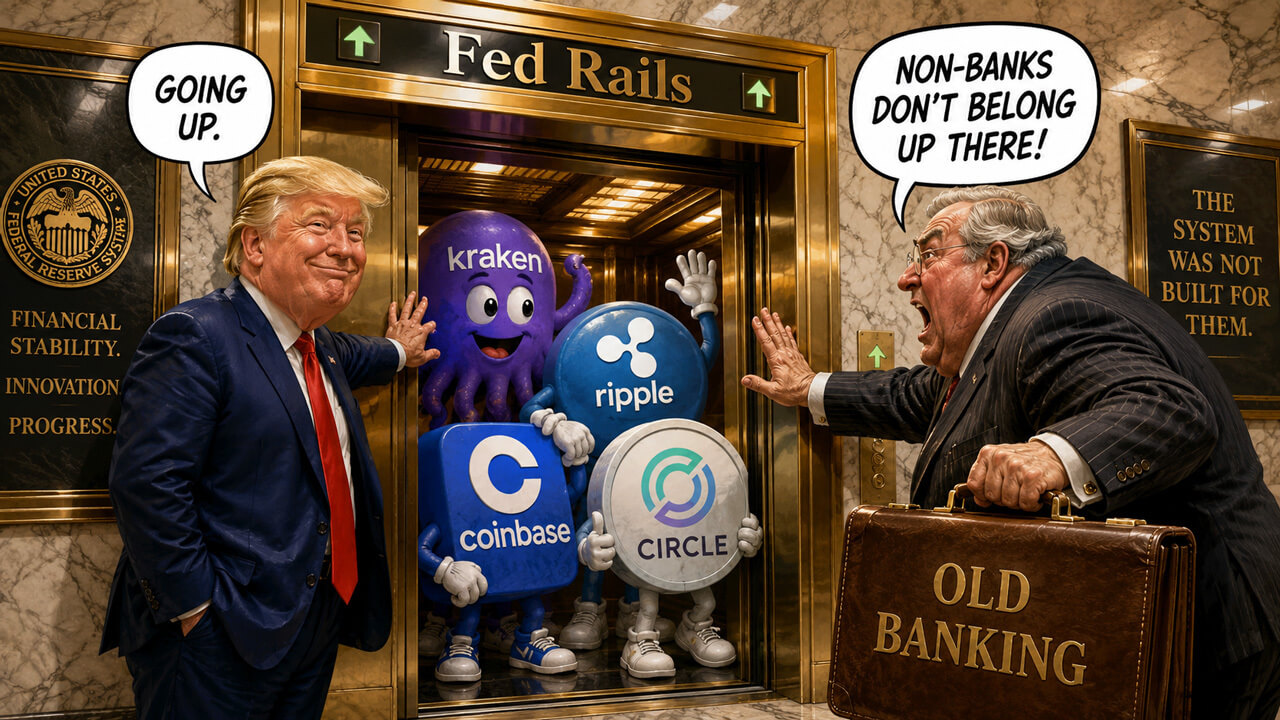
The end result may decide whether or not corporations similar to Kraken, Ripple, Coinbase, Circle, Anchorage, Smart, Paxos, and BitGo can scale back their reliance on middleman banks and transfer nearer to the infrastructure that handles high-value greenback settlement.
Trump order turns grasp accounts right into a White Home precedence
On the heart of the order is the Fed grasp account, a cost account that enables eligible establishments to entry Federal Reserve cost companies immediately.
These companies embrace Fedwire, the high-value cost system utilized by banks and monetary establishments to maneuver {dollars} throughout the US monetary system.
Beneath present Fed guidelines, entry is usually restricted to depository establishments. That has led some crypto corporations to hunt special-purpose financial institution or nationwide belief financial institution charters to qualify for direct entry.
Trump’s order asks the Fed to conduct a complete evaluate of its framework for granting entry to Reserve Financial institution cost accounts and cost companies. It additionally directs the central financial institution to make clear whether or not the 12 regional Federal Reserve banks have the authorized authority to independently approve or deny functions.
That query has turn out to be extra pressing after the Kansas Metropolis Fed permitted a limited-purpose cost account for Payward, Kraken’s mum or dad firm, in March.
The approval gave the crypto change’s banking unit a restricted connection to the Fed’s cost system, making a precedent for different digital asset corporations in search of related entry.
The order additionally directs regulators to look at broader boundaries going through fintech corporations, together with licensing practices, third-party risk-management steerage, and insurance policies that will restrict partnerships between banks and know-how corporations.
Sen. Cynthia Lummis framed the directive as a correction to years of restricted entry for monetary know-how corporations.
She stated fintech corporations had lengthy been shut out whereas legacy establishments benefited from privileged entry, including that the administration’s order was aimed toward making a extra stage taking part in discipline, stronger competitors and decrease cost prices for customers.
Coinbase Chief Authorized Officer Paul Grewal additionally supported the transfer, saying the White Home had acknowledged that outdated guidelines on cost entry and third-party danger administration favored incumbents over innovators. He described the present framework as protectionist and stated regulators ought to replace it.
These feedback seize the crypto business’s argument that entry to funds has turn out to be a aggressive bottleneck. Corporations that can’t join on to Fed cost techniques should route exercise by way of banks, which may improve prices, sluggish settlement, and expose corporations to bank-specific danger.
Kraken provides crypto corporations a working mannequin
Kraken’s approval provides the business a sensible instance of how expanded entry may work.
In March, the Kansas Metropolis Fed granted Kraken Monetary a limited-purpose account that enables entry to core cost rails used for high-value greenback settlement.
The account may assist the change course of institutional deposits and withdrawals extra effectively, significantly for purchasers transferring massive balances between buying and selling venues, custodians, and banking companions.
The association is proscribed. Kraken doesn’t have entry to all companies accessible to insured banks, and the account reportedly excludes advantages similar to curiosity on reserves and entry to Fed credit score.
These limits are designed to cut back danger to the central financial institution whereas giving a crypto agency a narrower connection to cost infrastructure.
That mannequin may turn out to be the template for different digital asset corporations. A restricted account would enable corporations to maneuver {dollars} by way of Fed cost techniques whereas withholding privileges that regulators and banks think about extra delicate, together with overdrafts, reserve curiosity, or emergency lending entry.
Caitlin Lengthy, CEO of Custodia Financial institution, welcomed Trump’s intervention, saying the order acknowledged a unbroken downside on the Fed with blocking legally eligible establishments from the US cost system. Custodia has spent years preventing for entry after the Fed denied its utility to hitch the Federal Reserve System in 2023.
The Custodia determination stays a warning for the sector. The Fed concluded on the time that the financial institution’s enterprise mannequin and crypto focus had been inconsistent with the statutory necessities.
The rejection confirmed how troublesome it may very well be for corporations with digital asset publicity to acquire full entry even after they pursue regulated charters.
Kraken’s restricted approval modified the tone of that debate. Slightly than full entry or full rejection, regulators now have a narrower account construction they will use to convey crypto corporations nearer to the cost system whereas imposing safeguards.
Ripple, Coinbase, and Circle are positioned for the subsequent section
Ripple, Coinbase, and Circle are among the many corporations with the clearest enterprise causes to profit from a broader Fed entry framework.
Ripple has utilized for a Fed grasp account and helps the concept of a restricted or “skinny” account that may give non-bank monetary corporations entry to cost companies with out extending all central financial institution privileges.
Such entry may help Ripple’s RLUSD stablecoin enterprise by permitting quicker reserve motion and redemption exercise.
For stablecoin issuers, pace and certainty round reserve settlement are central to market confidence. A direct or restricted Fed account may scale back reliance on financial institution intermediaries and make it simpler to handle greenback liquidity in periods of heavy redemptions or market stress.
Coinbase and Circle have an identical curiosity by way of USDC and its broader funds infrastructure.
The businesses have a federal trust-bank construction that would deepen their integration with regulated monetary plumbing.
If finalized, that sort of constitution may place stablecoin operations below clearer federal oversight whereas positioning the corporations for direct or restricted entry to funds.
In the meantime, different corporations are additionally within the queue. Anchorage Digital already operates as a federally chartered crypto financial institution. Paxos, BitGo, and Constancy Digital Belongings have sought or acquired approvals tied to nationwide belief financial institution constructions from the Workplace of the Comptroller of the Foreign money (OCC)
These approvals don’t mechanically grant entry to Fed cost accounts, however they transfer the corporations nearer to the sort of regulated standing that would help an utility.
The enterprise case is simple. Crypto exchanges need quicker fiat settlement. Stablecoin issuers need extra direct reserve operations. Custodians need extra environment friendly asset motion for institutional purchasers. Fee corporations need decrease dependence on correspondent banks.
Alex Thorn, head of analysis at Galaxy Digital, argued that the concept that solely Fed-supervised, deposit-taking lenders ought to course of wire transfers is a contemporary regulatory selection somewhat than a everlasting rule of finance. He stated banks try to protect a funds monopoly as competitors emerges from a number of instructions.
That view displays a rising business argument that cost entry ought to be based mostly on operate, supervision, and danger controls somewhat than the standard financial institution mannequin alone.
Banks warn entry ought to include bank-grade requirements
Nonetheless, the banking business is making ready to problem that argument.
On Could 19, the American Bankers Affiliation (ABA) stated any firm providing bank-like companies ought to be required to fulfill the identical rigorous regulatory and consumer-protection requirements as banks.
ABA President and CEO Rob Nichols urged regulators to conduct the evaluate in a approach that enables innovation with out compromising the security and soundness of the monetary system. He stated:
“Until everyone seems to be held to the identical excessive requirements, the monetary system and customers shall be in danger. In mild of in the present day’s White Home Government order on monetary innovation, we urge the banking regulators to conduct their requested evaluate in a approach that enables for innovation however does not compromise the protected and sound monetary system we have now in the present day.”
That place goes to the core of the banking sector’s objection. Banks argue that direct entry to Fed cost techniques is a privilege tied to intense supervision, deposit insurance coverage, capital necessities, liquidity guidelines, and examination requirements.
They contend that corporations with narrower charters or limited-purpose licenses may create danger in the event that they achieve entry with out equal obligations.
The dangers should not theoretical for regulators. Fedwire is a central element of US greenback settlement. A cyberattack, operational failure, compliance breakdown, or liquidity downside at a agency with direct entry may create settlement disruptions with penalties past that firm’s personal clients.
Cash-laundering controls are one other concern. Banks spend closely on compliance techniques, buyer monitoring, and suspicious-activity reporting.
If crypto corporations achieve direct entry, regulators will want confidence that these corporations can meet equal expectations whereas working throughout buying and selling, custody, stablecoin, and cost markets.
Liquidity can be a part of the controversy. Banks have warned that broader entry may pull funds away from the standard banking system, particularly if stablecoin issuers and fintech corporations can maintain balances or transfer funds extra effectively by way of the Fed.
Restricted accounts that don’t pay curiosity or supply credit score may scale back that concern, however banks are unlikely to just accept the shift with out a battle.
The Fed has signaled that limited-purpose accounts may mitigate a few of these dangers by denying entry to order curiosity, Fed credit score, and different privileges.
Nonetheless, the construction nonetheless raises a coverage query: how a lot entry can regulators grant earlier than a non-bank begins to appear like a financial institution for cost functions?


