

For conventional US banks, the CLARITY Act was meant as a firewall that successfully barred crypto corporations from providing “passive” curiosity on stablecoins.
The laws aimed to stop a catastrophic deposit flight by which on a regular basis checking account balances drain from the banking system into high-yield crypto exchanges.
However as lawmakers put together to finalize the framework, Coinbase seems to be quietly structuring a loophole that depends on advanced monetary engineering to maintain the profitable yield flowing.
The important thing lies in a important semantic distinction inside Part 404 of the proposed laws. Whereas the CLARITY Act explicitly outlaws savings-account-style curiosity on stablecoins, it preserves “activity-based” rewards.
Enter Ethena, an artificial greenback protocol that generates returns by an lively, delta-neutral foundation commerce that includes shorting crypto perpetual futures whereas holding the spot asset.
By integrating with Ethena, Coinbase might theoretically route idle USDC into this technique.
If profitable, the trade might move alongside the earnings of an lively buying and selling technique and probably supply huge yields on digital {dollars} proper underneath regulators’ noses whereas deeply irritating a conventional banking sector caught providing negligible charges.
The legislative wall known as CLARITY Act
The CLARITY Act, a sweeping US market-structure invoice designed to outline how crypto property and intermediaries function underneath federal rules, has been a legislative battleground.
On the heart of the dispute that dragged out the Senate Banking Committee’s course of is the query of stablecoin rewards.
The newest compromise is primarily captured in Part 404, which was born from the Tillis-Alsobrooks modification. The availability attracts a tough regulatory line that the trade negotiated for months.
On one aspect is passive yield: merely holding a stablecoin steadiness and receiving periodic curiosity, which is structurally an identical to a financial institution financial savings account. That is explicitly banned.
On the opposite aspect are activity-based rewards: incentives tied to precise buyer exercise, resembling funds, transactions, platform utilization, and buying and selling. These are permitted.
The financial institution foyer pushed onerous for these restrictions. Banking executives contend that companies providing bank-like merchandise ought to face comparable oversight, reserve, and capital obligations.
If crypto platforms might freely pay savings-account charges on stablecoin balances with out FDIC insurance coverage necessities, they might simply siphon depositor capital on the expense of the regulated banking system.
JPMorgan Chase CEO Jamie Dimon just lately voiced this actual frustration. In a current interview, Dimon criticized Coinbase CEO Brian Armstrong and warned that the CLARITY Act might fail if conventional banking considerations aren’t addressed.
Requested if he was glad with the present draft of the invoice, Dimon was blunt, saying:
“No, as a result of it permits them to successfully pay curiosity on deposits, stablecoins or one thing like that, with out safety that they need to have. The banks is not going to settle for it that approach…”
For the laws to change into legislation, representatives from the Senate Banking and Agriculture committees should merge their superior payments earlier than it clears the total Senate, the Home, and lands on President Donald Trump’s desk. However whereas Washington debates, the crypto trade is already constructing across the new guidelines.
Coinbase’s Ethena workaround
Coinbase depends closely on stablecoins. In Q1 2026, the trade reported $305.4 million in stablecoin income, making up roughly 52% of its subscription and providers income.
The agency additionally acknowledged that it held a median of about $19 billion in USDC throughout its merchandise, accounting for greater than 25% of the whole USDC in circulation.
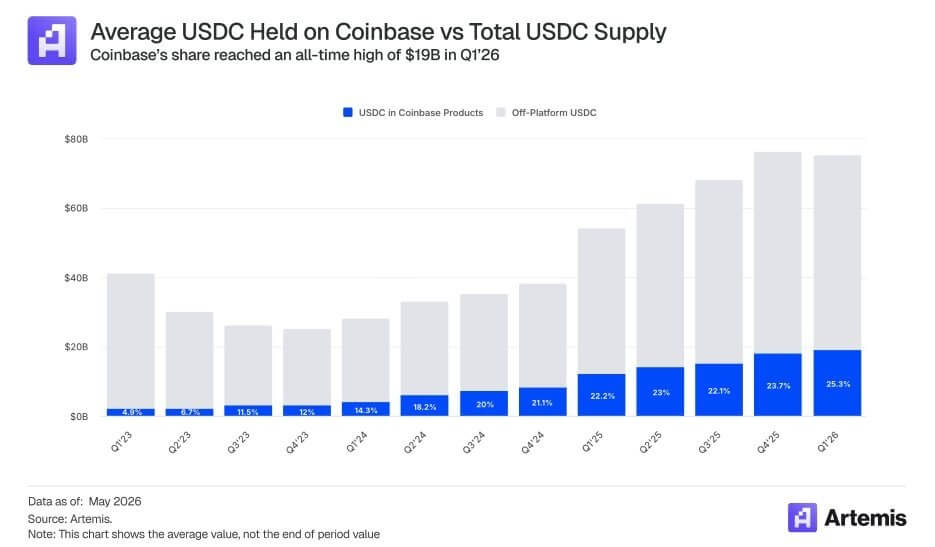
To guard this important income engine underneath Part 404, Coinbase wanted a product by which yield is tied to express exercise moderately than passive holding. Its new partnership with Ethena completely threads this needle.
Ethena acknowledged:
“Ethena and Coinbase have partnered to develop on-chain finance and financial savings merchandise for his or her 100 m+ person base, with the primary progress initiative launching subsequent week.”
Alongside the mixing, Coinbase Ventures made its first funding into Ethena on the open market.
Coinbase additionally confirmed its expanded function, noting it’s going to assist safety and operations throughout greater than $5 billion in Ethena property. Coinbase now serves as Ethena’s main custodian, pockets supplier, and perpetuals venue.
As a result of Ethena generates yield by advanced buying and selling actions, Coinbase can route yield-seeking USDC customers into actual borrow demand and lively market methods.
Man Younger, Ethena’s Founder, explicitly acknowledged the regulatory tailwinds, saying:
“Excited to associate with Coinbase for the primary time to assist their greenback financial savings merchandise…Given the evolving nature of the Readability Act, we anticipate additional potential tailwinds for onchain native merchandise like USDe from idle balances on exchanges, and Ethena is effectively positioned to assist this transition.”
Yan Liberman, a managing associate at Delphi Ventures, highlighted precisely how profitable this structural shift may very well be for either side. He acknowledged:
“Studying between the traces for the upcoming product launch referenced. Coinbase x Ethena is bullish as a result of it could actually flip Coinbase’s ~$19B USDC base, with an implied ~$13B of reward-earning balances, right into a funding rail for Ethena. If sUSDe yields clear baseline USDC charges, Coinbase can supply higher USDC lending yields, loopers can lever the unfold, and Ethena will get deeper/cheaper funding than native DeFi alone. Aave mechanics, Coinbase distribution.”
Liberman added that the CLARITY Act makes this pivot extremely invaluable. If lawmakers limit passive USDC rewards, Ethena offers Coinbase a strategy to route customers into actual borrow demand moderately than merely paying them for holding USDC.
He added:
“Coinbase wants merchandise the place yield is tied to express exercise: lending, collateral, liquidity, or platform utilization. Ethena offers them a strategy to route yield-seeking USDC customers into actual borrow demand, moderately than simply paying rewards for holding USDC.”
The brand new “Coinbase downside” for banks
Whereas banks may really feel protected by Part 404’s ban on passive curiosity, the Ethena loophole presents a brand new and instant menace.
Stablecoins have outgrown their origins as a distinct segment settlement layer. The entire stablecoin market sits at roughly $320 billion, with USDC at about $76 billion and Ethena’s USDe round $4.5 billion.
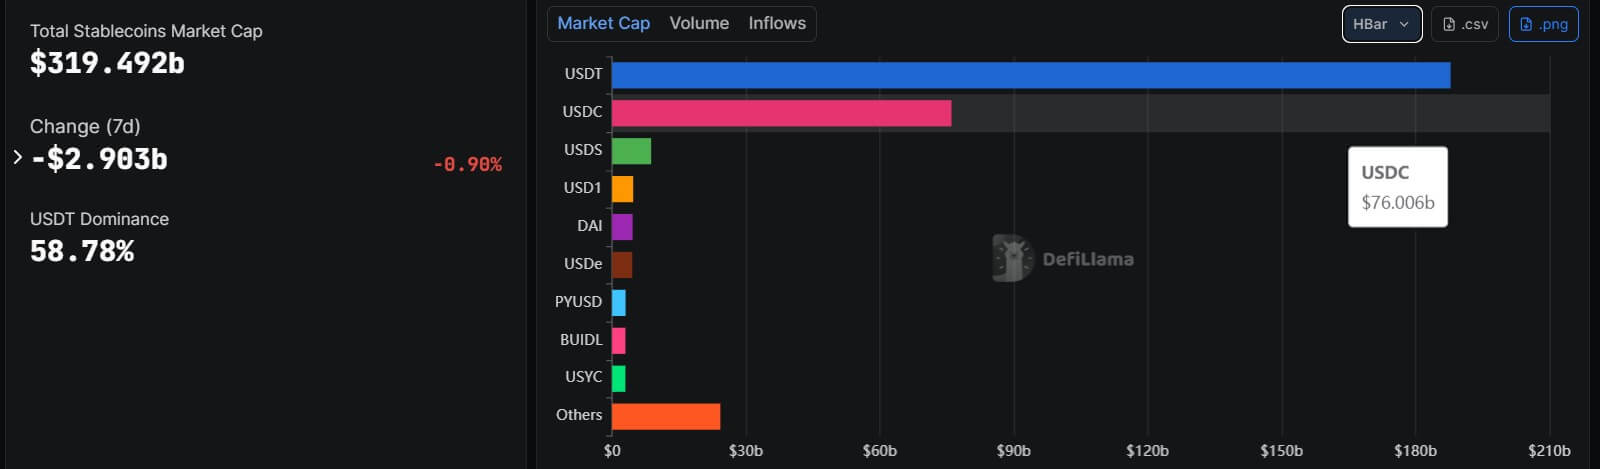
As a result of Circle backs USDC with extremely liquid money and cash-equivalent property with month-to-month attestations, Coinbase’s technique makes use of USDC because the trusted settlement asset, whereas Ethena provides the yield-bearing synthetic-dollar layer.
Admittedly, a direct systemic financial institution run is unlikely. US industrial financial institution deposits stood at roughly $19.3 trillion in late Could 2026, and money-market fund property sat at $7.78 trillion. Even when Coinbase transformed its complete $19 billion USDC steadiness, it might be a drop within the bucket in comparison with the broader banking system.
Nevertheless, the true hazard to banks is marginal pricing stress.
If cell, yield-sensitive retail clients and institutional treasuries understand they’ll seamlessly entry ~3.8% APY by an activity-based Ethena technique inside a Coinbase app, they’ll inevitably transfer their idle money.
To stem the outflow, conventional banks could also be pressured to lift their very own traditionally low deposit charges, which instantly eats into their web curiosity margins. Notably, US financial savings accounts yield simply 0.38%, and curiosity checking accounts scrape the underside at 0.07%.
Furthermore, Tom Wan, head of analysis at Entropy Advisors, identified that the Coinbase and Ethena integration may very well be the start of an institutional synergy that bypasses conventional banking solely.
Wan notes Ethena can leverage institutional lending through Coinbase Asset Administration, make the most of Coinbase Custody, and use USDC as a liquid stablecoin backing. Sooner or later, Coinbase might change into a main foundation commerce venue and allocate backing property to lending protocols like Aave on Base to develop USDe as a dominant financial savings product.


