
Vitalik Buterin is difficult one in every of DeFi’s most acquainted security mechanisms: the automated liquidation that closes a debt-backed place when collateral falls under the required backing for the mortgage.
In a June 1 Ethereum Analysis publish, Buterin proposed constructing artificial, index-tracking property on high of choices, with collateralized debt faraway from the bottom design.
The concept would take away the arduous liquidation set off from the bottom design and change it with a slower type of danger: the person’s publicity drifts away from the goal except the place is rebalanced.
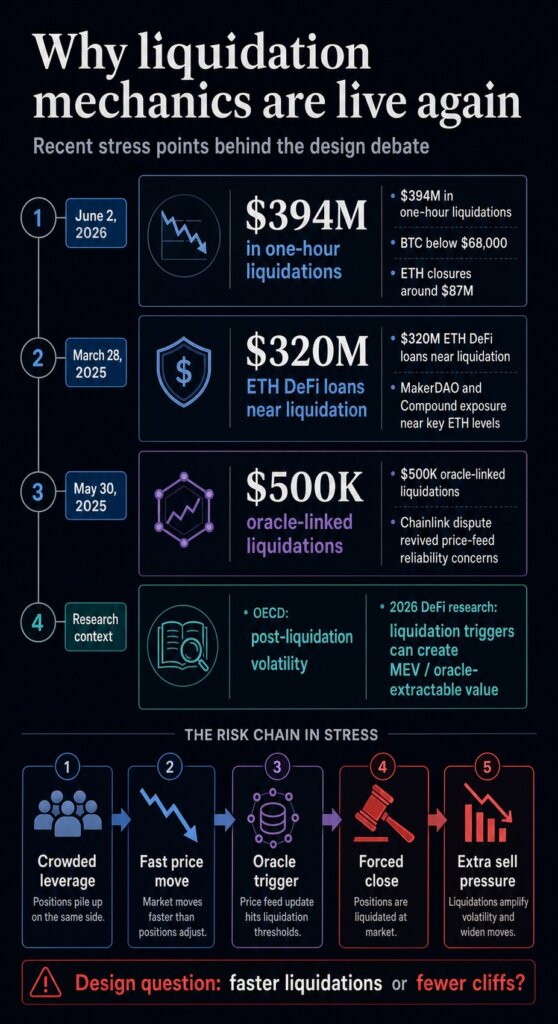
That distinction is necessary as a result of the outdated mechanism continues to be exhibiting up in market stress. Bitcoin‘s fall under $68,000 triggered about $394 million in one-hour liquidations on June 2, together with roughly $87 million in ETH positions, as leveraged bets had been force-closed throughout the market.
The flash crash got here someday after Buterin’s publish and serves as a market reminder: when worth strikes hit crowded leverage, automated closures can flip a drop right into a wider market occasion.
The proposal is research-stage structure: a design argument separate from any protocol launch, Ethereum roadmap dedication, or direct alternative for Aave, Maker, or current stablecoins. It shifts the main focus from collateral buffers and sooner worth feeds to a extra basic design selection: whether or not prompt liquidation ought to stay DeFi’s central technique of surviving a crash.
Why the security change can amplify stress
Most DeFi lending methods are constructed across the identical primary drawback. A person locks in collateral, borrows in opposition to it, and should hold the place above a required security stage.
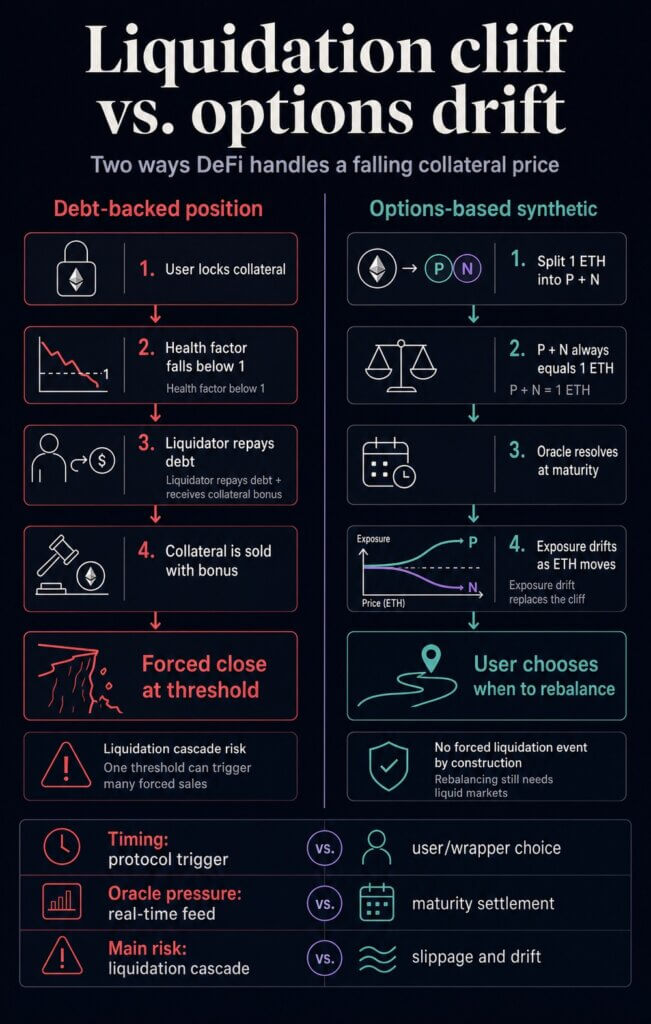
In Aave’s borrowing documentation, that stage is expressed via a well being issue. When it falls under 1, the place might be liquidated: a liquidator repays debt on the borrower’s behalf and receives collateral plus a bonus.
That construction protects the protocol’s solvency, however it additionally concentrates motion on the worst doable second. If ETH or one other collateral asset falls quick sufficient, customers don’t select when to promote. The system chooses for them.
Liquidators compete to shut eligible positions, and the collateral might be pushed into markets already quick on liquidity.
The document helps that concern. An OECD working paper on DeFi liquidations discovered a optimistic relationship between liquidation exercise and post-liquidation worth volatility throughout main decentralized alternate swimming pools.
The paper additionally emphasised that liquidators depend on out there liquidity throughout stress, which suggests the mechanism designed to revive stability can run into the identical liquidity scarcity as everybody else.
CryptoSlate has beforehand coated the operational model of that danger. A 2025 Chainlink-related oracle dispute led to greater than $500,000 in liquidations on Euler Finance and revived questions on how protocols ought to interpret pricing information in illiquid markets.
Individually, a 2025 ETH decline put practically $320 million in Ethereum-based DeFi loans inside 20% of liquidation, with MakerDAO and Compound publicity concentrated close to key worth ranges.
The frequent thread is the cliff. DeFi wants a method to deal with undercollateralized positions, however the present technique usually waits till a quantity is breached after which requires rapid motion.
That creates a crowded second for debtors, liquidators, oracle feeds, and liquidity suppliers concurrently. It additionally offers refined actors a transparent set off to observe, as a result of the protocol rule pronounces when a place turns into worthwhile to shut.
For customers, the sensible consequence is simple. A liquidation system can defend a lending pool whereas nonetheless giving the person borrower the worst doable execution window.
The person could have supposed to maintain long-term ETH publicity, hedge a money want, or wait out a pointy wick. As soon as the edge is crossed, the system’s precedence turns into solvency, and the person’s timing desire disappears.
How choices flip a cliff into drift
Buterin’s various begins by altering the primitive. A place that may turn out to be undercollateralized offers method to a cut up ETH declare: the proposal divides 1 ETH into two option-like property, referred to as P and N, tied to a worth index, strike worth, and maturity date.
At maturity, an oracle resolves the index worth and determines how a lot of the ETH declare either side receives.
The important thing property is easy: P and N all the time add again as much as 1 ETH. As a result of the system is dividing a hard and fast ETH declare between two sides, it might probably keep away from seizing collateral from a borrower to shut a deficit.
In Buterin’s framing, the design removes the liquidation occasion by building.
For a person attempting to carry artificial greenback publicity, the sensible expertise differs from a debt-backed stablecoin. Within the debt mannequin, a person can seem absolutely hedged till the collateral threshold is breached, at which level the place is force-closed.
Within the choices mannequin, the holder avoids the sudden shut, however the place can progressively cease behaving because the person supposed.
Buterin’s instance makes use of a person who needs some stage of greenback publicity whereas ETH is buying and selling round $2,500. The person might purchase a deep choice tied to a decrease strike, resembling $1,500, and rotate into lower-strike choices if ETH falls towards the unique strike.
If the person doesn’t rebalance, the publicity drifts. The person retains a declare, however the hedge turns into much less actual.
That’s the central tradeoff. The design retains danger within the system, and adjustments who controls the timing and what kind the injury takes.
Liquidation-based methods outsource the choice to a protocol rule and liquidator bots. The choices-based design pushes extra of that call towards customers, wrappers, market makers, or automated rebalancing methods.
Buterin additionally acknowledged a restrict for stablecoin use. A medium quantity of annualized drift could also be acceptable for somebody in search of worth stability relative to future bills.
It’s a lot much less helpful for an accounting stablecoin, the place customers wish to deal with the token as a greenback for funds, bookkeeping, or tax reporting.
The oracle tradeoff
The oracle argument often is the proposal’s most necessary protocol-design declare.
Debt-backed liquidations rely on real-time worth feeds. A protocol wants a binding worth rapidly sufficient to find out when a place is unsafe and to permit liquidators to behave.
Buterin argues that this constraint makes real-time oracles arduous to safe as a result of they depend on automated actors watching dwell indicators and depart little room for slower dispute decision.
Choices transfer the crucial oracle name to maturity. Oracle danger stays, however the time stress adjustments.
If a system can wait to resolve a contract, it might probably use slower, extra contestable mechanisms, together with prediction-market-style approaches or costly fallback oracles that may be impractical for fast liquidation.
That’s the reason the proposal is greater than a stablecoin tweak. It shifts DeFi’s danger structure away from a single dwell worth that may set off irreversible motion.
Latest analysis on liquidation dynamics in DeFi exhibits why that floor is central: liquidation mechanics can create incentives round worth manipulation, MEV, and oracle-extractable worth when a worthwhile closure is dependent upon a market worth crossing a set off.
The profit nonetheless is dependent upon implementation. A wrapper that robotically rebalances for customers might make the product simpler to carry, however it might additionally recreate seen timing guidelines that refined merchants can anticipate.
A purely native person agent might cover some timing decisions, however would elevate its personal usability and execution questions. An onchain DAO wrapper would want deterministic guidelines and deep markets to keep away from turning into one other predictable goal.
Sluggish oracles assist provided that the remainder of the design avoids forcing the identical drawback elsewhere. That’s the pressure Buterin’s publish leaves for builders.
A slower oracle may give a system extra time to settle disputed data, however customers nonetheless want markets deep sufficient to rotate publicity and guidelines sturdy sufficient to keep away from turning each rebalance into an exploitable sign.
The comparability with prior oracle disputes is beneficial right here as a result of the chance arises when dangerous information meets a rule that should act instantly.
The choices design reduces the necessity for that prompt determination, whereas builders nonetheless should resolve who watches the index, who gives liquidity, and who absorbs losses when the market strikes sooner than the hedge.
What builders nonetheless should show
The following check is whether or not the market construction round Buterin’s thought might be aggressive with the debt methods it might problem.
The proposal itself flags slippage as a serious danger. Rebalancing via bizarre automated market makers could possibly be costly, particularly if customers have to rotate choice publicity repeatedly throughout risky intervals.
Buterin steered that rebalancing may want a special market construction, nearer to affected person one-sided market making than an prompt promote.
That requirement is the adoption check. If customers keep away from liquidation however bleed an excessive amount of worth via drift, slippage, or operational complexity, the mannequin turns into elegant analysis fairly than helpful DeFi infrastructure.
If builders could make rebalancing low-cost and fewer uncovered to assault, the concept might turn out to be a critical various for customers who need worth stability with out signing up for a liquidation cliff.
The identical check applies to stablecoin framing. The proposal is most defensible when described as a method to maintain a stability-oriented publicity or private hedge.
It turns into weaker if marketed as a easy greenback alternative. A token that drifts away from its goal and desires periodic rotation is a special person promise from a redeemable greenback, an overcollateralized stablecoin, or a traditional CDP-backed artificial.
For Ethereum, the importance is that one in every of its most influential designers is treating liquidation as an architectural selection fairly than an unavoidable truth of DeFi.
The following sign is whether or not any protocol workforce turns the choices mannequin right into a examined wrapper, simulation, or dwell market with adequate liquidity to display the trade-off in observe.
Till then, the proposal is finest learn as a direct problem to DeFi’s crash mechanics: the business can hold attempting to make liquidations sooner and higher collateralized, or it might probably check designs constructed with out sudden compelled gross sales.


