

Morgan Stanley introduced on June 5 that eligible wealth administration purchasers can now lend Bitcoin, Ethereum, or Solana to Galaxy Digital and obtain shares of spot crypto exchange-traded merchandise in return.
Galaxy will coordinate an in-kind creation with a licensed participant, then ship ETP shares straight into the consumer’s chosen account. Onboarding timelines that beforehand exceeded 4 weeks might fall by as much as 75%.
For Morgan Stanley-referred purchasers, Galaxy has lowered the minimal transaction dimension from $25 million to $5 million.
US-traded spot Bitcoin ETFs recorded a historic $4.4 billion in internet outflows over 13 consecutive weeks, extending into early June. Bitcoin has fallen roughly 53% from its October 2025 all-time excessive close to $126,200 and briefly touched $60,000 this week.
In opposition to that backdrop, Morgan Stanley’s association presents wealth purchasers direct holding of cash that enter the financial institution’s portfolio equipment and grow to be marginable, reportable, and accessible to the identical infrastructure that already helps securities lending, margin accounts, and personal banking.
The regulatory layer that made this doable
The SEC’s approval of in-kind creations and redemptions for crypto ETPs in July 2025 eliminated the central structural impediment.
That change permitted approved contributors to create and redeem spot crypto ETP shares utilizing underlying crypto property, transferring the plumbing nearer to how commodity ETPs already perform.
Galaxy can now take a consumer’s BTC, use it to create ETP shares in sort, and ship these shares with out a taxable sale of the underlying asset, a workflow that will have required a money conversion spherical journey underneath the prior guidelines.
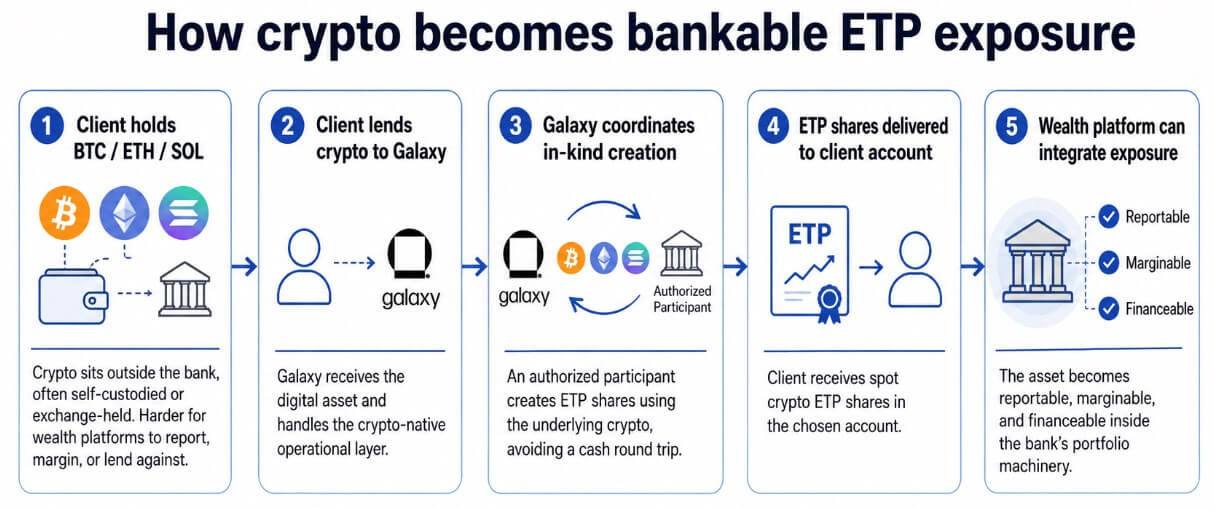
Morgan Stanley limits its position to referrals and consumer training, and Galaxy supervises onboarding and bears the crypto operational publicity.
That division retains Morgan Stanley on the regulated-securities aspect of the interplay, whereas Galaxy bears the operational publicity to crypto.
Exterior crypto wealth, beforehand held in self-custody or on an alternate, strikes right into a bankable portfolio, the place it may possibly function collateral for margin and combine with reporting and lending companies.
Three fashions for 3 theories
Morgan Stanley’s association sits inside a broader institutional divergence about which type of crypto publicity banks can safely acknowledge, and three fashions at the moment are operating in parallel.
The primary is ETP collateral, which is essentially the most bank-friendly kind, since banks perceive learn how to worth, custody, margin, and liquidate a registered safety. JPMorgan moved right here first, accepting BlackRock’s IBIT shares as collateral for loans earlier than increasing additional.
The Morgan Stanley/Galaxy association extends this mannequin by changing crypto held exterior the financial institution into ETP shares that slot into present wealth-management, margin, and lending workflows.
The second mannequin is direct crypto collateral, representing the larger structural leap. JPMorgan deliberate to permit institutional purchasers to pledge BTC and ETH straight towards loans by year-end 2025, with third-party custodians holding the pledged property. The financial institution has not publicly confirmed a reside product, and the standing remains to be based mostly on reported plans.
ModelBank consolation levelMain asset formExample from articleWhat banks likeMain riskETP collateralHighSpot Bitcoin / crypto ETP sharesMorgan Stanley/Galaxy; JPMorgan accepting IBIT collateralFamiliar securities wrapper, custody, pricing, marginingETF outflows transmit institutional sellingDirect crypto collateralMedium to lowBTC / ETH pledged directlyReported JPMorgan BTC/ETH collateral planMore direct use of crypto as balance-sheet collateralVolatility, custody, margin calls, liquidation rightsTokenized collateral substitutionRisingTokenized Treasuries, MMFs, depositsStandard Chartered/OKX/BlackRock BUIDL; HSBC tokenized depositsYield-bearing, lower-volatility collateral legSettlement, authorized, and platform interoperability threat
If operational, it might deal with BTC and ETH the way in which banks already deal with publicly traded shares in a margin account, with real-time valuation, haircuts, and automatic margin calls.
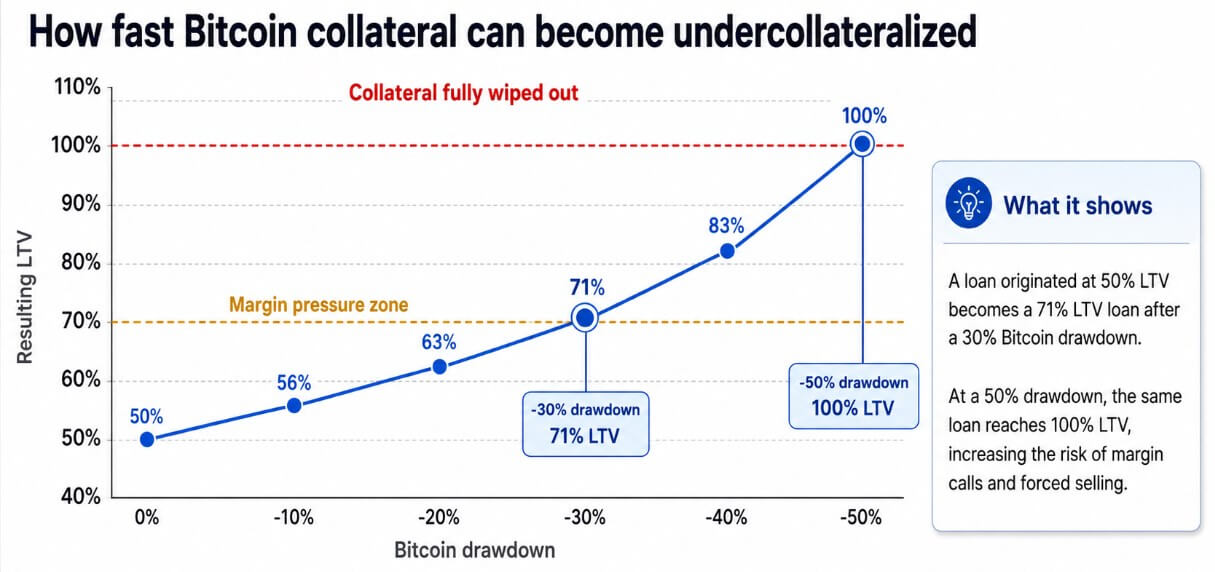
A mortgage originated at 50% loan-to-value turns into a 71% LTV mortgage after a 30% Bitcoin drawdown. At a 50% drawdown, that very same mortgage hits 100%, leading to full collateral wipeout.
The $1.8 billion in compelled crypto liquidations recorded on June 3 alone, the most important single-day determine since February 2026, illustrates what leverage produces in a quick market.
The third mannequin, tokenized collateral substitution, could show to be essentially the most sturdy. Banks desire tokenized Treasuries or cash market funds because the collateral leg, whereas crypto stays because the traded threat asset.
On Apr. 28, OKX, BlackRock, and Normal Chartered launched a framework that enables institutional purchasers to publish BlackRock’s BUIDL tokenized Treasury fund as yield-bearing margin collateral on OKX, with Normal Chartered serving as the primary G-SIB custodian in such an association.
Shoppers earn yield on collateral they might in any other case go away idle, and Normal Chartered handles regulated off-exchange custody, preserving property segregated from the alternate’s personal holdings.
What banks are literally constructing
Normal Chartered’s off-exchange mannequin with OKX means crypto-native buying and selling venues want a regulated G-SIB wrapper to draw essentially the most cautious institutional capital.
BNY is constructing its digital asset platform by combining custody, collateral administration, financing, funds, and 24/7 liquidity rails, positioning it because the infrastructure substrate on which crypto lending and tokenized asset markets will run.
Citi has framed its position round settlement, custody of stablecoin reserves, and crypto ETF custody companies, claiming the plumbing.
Each main financial institution is competing to regulate the wrapper, the custodian, the collateral agent, or the servicing infrastructure by which Bitcoin flows.
Two paths by the identical plumbing
Within the bull case, regulatory readability and stronger custody controls normalize using BTC and ETH as pledged collateral for institutional debtors.
Citi’s June 2026 tokenization report places international tokenized property at roughly $17 billion at the moment, with a 2030 bull-case forecast of $8.2 trillion.
If that trajectory holds, crypto collateral turns into a routine characteristic of financial institution lending, tokenized Treasuries develop as the popular institutional margin asset, and Bitcoin turns into extra helpful as a balance-sheet instrument.
The plumbing that Morgan Stanley and Galaxy are assembling will get prolonged throughout non-public banking at scale, pulling self-custodied wealth into managed portfolios the place it may be financed, reported, and deployed.
Within the bear case, volatility and operational threat hold banks anchored to the ETP wrapper. Direct Bitcoin collateral packages keep narrowly eligible and high-haircut, with restricted attain past a slim institutional base.
Banks lean on tokenized Treasuries and deposits, with HSBC increasing its tokenized deposit service to US purchasers in April 2026, enabling 24/7 on-chain fund motion with out public-chain settlement threat, whereas uncooked BTC lending stays confined to a small set of crypto-native lenders and hedge funds.
Bitcoin ETF outflows grow to be a recurring characteristic, because the regulated wrapper attracts capital that additionally leaves by the identical door when sentiment shifts.
The leverage loop
Neither situation eliminates the structural consequence of collateralization itself.
Galaxy Analysis estimated that crypto-collateralized lending reached $73.59 billion within the third quarter of 2025, break up amongst DeFi lending (55.7%), CeFi (33.1%), and crypto-collateralized stablecoins (11.2%).
As banks increase from ETP collateral towards direct BTC and ETH lending, extra of Bitcoin’s worth conduct will replicate institutional deleveraging cycles.
The $4.4 billion in spot ETF outflows that pushed Bitcoin beneath $60,000 this week present how shortly regulated wrappers can transmit institutional promoting. Add direct crypto-backed mortgage margin calls to that mechanism, and drawdowns carry extra compelled promoting than the market has traditionally processed.
Morgan Stanley’s association with Galaxy is a wealth-management funnel: exterior crypto wealth enters the financial institution’s portfolio equipment, turns into financeable and reportable, and turns into extra correlated with no matter causes institutional buyers to cut back threat.
Bitcoin adoption turns into built-in into the identical collateral loops that govern each different asset class, with all of the structural upside and deleveraging publicity that entails.


