
The UK Monetary Conduct Authority is weighing a rule that may let UCITS schemes and most non-UCITS retail schemes maintain crypto exchange-traded notes, capped at 10% of scheme property.
The proposal, set out within the FCA’s CP26/17 session, would transfer crypto publicity deeper into regulated fund plumbing. Retail buyers already gained a path to crypto ETNs as standalone trade merchandise.
The brand new query is how far these notes can journey inside diversified portfolios run by approved fund managers.
The reply is a brief leash. The FCA would permit a restricted ETN sleeve the place it matches the fund’s disclosed goal and danger profile.
Direct holdings of Bitcoin, Ether, or different cryptoassets for funding functions stay outdoors the proposal. Feedback on the fund chapter are due July 13, 2026.
What the cap would permit
The proposed rule would give UK UCITS schemes and, with exceptions, non-UCITS retail schemes a capped allocation channel. The restrict would apply on the scheme-property stage, that means as much as 10% of a fund’s property may encompass transferable securities which might be cryptoasset ETNs.
That threshold makes the publicity attainable whereas retaining it secondary. A balanced multi-asset fund may use the permission as a satellite tv for pc allocation.
A fund marketed as a traditional retail portfolio would nonetheless sit inside the retail authorized-fund framework, with crypto publicity contained by the ETN wrapper and the proportion cap.
The FCA additionally attracts traces between fund sorts. Certified investor schemes, that are offered to skilled shoppers and complicated buyers, sit outdoors the identical proposed retail-fund restrict.
Lengthy-term asset funds and NURS working as funds of different funding funds face a proposed prohibition on crypto ETN holdings, with the FCA asking for views on that remedy.
VehicleProposed treatmentImplicationUK UCITS schemesMay maintain cETNs as much as 10% of scheme propertyOpens a capped route inside mainstream retail fund portfoliosMost NURSMay maintain cETNs as much as 10% of scheme propertyExtends the identical restricted channel past UCITS structuresQualified investor schemesOutside the proposed retail-fund capReflects their skilled and complicated investor baseLTAFs and NURS working as FAIFsProposed prohibition on cETN holdingsSignals that some fund wrappers might stay outdoors the channelDirect crypto holdingsExcluded for funding purposesKeeps the publicity oblique by listed notes
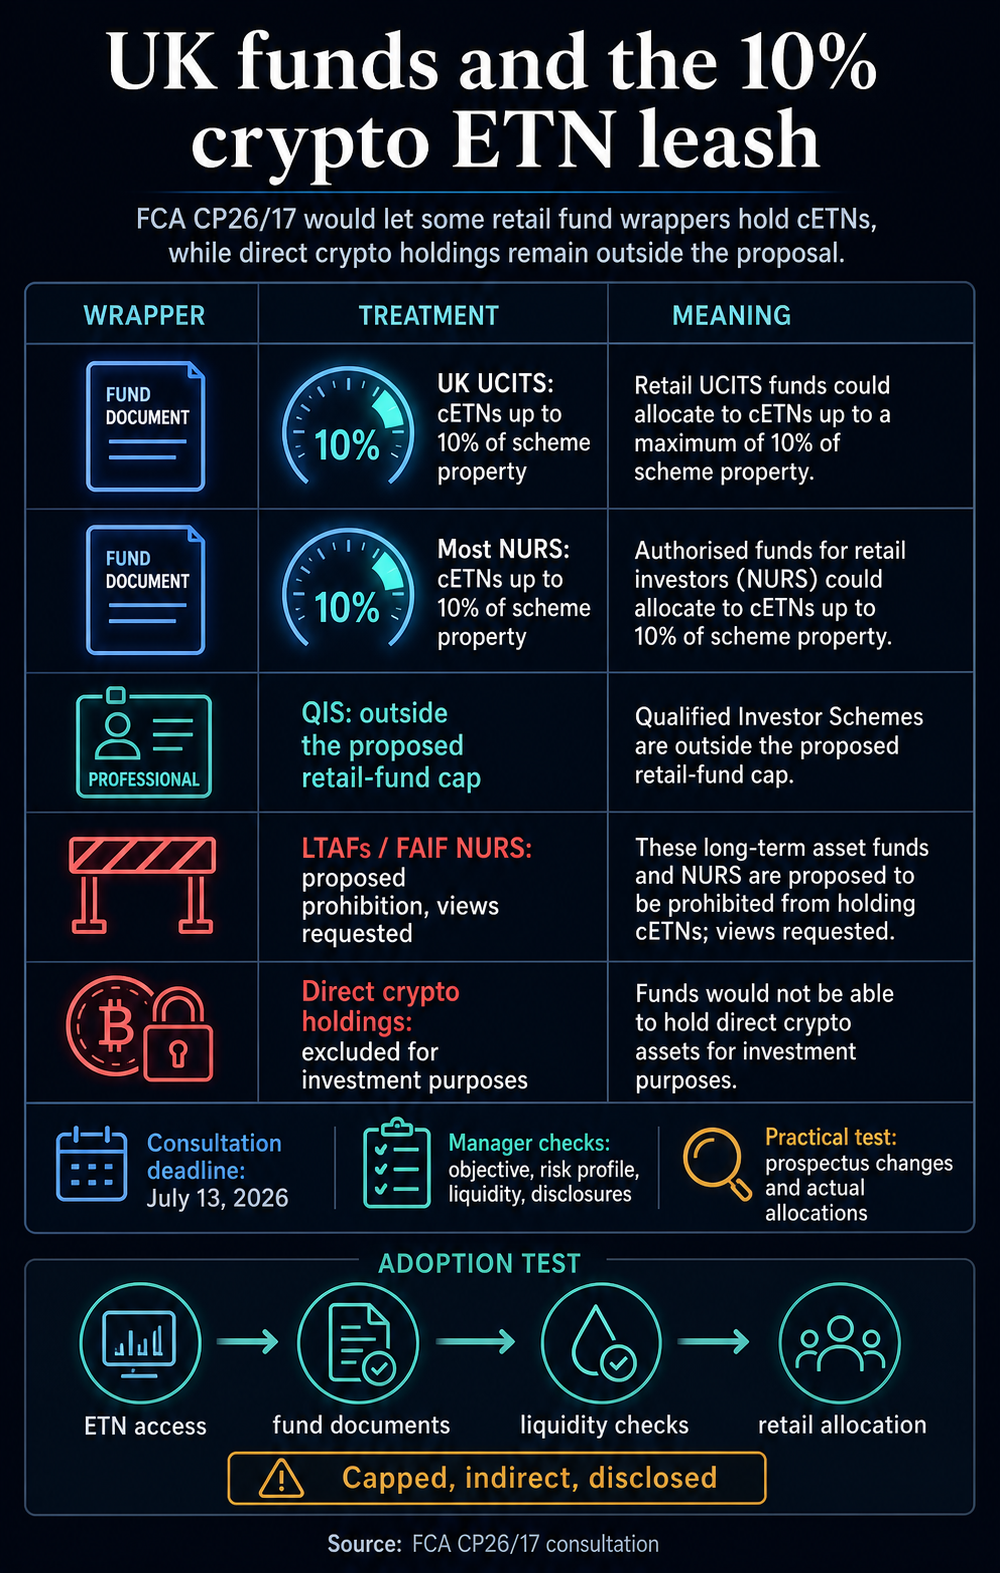
That distinction offers the proposal its form: entry can increase by securities legislation and fund guidelines whereas custody of the cash stays outdoors the fund portfolio.
A fund may get price-linked crypto publicity by a safety traded on a regulated venue. The underlying cryptoasset would stay past the approved fund’s funding holdings.
The proposal follows the FCA’s earlier determination to open retail entry to crypto ETNs traded on UK acknowledged funding exchanges.
That change, which got here into pressure on Oct. 8, 2025, allowed retail shoppers to entry cETNs by FCA-approved UK funding exchanges, with monetary promotion guidelines and Shopper Obligation protections making use of.
These protections saved cETNs in a high-risk class. The FCA stated retail cETNs sit outdoors Monetary Companies Compensation Scheme protection, and the ban on retail cryptoasset derivatives stays in place.
The regulator’s stance is that the market has advanced sufficient to allow managed entry whereas preserving a high-risk label for the underlying publicity.
That very same logic runs by the fund proposal. Crypto ETNs have already turn into a reside UK exchange-traded product class, with London Inventory Change protection describing the product phase one yr after launch.
For funds, nevertheless, the wrapper creates a second layer of duty. Managers should determine whether or not a listed word is eligible and whether or not the publicity suits a fund’s aims, liquidity profile, danger limits, and retail disclosures.
The FCA says fund managers ought to have satisfactory data and understanding of the belongings wherein a fund invests, conduct due diligence on funding choice, and monitor compliance with the fund’s goal, technique, danger limits, and liquidity profile.
It additionally says managers ought to think about whether or not cryptoassets and cETNs will stay liquid in burdened circumstances.
The cap is the seen management. Disclosure and liquidity work might determine how usable the permission turns into.
The FCA plans to depend on present disclosure guidelines for approved funds holding cETNs. It factors managers again to guidelines on fund aims, funding insurance policies, advertising and marketing communications, Shopper Obligation, and danger summaries for cryptoassets and cETNs.
It additionally says UCITS managers should embrace a distinguished volatility assertion the place a fund has, or is prone to have, larger volatility in its internet asset worth.
A supervisor utilizing the permission would want to clarify the publicity in fund paperwork and consumer-facing supplies whereas retaining the product’s character clear.
A small allocation should still be an important function of a technique when it’s greater than genuinely de minimis, as a result of crypto ETNs carry completely different dangers from many standard transferable securities.
The FCA additionally asks managers to evaluate cETN holdings in opposition to the broader portfolio, together with different higher-risk belongings, oblique crypto publicity by different funds, and belongings correlated with crypto, akin to cryptoasset treasury issuers.
A ten% cETN restrict subsequently leaves a separate query round the remainder of a fund’s crypto-linked market habits.
For retail buyers, the sensible impact is that crypto can transfer nearer to the default portfolio stack whereas staying seen. If adopted, the rule would permit a fund to incorporate cETNs, with the publicity disclosed, monitored, and evaluated alongside the remainder of the portfolio.
The true adoption take a look at
The proposal creates entry; demand nonetheless is determined by fund managers, platforms, depositaries, and distributors deciding that the capped publicity is definitely worth the documentation, governance, and suitability work.
One path is significant, restricted adoption. Managers may use cETNs as a small allocation device inside diversified funds.
In that case, the FCA’s rule would mark an actual shift: crypto publicity would transfer past a standalone retail determination or a professional-investor product and turn into one thing a mainstream fund may embrace with danger controls round it.
One other path is basically symbolic. Managers might determine that the ten% restrict, disclosure duties, liquidity questions, and reputational danger outweigh the profit.
The permission would stay a bridge that few merchandise cross, making a coverage change with a modest allocation footprint.
That’s the reason the proposal is greatest learn as an incremental normalization of crypto market construction as an alternative of a broad portfolio opening.
The FCA is accepting that crypto ETNs have turn into established sufficient to enter some approved funds whereas nonetheless attempting to cease the publicity from changing into a dominant retail portfolio danger.
The following sign will probably be allocator habits, submitting updates, and platform documentation.
UK asset managers will both rewrite prospectuses, product summaries, and platform supplies to make room for cETNs after the session closes, or the ten% cap will perform primarily as a symbolic bridge. Till then, crypto can transfer contained in the fund wrapper whereas remaining on a brief leash.


