
Have you learnt how a lot time you spent watching TV this previous week? I’ll inform you exactly. You spent two hours a day simply on Netflix, and possibly some extra on YouTube too. Most firms can do one in all two issues nicely. They will develop quick, or they will make some huge cash. Doing each, yr after yr, is uncommon. The way in which Netflix manages the battle on your consideration is the explanation I’m not only a long-time subscriber, however a long-time shareholder too.
How does Netflix do it? It has one of many deepest buyer lock-in results on this planet. Netflix raises its costs. Subscribers grumble, just a few cancel, after which nearly all of them keep, as a result of for the cash there may be nothing else prefer it.
The corporate takes that cash and reinvests it into making the platform extra invaluable with extra content material, and that permits it to lift costs once more in a virtuous cycle. Then it does it once more the following yr.
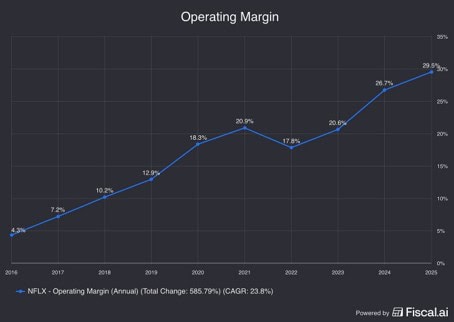
This interprets superbly to working metrics. Working margin has gone from 27% to almost 30% to a guided 31.5%, roughly two factors a yr, three years operating. That’s pricing energy and working self-discipline working collectively, and it’s the coronary heart of why I feel Netflix is a top quality enterprise. However there’s a key query that’s scaring buyers away. Netflix guided for decrease income progress this yr than the yr earlier than.
If progress is slowing from its golden period, does the inventory value replicate a future that’s now not actual?
After Netflix’s current fall, I imagine it does. However it’s not that easy.
In case you discover this sort of evaluation helpful, take into account subscribing. I publish new posts each week.
What Netflix Truly Does
Netflix sells leisure. To be exact, it sells streaming leisure to greater than 325 million paying households, reaching an viewers approaching a billion individuals. You pay a month-to-month price, you get an unlimited library of movies and sequence in dozens of languages, and more and more you possibly can pay much less for those who settle for some adverts.
The cash is available in 3 ways.
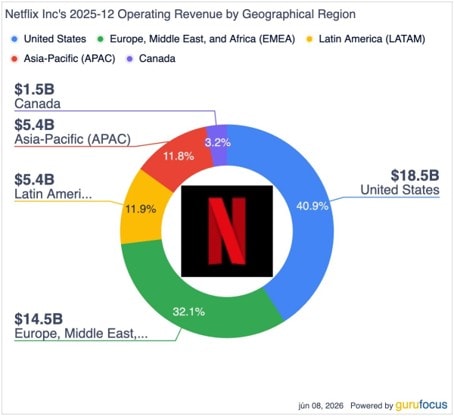
Most of it’s subscriptions, break up throughout 4 areas: the US and Canada (the most important by income), Europe (the most important by members), and the faster-growing Latin America and Asia-Pacific.
The second stream, nonetheless small however rising quick, is promoting on the cheaper ad-supported plan. The third, newer nonetheless, is dwell occasions: NFL video games, large boxing matches, the World Baseball Traditional, weekly WWE.
Did the quantity at the start shock you? It’s true. The common member watches about two hours a day, and in late 2025 Netflix reached its highest-ever share of TV time within the US, at 8.6%. This reveals how fierce the competitors on your consideration is, and it additionally reveals how a lot runway Netflix has forward of it.
Why I’m Writing About Netflix Now
Netflix was having fun with a large bull run, however that each one modified with a stunning administration choice. The often prudent, underpromising and overdelivering administration tried to accumulate WBD, a legacy film studio with huge real-world property. Precisely the sort of agency Netflix has been placing out of enterprise.
Buyers punished the corporate instantly. The inventory fell from $130 to $75. The bull thesis regarded damaged. Till one thing sudden occurred. Paramount joined the combat, and finally gained the bidding conflict and bought WBD.
The end result? Not solely did Netflix stroll away from an unpopular acquisition, however it additionally acquired a $2.8 billion break-up price. The query is, now that the elephant within the room has been addressed, what continues to be holding the inventory value depressed?
Netflix is quietly shifting its narrative. It was a subscriber-growth story. In 2025, Netflix stopped reporting that quantity completely. It was clear Netflix wished to redefine itself, and for buyers to take a look at income, revenue, and engagement because the platform matured and needed to pivot to pricing and supplementary enterprise strains to drive outcomes, not simply subscriber progress. Which means progress now comes as a lot from elevating costs and scaling adverts as from including members. The advert enterprise doubled in 2024, grew about two and a half instances in 2025, and is focused to roughly double once more to round $3 billion in 2026.
The Numbers That Matter
Income grew about 16% in 2025 to $45 billion, and is guided to roughly $51 billion in 2026. That’s slower than Netflix’s hypergrowth previous, however it’s on a a lot greater base. What issues is that Netflix has been constantly increasing its margins.
Netflix can also be good at producing money. Free money movement went from about $6.9 billion in 2024 to about $9.5 billion in 2025, up 37%. Virtually all of that money goes towards shopping for again inventory.
The Moat
Netflix’s aggressive benefit comes from its sheer scale of content material. Pricing energy is the proof. Netflix can increase costs even in a weaker client surroundings as a result of, for the cash, it delivers probably the most leisure per hour. That hole between worth and value is the moat.
The opposite moat mechanism is scale. Netflix spreads a content material funds of roughly $16 billion throughout 325 million households. That lets it each outspend rivals on hits and nonetheless develop its margin. Higher economics deliver higher content material, which drives engagement, which funds extra content material.
Is the moat sturdy? I feel Netflix can widen its content material moat, however it’s contested on complete consideration share, the place it competes not solely with YouTube but in addition with different platforms like Disney+ and Prime Video.
The Aggressive Panorama
The streaming business, with Disney, Amazon, Apple, and the newly merging legacy gamers, poses an actual risk. However because of a years-long first-mover benefit, Netflix has entrenched itself throughout nearly all of the addressable market.
Netflix has to win on content material breadth, as a result of its rivals have inherent benefits on high quality, similar to Disney motion pictures and HBO reveals. However to date, the corporate has managed this nicely.
Dividends & Buybacks
Netflix doesn’t pay a dividend, by selection, and has been clear it has no plans to begin. As a substitute it returns primarily all of its free money movement by share repurchases: about $6.3 billion in 2024 and $9.1 billion in 2025, steadily shrinking the share depend. With free money movement rising and a $2.8 billion one-time price within the financial institution, I anticipate the buyback to proceed.
Bull Case / Bear Case
The Bull Case
The bull case assumes Netflix would compound on each axis directly. It might develop income within the mid-teens, proceed elevating costs whereas holding retention regular, scale the high-margin advert enterprise, and develop working margin additional on higher value economics. The bull’s sincere danger is value: the standard is well-known.
The Bear Case
The bear case rests on progress expectations. Netflix’s valuation rests on the belief that it is going to be in a position to develop and develop margins. There may be already a slowdown in income progress, and since Netflix stopped reporting subscriber numbers, we are able to deduce that subscriber progress might be slowing too. Nevertheless, at this value, Netflix is priced for low single-digit progress, one thing I take into account unlikely.
If somebody who’d discover this handy, sharing goes a good distance.
Valuation & What the Road Thinks
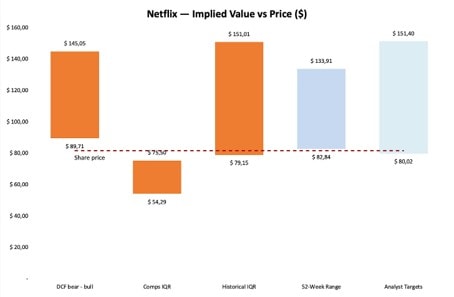
Netflix has traditionally traded at a premium valuation, which is why wanting purely at historic valuation may be deceptive.
I worth portfolio firms based mostly on three lenses. The historic valuation, if one have been to anticipate the agency to revert to its long-term median. The peer valuation, how the market values comparable firms, adjusted to replicate the interquartile vary to strip away extremes. And a customized DCF mannequin, the place I mannequin the financials in opposition to my expectations of future efficiency.
I take advantage of Wall Road analyst targets and the 52-week buying and selling vary as a sanity examine.
As you possibly can see, Netflix is now buying and selling on the low finish of its historic valuations, analyst estimates, and its buying and selling vary.
Its friends commerce cheaper, however the reason being that Netflix lacks actual pure-play streaming friends to match in opposition to. My DCF valuation suggests a flooring of $90 if the enterprise continues to carry out in step with expectations.
In investing, it is very important use a margin of security, and for a higher-risk title like Netflix, I like that margin to be 20% under honest worth. That brings us to a good worth estimate of $101, representing a 24% upside from the present value.
The draw back I’d take into account an actual danger is a reversal to the $75 assist, the place I’d revisit the thesis.
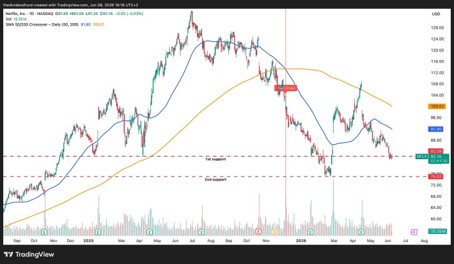
From a fast technical perspective, Netflix is at present sitting at an vital assist degree. If this breaks, we are able to anticipate one other down leg to $75, at which level, if the thesis and the economic system haven’t shifted dramatically, I’d take into account including considerably.
Netflix has already proven it has the momentum to recuperate towards a extra affordable value, however that fizzled out after the newest earnings report.
My Take
I not too long ago purchased extra Netflix inventory. It at present makes up round 7% of my portfolio. Netflix has what I search for: a robust enterprise, pricing energy, and a administration group that likes to underpromise and overdeliver.
On the draw back, I’d reassess my thesis if margin enlargement stalls or a value improve lastly drives subscribers away.
Backside Line
Netflix grows within the mid-teens, raises costs with out shedding prospects, expands its margins yearly, and generates near $10 billion in money it arms again to shareholders. The enterprise is firing on each cylinder. The one actual debate is what it’s value. Whether or not it belongs in your portfolio is dependent upon the value you pay and your time horizon, however I feel the machine itself is value keeping track of.
I share all my strikes in actual time on eToro, the place over 1 500 buyers observe my portfolio. In case you’re curious how this matches into the larger image, come discover me there: https://www.etoro.com/individuals/thedividendfund
Thanks for studying R² Funding Membership! Subscribe without spending a dime to obtain new posts and assist my work.
This communication is for data and training functions solely and shouldn’t be taken as funding recommendation, a private advice, or a suggestion of, or solicitation to purchase or promote, any monetary devices. This materials has been ready with out bearing in mind any specific recipient’s funding goals or monetary scenario and has not been ready in accordance with the authorized and regulatory necessities to advertise unbiased analysis. Any references to previous or future efficiency of a monetary instrument, index or a packaged funding product usually are not, and shouldn’t be taken as, a dependable indicator of future outcomes. eToro makes no illustration and assumes no legal responsibility as to the accuracy or completeness of the content material of this publication.
The put up The Neglected Tech Big You Shouldn’t Ignore appeared first on eToro.


