
DeFi lending protocol Edel disclosed a $403,000 exploit that hit the layer the place tokenized shares are attempting to turn into DeFi collateral.
Edel stated no depositor would bear losses, and the staff would take up the dangerous debt, restore affected balances one-to-one, and rebuild the protocol’s oracle structure for a model two launch.
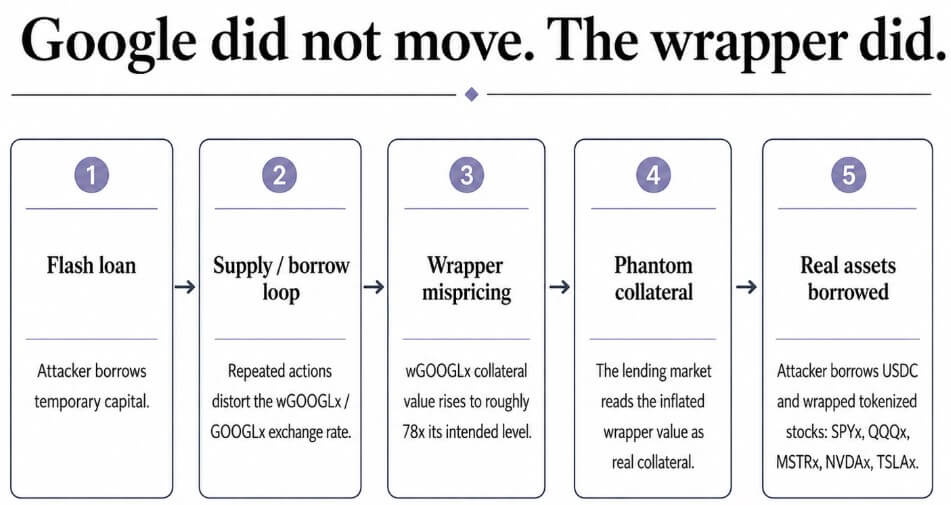
The assault manipulated the change price between wGOOGLx, a wrapped model of Edel’s tokenized Google inventory, and GOOGLx, the token it wraps. Edel stated the manipulation pushed wGOOGLx’s collateral worth to roughly 78 instances its right degree.
SlowMist traced the basis trigger to Edel’s worth supply, which used latestAnswer() to return an ERC-4626-style vault’s convertToAssets() price. That conversion price might be manipulated when an attacker controls sufficient of the underlying circulate, and Edel’s worth feed reads it instantly.
CertiK described the identical flaw from the lending facet: the attacker manipulated wGOOGLx’s collateral worth, which tracked its GOOGLx steadiness, then borrowed in opposition to the inflated worth.
GoPlus famous that the attacker used a flash mortgage to repeatedly provide and borrow, distorting the wGOOGLx/GOOGLx conversion price. The inflated collateral then supported actual borrowed property, together with 384,215 USDC and wrapped positions in SPYx, QQQx, MSTRx, NVDAx, and TSLAx.
Safety corporations revealed totally different estimates. Cyvers put the loss at roughly $353,000, GoPlus cited about $403,000 in losses and roughly $305,000 in attacker revenue, and CertiK put the drained funds at roughly $204,000.
The hole seems to mirror totally different measurements, together with dangerous debt, gross loss, and web attacker revenue.
The disconnect most likely comes from every agency measuring one thing totally different, reminiscent of dangerous debt, gross loss, or web revenue.
The essential failure sat within the change price between the wrapped token and its underlying counterpart, a relationship that Edel’s lending market priced as if it had been secure. Alphabet’s share worth didn’t drive the exploit.
The market in numbers
RWA.xyz places tokenized shares’ onchain worth at $1.7 billion, up 2.17% over the previous 30 days. Month-to-month switch quantity sits at $8.92 billion, and holders at over 396,000.
xStocks alone lists greater than 100 shares and ETFs throughout greater than 50 built-in platforms, with over $25 billion in whole transaction quantity. It describes itself as absolutely backed and open to plugging into any DeFi protocol with out permission.
Backed, the issuer behind xStocks, markets the tokens explicitly for DeFi use: lending tokenized Apple shares or borrowing in opposition to them with out promoting.
Kamino says it grew to become the primary main lending protocol to simply accept tokenized equities as collateral, permitting customers to deposit tokens reminiscent of SPYx, QQQx, GOOGLx, AAPLx, NVDAx, TSLAx, MSTRx, and HOODx to borrow stablecoins or earn yield.
Robinhood launched inventory and ETF tokens for EU clients in June 2025, then opened a public testnet for Robinhood Chain. The community is an Ethereum layer-2 constructed on Arbitrum, designed round tokenized real-world property together with equities, ETFs, and personal property.
The promoting level throughout all of this is identical: tokenized shares ought to transfer and join like every other crypto asset. Edel is a reminder that when they transfer like crypto, they’ll additionally break like crypto.
Market layerWhat it enablesExamples from the articleRisk Edel exposedAccessUsers achieve publicity to shares and ETFs onchain.Robinhood inventory and ETF tokens for EU clients; xStocks’ 100+ shares and ETFs.Authorized and issuer-level backing are mandatory, however not ample.TradingTokenized shares transfer throughout venues, chains, and DeFi platforms.xStocks throughout 50+ built-in platforms; $25B+ whole transaction quantity.Extra integrations create extra pricing and liquidity dependencies.CollateralUsers borrow in opposition to tokenized equities.Kamino accepting SPYx, QQQx, GOOGLx, AAPLx, NVDAx, TSLAx, MSTRx, HOODx.Wrapped variations, vault change charges, and oracle paths can turn into assault surfaces.Future derivativesTokenized equities turn into inputs for structured merchandise and leverage.Implied subsequent section as collateral markets mature.A wrapper or oracle failure can unfold past one lending market.
The disconnect between backing and security
A lending market costs a number of layers, such because the tokenized fairness itself, the wrapped model constructed on high of it, and the change price a vault makes use of to transform between the 2.
It additionally costs the oracle path that stories a price, the lending market’s personal borrowing limits, and whether or not that collateral can truly be bought throughout a interval of stress. Edel’s exploit sat nearly fully within the wrapper and oracle layers.
Utilizing a tokenized inventory as collateral provides a second pricing downside on high of the fairness itself. A protocol additionally has to cost each on-chain illustration constructed round that inventory, together with how a wrapper’s change price behaves beneath stress. That publicity comes from the collateral integration constructed round a tokenized inventory.
Flash loans, collateral manipulation, and ERC-4626 exchange-rate assaults have all proven up in DeFi exploits earlier than. This exploit’s novelty lies within the asset class these methods goal, and it seems to be one of many first clear tokenized-stock-collateral exploits on report.
How this performs out
Within the bull case, protocols spend the subsequent 12 months isolating wrapper danger. Which means capping how a lot collateral in a lending market can come from wrapped tokenized shares, separating issuer-level costs from wrapper change charges, and constructing oracle paths {that a} single flash mortgage can not transfer.
Tokenized equities then turn into credible collateral for conservative borrowing in opposition to liquid names like Apple, Nvidia, Tesla, and Google. Edel finally ends up remembered because the early failure that compelled higher design earlier than the class scaled.
Within the bear case, listings outrun the chance work. Extra venues settle for tokenized shares as collateral earlier than oracle design and wrapper isolation catch up.
The variety of wrapped tokens, bridges, and vaults constructed round every ticker retains multiplying quicker than anybody can audit them.
Alongside that path, extra exploits within the low a whole bunch of hundreds of {dollars} proceed to floor involving exchange-rate manipulation and skinny liquidity. Tokenized shares have turn into a safety flashpoint over how DeFi protocols use them as collateral.
The primary section of tokenized shares was entry: letting eligible customers maintain tokenized publicity to names reminiscent of Apple or Google. The second section was buying and selling, which concerned making that declare transfer throughout chains across the clock.
ScenarioWhat has to happenMarket outcomeWhat Edel turns into in hindsightBull case: safer collateral marketsProtocols isolate wrapper danger, cap collateral publicity, separate issuer costs from wrapper change charges, and harden oracle paths.Tokenized equities turn into credible collateral for conservative borrowing in opposition to liquid names like Apple, Nvidia, Tesla, Google, SPY, and QQQ.An early failure that compelled higher design earlier than the class scaled.Base case: slower collateral adoptionLending markets preserve tokenized shares in remoted swimming pools with conservative loan-to-value ratios and tight caps.Tokenized shares develop primarily as buying and selling property, whereas borrowing use instances broaden progressively.A warning label that slows leverage however doesn’t cease the market.Bear case: listings outrun danger controlsMore venues settle for tokenized shares and wrapped variants earlier than oracle design and wrapper isolation enhance.Extra small-to-mid exploits seem round exchange-rate manipulation, skinny liquidity, bridges, and vault accounting.The primary seen signal that tokenized-stock collateral grew to become a safety flashpoint.
Edel arrived at the beginning of the third section, collateral, the place holding a tokenized inventory additionally permits borrowing in opposition to it.
The primary two phases of tokenized shares rewarded whoever listed probably the most tickers or reached probably the most chains. The following one rewards whoever can worth a wrapped inventory accurately beneath stress, each time.


