

CleanSpark has signed a 20-year AI infrastructure lease, however nonetheless must finance an estimated $1.75 billion to $2.10 billion information middle construct.
The Bitcoin miner and information middle developer entered a 20-year triple-net lease for 175 megawatts of crucial IT load at its Sandersville, Georgia, campus on July 10. CleanSpark disclosed the settlement in a Kind 8-Okay on July 14 and estimates that the preliminary time period can have a contract worth of $6.6 billion and contribute about $330 million in common annual web working earnings.
CleanSpark’s estimate of $10 million to $12 million in landlord mission prices per MW implies a $1.75 billion to $2.10 billion construct.
That vary exceeds the $260.3 million of money and $925.2 million of company-defined Bitcoin HODL worth reported as of March 31, 2026, even when the 2 figures are added collectively. The HODL measure contains present and noncurrent Bitcoin, in addition to Bitcoin held by counterparties beneath collateral preparations, a composition distinct from that of unrestricted money.
The July lease announcement identifies no lender, dedicated financing quantity, pricing, sponsor fairness contribution, or draw schedule. Phased supply is predicted to start within the fourth quarter of 2027, whereas the total supply and rent-commencement schedules stay undisclosed. CleanSpark says the nameless tenant’s high-investment-grade credit score profile facilitates entry to financing. The eventual phrases will decide whether or not the mission is funded primarily towards the lease or pushes extra leverage, dilution or Bitcoin-collateral threat onto the corporate and its shareholders.
What CleanSpark truly signed
The Sandersville settlement is a binding infrastructure lease masking 175 MW, with annual escalators, a 20-year preliminary time period and two non-obligatory five-year extensions. The tenant is described solely as a high-investment-grade world expertise firm, with its id undisclosed.
CleanSpark estimates $6.6 billion in contract worth through the preliminary time period and as much as $11.6 billion if each five-year choices are exercised. The preliminary signed time period stays $6.6 billion; reaching $11.6 billion requires train of each choices.
Calling it a triple-net lease doesn’t imply CleanSpark can be on the hook to construct the mission. The 8-Okay states that the tenant bears the prices, costs, indemnities, and bills specified within the lease. CleanSpark individually estimates the owner mission prices at $10 million to $12 million per MW within the SEC-filed launch, leading to a calculated vary of $1.75 billion to $2.10 billion for 175 MW.
ItemAmount or timingWhat it representsInitial contract worth$6.6 billionCleanSpark estimate over the 20-year preliminary termValue with extensionsUp to $11.6 billionOnly if each five-year tenant choices are exercisedAverage annual NOI contributionAbout $330 millionCompany estimate for potential incomeLandlord mission price$1.75 billion to $2.10 billionCalculated from the corporate’s $10 million to $12 million per MW estimateMarch 31 stability sheet$260.3 million money; $925.2 million HODL worth; $1.788 billion long-term debtDated monetary place; excludes Sandersville financing termsDeliveryExpected to start This fall 2027Phased begin; full completion and precise hire schedule undisclosed
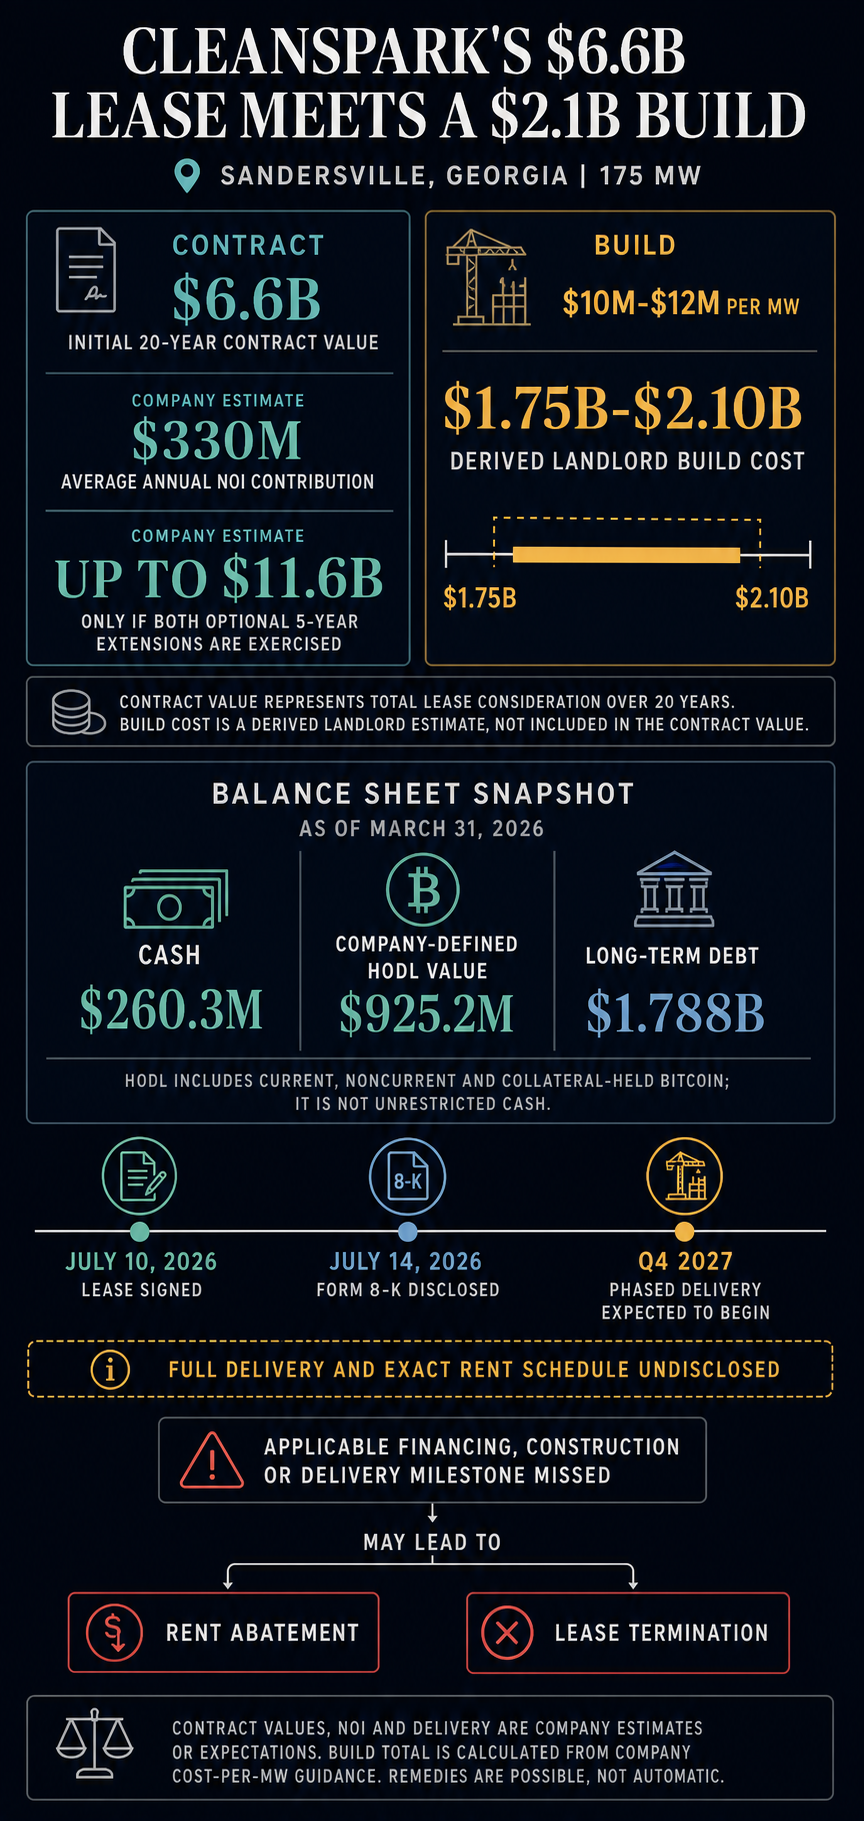
The contract worth is unfold over years, whereas the estimated NOI stays potential. A phased development program can also not require your complete mission price upfront. The figures set up the dimensions of the duty with out revealing when every greenback have to be funded.
The funding paths transfer threat in a different way
CleanSpark’s fiscal second-quarter outcomes present why Sandersville wants funding that matches the dimensions of the construct.
As of March 31, the corporate reported $260.3 million in money, $925.2 million in HODL worth, $1.788 billion in long-term debt, and $1.927 billion in complete liabilities. The calculated Sandersville price is roughly 6.7 to eight.1 instances the dated money stability, 1.9 to 2.3 instances the HODL worth, and roughly 98% to 117% of long-term debt. These figures present that the mission is just too massive for CleanSpark to fund with its current money.
CleanSpark additionally reported a $378.3 million web loss for the quarter ended March 31. The determine included a $224.1 million Bitcoin fair-value loss and a $38.8 million loss on Bitcoin collateral, based on its SEC-filed earnings launch. These market-linked objects can considerably have an effect on the reported stability sheet, making the online loss a poor proxy for quarterly money burn.
Bitcoin stays a possible supply of liquidity, collateral, or sale proceeds, relying on how a lot is encumbered and the extent of publicity the corporate desires to retain. Cash pledged to a lender can not additionally operate as an unencumbered reserve. CryptoSlate beforehand examined how collateral-held Bitcoin complicates the liquidity implied by CleanSpark’s headline HODL determine.
One believable state of affairs is mission financing constructed across the website and its tenant-backed lease. CleanSpark says the tenant’s credit score profile facilitates financing choices, and a long-duration lease could present lenders with a contractual cash-flow foundation for underwriting development. The protections would depend upon the precise package deal: sponsor ensures, company recourse, Bitcoin collateral, or a big sponsor fairness dedication might transfer threat again to CleanSpark.
The lease ties financing on to CleanSpark’s capacity to ship the mission. CleanSpark’s 8-Okay states that the corporate should meet relevant financing, development, and supply milestones, in addition to different covenants and circumstances. Miss a milestone and the hire might shrink or disappear completely, leaving the mission’s financing tied to CleanSpark maintaining the lease on monitor.
Funding Sandersville via CleanSpark’s company stability sheet would expose shareholders extra on to the associated fee. Further company debt would elevate leverage from a March 31 base of almost $1.8 billion in long-term debt. New frequent fairness or equity-linked securities might dilute current holders. Bitcoin gross sales would scale back treasury publicity and the asset base buyers could depend as liquidity. Bitcoin-backed borrowing might protect nominal coin possession whereas including collateral, margin, and liquidation threat.
CleanSpark’s $1.769 billion web carrying stability for zero-coupon convertible notes represents excellent debt. Its $400 million in unused Bitcoin-backed credit score strains had been undrawn as of March 31 and require Bitcoin collateral. CryptoSlate’s protection of the 2025 convertible financing provides context for the company route, whereas Hut 8’s AI landlord mannequin illustrates how mission debt and Bitcoin-backed bridge capital can coexist. CleanSpark’s eventual construction stays an open query.
The tenant’s credit score profile could help mission financing, however the eventual pricing, recourse, collateral, and fairness necessities will decide how a lot threat stays with CleanSpark.
Why the $6.6 billion worth stays conditional
The $6.6 billion headline nonetheless comes with strings hooked up. The financing, development, supply, and different milestones and covenants disclosed within the 8-Okay hyperlink the income alternative to CleanSpark’s capacity to execute. The cures are conditional: the submitting states that relevant failures could end in hire abatements or termination.
The timeline provides one other catch. CleanSpark expects phased deliveries to start in This fall 2027. It has not disclosed how rapidly the total 175 MW will comply with, when hire begins for every part, or whether or not the acknowledged common annual NOI displays a totally delivered campus. Utilizing $330 million as a run-rate from the primary day of This fall 2027 would overstate the disclosed timing.
The Texas deal will not be a part of CleanSpark’s signed contract pipeline. The identical tenant executed a letter of intent and exclusivity settlement masking CleanSpark’s 718-acre Texas portfolio and as much as 885 MW of what CleanSpark describes as secured and deliberate energy capability. That association will not be a accomplished lease.
Sandersville has superior CleanSpark from an AI infrastructure pitch to contracted execution, whereas the decisive capital phrases stay undisclosed.
The financing phrases and the trail to This fall 2027 will reveal who is de facto carrying the danger: CleanSpark’s Bitcoin holdings, its stability sheet, or its shareholders.


